Money Mindset

Psychology of spending and saving

Loading...

How to Rebuild Financial Confidence After Making Money Mistakes

A costly purchase, missed payment, unmanageable loan or investment loss can make you question every financial decision you make. The result is often not just a smaller bank balance. It is a loss of financial confidence: you may avoid opening banking apps, delay decisions or ask others to decide for you.

Learning how to rebuild financial confidence is not about pretending the mistake did not matter. It is about responding clearly, taking a few reliable actions and collecting proof that you can handle money again. This practical process can help you recover from money mistakes without shame.

Why Money Mistakes Can Damage Your Financial Confidence

Money decisions carry practical consequences and emotional weight. A mistake may affect your housing, family plans, debt level or sense of security. It can also trigger harsh conclusions such as “I am terrible with money” or “I cannot trust myself.”

Those conclusions are understandable, but they are not useful facts. One poor decision can happen because of incomplete information, stress, urgency, misleading advice or a period when expenses exceeded income. Even a repeated pattern is a behaviour to change, not a permanent identity.

Low financial self-trust can create a cycle: avoidance means you have less information, less information makes decisions feel riskier, and the next decision is more likely to feel overwhelming. The way out is not a perfect plan. It is a simple routine that makes money visible and decisions slower and safer.

Separate a Bad Financial Decision From Your Identity

Use precise language when describing what happened. Instead of saying, “I am irresponsible,” say, “I took on a payment I could not comfortably afford.” Instead of, “I always mess up,” say, “I did not check the total cost before signing.”

This is not wordplay. A label makes change feel impossible; a specific description points to a solution. If the problem was an unaffordable monthly payment, the solution may be to review fixed costs and ask the provider about options. If the problem was impulse spending, the solution may be a 24-hour waiting rule and a separate spending account.

Try this replacement statement: “I made a decision I would handle differently now. I can learn the skill or build the system that was missing.” It leaves room for accountability without turning recovering from money mistakes into a verdict on your character.

Complete a No-Shame Review of What Happened

A short review turns a vague regret into useful information. Set aside 30 minutes, gather statements or contracts, and write answers without trying to defend or punish yourself. If the figures are difficult to face, start with one account or one bill.

Your money mistakes recovery worksheet

  1. Name the event: What happened? For example: “I used a credit card for €1,200 of expenses during a difficult month.”
  2. Measure the current impact: What is the balance, interest rate, payment date, fee or lost income? Use exact figures where possible.
  3. Identify the conditions: What was happening at the time? Consider income changes, stress, pressure, lack of information or automatic payments.
  4. Find the decision gap: What check, limit or knowledge would have made a better outcome more likely?
  5. Choose one repair action: This could be calling a lender, cancelling a subscription, arranging a payment plan or moving money to an emergency fund.
  6. Choose one prevention rule: Make it specific enough to use next time.

Keep the review factual. The purpose is not to relive the mistake; it is to create a response plan. If debt payments are becoming hard to meet, contact the lender early. In many European countries, free or low-cost debt advice services can explain your options and help you communicate with creditors.

Create Small Money Promises You Can Keep

Financial confidence grows when you keep commitments to yourself. Start smaller than you think you need to. A promise that is completed every week is more valuable than an ambitious plan abandoned after three days.

Choose one or two promises linked to your current reality, not your ideal future. Put them on a calendar and make them measurable.

SituationSmall promiseWhy it builds trust
You avoid checking balancesCheck your main account every Tuesday for five minutes.Reduces avoidance without creating overwhelm.
You often overspend before paydayTransfer €25 each week into a bills or savings pot.Creates a repeatable cushion.
You make rushed purchasesWait 24 hours before non-essential purchases over €50.Creates space to decide calmly.
You have missed due datesSet reminders seven days before every payment date.Turns memory into a reliable system.
You are repaying debtMake the minimum payment by direct debit and add €10 after each payday.Protects payment history while making visible progress.

Adjust the amounts to your currency, income and obligations. If €25 is unrealistic, start with €5. The point is consistency, not performance. As you keep promises, financial self-trust becomes evidence-based rather than dependent on feeling motivated.

Use Simple Decision Rules to Prevent Repeat Mistakes

Willpower is unreliable when you are tired, anxious or pressured. Decision rules reduce the number of choices you have to make in the moment. Write your rules where you can see them, and make them relevant to the mistake you want to avoid repeating.

  • Do not borrow for a purchase until you know the total amount repayable, interest rate and monthly payment.
  • For contracts lasting more than 12 months, wait 48 hours and compare at least two alternatives.
  • Do not invest money needed within the next three to five years.
  • Check whether a new monthly cost still fits after rent, utilities, food, transport and minimum debt payments.
  • Discuss any joint financial commitment above an agreed amount with your partner first.
  • Keep a small buffer in your current account before making discretionary purchases.

These rules do not eliminate risk, and they should not stop you from making normal life decisions. They simply provide guardrails when emotions or sales pressure are high. This is a practical part of how to improve your relationship with money: you stop relying on panic, guilt or optimism and start using a repeatable process.

Track Evidence That You Are Making Progress

After a mistake, your brain may focus only on what went wrong. Counter that tendency by tracking a few useful signs of progress. Do this weekly or monthly, not every hour.

  • Number of bills paid on or before the due date
  • Days since you checked your accounts and budget
  • Amount saved, even if it is small
  • Debt balance or number of repayments completed
  • Times you used your waiting rule before buying
  • Money conversations or calls you completed instead of avoiding

A free budget app such as WhizBudget can make this easier by giving you one place to record spending, upcoming bills and savings goals. The aim is not to monitor every cent perfectly. It is to see patterns early enough to make a calm adjustment.

Review the evidence with two questions: “What worked?” and “What needs a smaller or clearer system?” Avoid asking, “Why am I still bad at this?” Progress can include stabilising, asking for help and stopping a problem from getting worse.

What to Do When a New Financial Setback Happens

A setback does not erase your progress. An unexpected repair, reduced work hours or overspending weekend is information that your plan needs attention. Respond within 24 to 72 hours if possible, before avoidance grows.

  1. Pause the self-criticism. Name the event in one factual sentence.
  2. Protect essentials. Check housing, utilities, food, transport, insurance and minimum debt payments first.
  3. Get the real number. Look at the account balance, bill amount and due date rather than guessing.
  4. Take one stabilising action. Delay a non-essential expense, move money, contact a provider or update your budget.
  5. Review the system later. Ask whether the event was unavoidable, a planning gap or a rule that needs changing.

For example, if a €300 car repair empties your savings, the immediate goal may be arranging payment terms and pausing extra debt repayments for one month. The later goal may be building a vehicle repair category into your savings. Neither step requires shame.

When to Get Professional Help With Money Decisions

Some situations need more than a personal budget. Seek qualified help if you are missing essential payments, using new credit to repay old credit, facing enforcement action, dealing with gambling-related spending, or feeling unable to cope with financial anxiety.

Look for a regulated financial adviser when you need investment, pension, tax or complex planning advice. For debt, use a reputable non-profit debt advice service or a recognised local consumer organisation. Check credentials and fees before sharing information. A professional can provide options; you still remain part of the decision process, which supports rather than replaces your financial confidence.

FAQs About Rebuilding Financial Confidence

How long does it take to rebuild financial confidence?

It depends on the situation, but you can begin rebuilding it within weeks by keeping small promises and facing key numbers. Larger debt or income problems may take longer to resolve, yet confidence can grow before the final balance is paid.

What is the first step after making a big money mistake?

Get clear on the current facts: the balance, due dates, interest or fees, and essential bills. Then take one repair action, such as contacting the provider or setting up a realistic payment plan.

How can I stop avoiding my bank account?

Set a short, scheduled check-in once a week. Start by viewing only your balance and upcoming bills. Increase the detail gradually as the routine becomes less stressful.

Can I rebuild financial self-trust while paying off debt?

Yes. Paying debt consistently, even in small amounts, is strong evidence that you can follow a plan. Track on-time payments and balance reductions, not only the total remaining debt.

What if my partner does not trust my money decisions anymore?

Focus on transparent actions rather than promises. Share a simple budget, agree spending limits, schedule regular check-ins and follow through over time. If conflict is severe, a financial counsellor or relationship therapist may help.

Should I save money or repay debt after a mistake?

Usually, protect minimum debt payments and build a small emergency buffer while prioritising high-interest debt. The right balance depends on interest rates, job security and access to credit, so seek debt advice if payments are unaffordable.

Build Confidence Through the Next Good Decision

You do not need to prove that you will never make another money mistake. You need a workable way to notice problems, respond early and keep a few promises to yourself. Start with the no-shame review, choose one small action for this week and record the result.

WhizBudget is a free budget app that can help you see spending, organise bills and track the habits that rebuild trust over time. Open your budget today and make the next good decision easier.

How to Stop Avoiding Your Finances: A Practical Plan for Money Anxiety

If checking your bank balance makes your stomach drop, you are not irresponsible or bad with money. You may be caught in a common cycle: money anxiety makes finances feel threatening, so you avoid them; avoidance then creates more uncertainty, fees, missed deadlines, and stress.

The way to stop avoiding finances is not to become perfectly organised overnight. It is to make contact with the facts in small, safe steps and build a routine that keeps problems visible before they become emergencies. This practical plan can help you face your finances without turning one difficult afternoon into an exhausting overhaul.

What Financial Avoidance Looks Like in Everyday Life

Financial avoidance is any habit that delays information or decisions about money because they feel uncomfortable. It can happen at every income level. Sometimes it starts after an expensive month, a job change, debt problem, or unexpected bill. Other times, it is simply the result of never having a manageable money routine.

  • Not opening bank, credit card, tax, or utility letters.
  • Delaying a look at your current account balance until payday.
  • Ignoring payment reminders, overdraft notices, or debt statements.
  • Avoiding conversations with a partner about shared expenses.
  • Putting off cancelling subscriptions or changing a costly contract.
  • Making small purchases for a temporary mood lift, then avoiding the total.
  • Thinking about a budget often but never writing one down.

These behaviours are understandable attempts to get relief from discomfort. The problem is that they usually offer only short-term relief. A missed direct debit, late-payment charge, or growing overdraft can make the next check feel even harder.

Why Money Anxiety Makes You Avoid Your Bank Account

Money anxiety is the persistent worry, dread, or physical tension linked to finances. Your brain may treat a banking app, unopened bill, or debt email as a threat. Avoiding it reduces the feeling briefly, which teaches your brain to repeat the avoidance next time.

There may also be shame in the background. You might tell yourself that you should already know how to manage money, that everyone else is coping, or that one bad decision has ruined everything. Those thoughts are painful, but they are not financial facts. Money management is a skill, and skills can be rebuilt at any point.

Start by lowering the goal. You do not need to solve every money issue today. Your only task is to get an accurate snapshot and take the next useful action.

How to Face Your Finances Without Getting Overwhelmed

Use a low-pressure first-day reset. Set a timer for 20 minutes, choose a private place, and have a glass of water nearby. If possible, avoid doing this late at night when you are tired or after an argument. The purpose is awareness, not self-criticism.

  1. Gather only the essentials: your bank app, recent bills, debt or credit statements, and a note-taking app or paper.
  2. Check available cash: write down the balance in each current, savings, and credit account. Do not judge the numbers.
  3. Check the next seven days: list bills, direct debits, loan payments, and income due before next week.
  4. Flag urgent items: overdue bills, an unarranged overdraft, a declined payment, a final reminder, or a payment due today.
  5. Take one action: pay, call, reschedule, cancel, or make a note to contact the provider.

Stop when the timer ends, even if your list is incomplete. Ending on time shows you that how to face your finances can be contained. You can return tomorrow. If seeing balances feels too intense, ask a trusted person to sit with you while you log in, without taking control of your decisions.

Create a 15-Minute Weekly Money Check-In

A short recurring appointment is one of the most effective money management habits. Choose the same time each week, such as Sunday afternoon or the day after payday. Add it to your calendar and keep the scope deliberately small. Regular contact matters more than a complicated spreadsheet.

MinuteTask
1–3Check current account balance and available credit. Note income received since the last check-in.
4–6Review transactions. Mark anything unfamiliar and remove or pause one unnecessary recurring cost if needed.
7–9Look ahead 14 days for direct debits, rent, mortgage, utilities, transport, and debt payments.
10–12Update a simple list of balances and due dates. Check whether enough money is set aside.
13–15Choose one next action and schedule it: transfer money, contact a provider, or compare a bill.

Use a free budget app such as WhizBudget to keep your spending, upcoming bills, and goals in one place. The aim is not to monitor every cent perfectly. It is to make your weekly check-in quick enough that you will actually do it.

List Your Most Urgent Financial Decisions

When everything feels urgent, prioritise by consequence. Protect essentials first: housing, energy, food, transport needed for work or care, insurance required by law or contract, and payments that could lead to serious penalties. Then deal with costs that grow quickly, such as unarranged overdrafts and high-interest credit.

PriorityExamplesFirst step
Act todayOverdue rent or mortgage, energy disconnection warning, unarranged overdraft, court or tax noticeContact the organisation immediately and ask about a payment arrangement or support options.
Act this weekCredit card due date, personal loan payment, overdue mobile or internet billPay what you can, review the due date, and ask before missing a payment.
Plan this monthSubscriptions, insurance renewal, non-essential purchases, savings goalsCompare, cancel, negotiate, or set a realistic spending limit.

Do not ignore letters because you cannot pay the full amount. Many creditors and service providers would rather discuss options early than pursue a missed payment later. Ask what payment plans, hardship support, interest freezes, or due-date changes may be available. Consumer protections and support services differ across European countries, so check your local independent debt-advice organisation.

Separate Facts From Fear-Based Money Thoughts

Overcoming money stress gets easier when you distinguish a number from the story attached to it. Write the worry down, then answer it with evidence and one practical action.

  • Fear-based thought: “I have no idea where my money goes; it is hopeless.”
    Fact: “I have not reviewed this month’s transactions yet.”
    Action: Review the last seven days and group spending into essentials, flexible costs, and subscriptions.
  • Fear-based thought: “One missed payment means I have ruined my finances.”
    Fact: “I missed one payment and need to check the fee and contact the provider.”
    Action: Call today and make a plan.
  • Fear-based thought: “I will never clear this debt.”
    Fact: “I owe a specific amount at a specific interest rate.”
    Action: List balances, minimum payments, and APRs, then seek advice if repayments are unaffordable.

This is not about pretending that a difficult balance is fine. It is about replacing vague catastrophe with information you can act on.

Build a Simple System for Bills, Balances, and Due Dates

Complex systems often fail when life gets busy. Build a simple system you can maintain in 15 minutes. Keep one list, whether on paper, in a spreadsheet, or in an app, with these headings: account or provider, amount due, due date, payment method, and status.

Where possible, keep bill money separate from day-to-day spending. You could use a dedicated bills account, a savings pot, or clearly labelled categories in WhizBudget. Transfer a set amount after each payday so rent, utilities, insurance, and debt minimums do not compete with everyday purchases.

Set reminders three to five days before manual payments are due. Direct debits can reduce missed dates, but review them regularly so you know what is leaving your account and can avoid insufficient-funds charges. If income is irregular, plan from your lowest reliable monthly income and treat stronger months as an opportunity to build a buffer.

Choose One Financial Action at a Time

A long financial to-do list can trigger more financial avoidance. Instead, make actions tiny and specific. “Sort out debt” is overwhelming; “open the credit card statement and write down the minimum payment” is doable.

Examples of a next action include:

  • Transfer €20, ÂŁ20, or your local equivalent into a bills pot.
  • Open one envelope or one secure message.
  • Cancel one unused subscription.
  • Call a provider and ask for the balance, due date, and available repayment options.
  • Set a reminder for your weekly check-in.
  • Compare the interest rate on two debts.

After completing an action, record it and stop. Progress is built through repeated contact with your finances, not through punishment or marathon budgeting sessions.

When to Get Help With Serious Money Anxiety

Normal financial stress can improve with a clear plan and a few consistent habits. Seek extra support if anxiety is affecting sleep, work, relationships, eating, or your ability to complete basic tasks. It is also worth speaking to a qualified mental health professional if you have panic attacks, persistent low mood, compulsive spending, or thoughts of harming yourself.

For the money problem itself, contact a free, independent debt-advice service or consumer advice organisation in your country. They can help you understand priority debts, communicate with creditors, and assess repayment options. If you are in immediate danger or at risk of self-harm, contact local emergency services or a crisis helpline now.

FAQs About Financial Avoidance and Money Anxiety

How do I stop being scared to check my bank account?

Start with a timed five-minute check and focus only on the balance and payments due in the next week. Take one small action afterwards, such as moving money for a bill. Repeat weekly so checking becomes routine rather than an emergency event.

What should I do first if I have ignored bills for months?

Open the newest letters and messages first, then identify any final notices, overdue housing or energy costs, tax demands, overdrafts, and high-interest debt. Contact providers before making assumptions about what they can offer.

Is financial avoidance a sign of being bad with money?

No. Avoidance is often a stress response, especially after uncertainty, debt, or difficult past experiences. It can still create problems, but it is a behaviour that can be changed with small routines and support.

How often should I review my finances?

A 15-minute weekly review works well for most people, alongside a longer monthly review of income, spending, debt, and savings goals. Check more often temporarily if your balance is tight or bills are overdue.

Should I pay off debt or build savings first?

Keep essential bills current and try to build a small emergency buffer while making at least the required debt payments. High-interest debt usually deserves extra payments once you have prevented immediate crises. Get independent debt advice if minimum payments are not affordable.

Can a budget app help with money anxiety?

Yes, if it makes the facts easier to see without demanding perfection. A simple app can show upcoming bills, spending categories, and progress toward a small buffer, reducing the need to hold every detail in your head.

Take the Next Small Step

You do not need confidence before you start. Confidence comes from opening one statement, making one call, and keeping one short appointment with your money each week. Begin with the 20-minute reset today, then protect your progress with a simple routine.

WhizBudget is a free budget app designed to help you see spending, plan bills, and build calmer money management habits. Start your first check-in now and turn financial uncertainty into a clear next step.

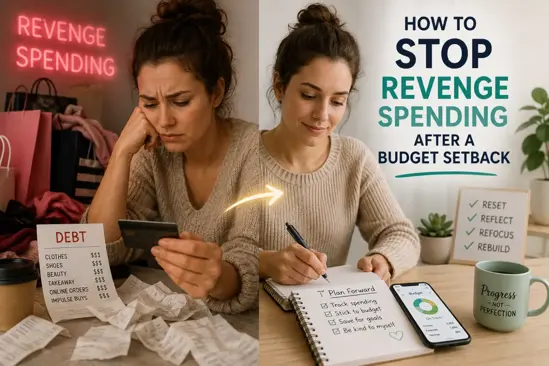
How to Stop Revenge Spending After a Budget Setback

Revenge spending is what happens when your budget starts to feel like a punishment, so you spend to feel free again. It often shows up after a strict saving period, a stressful week, an unexpected bill, or one mistake that makes you think, I have already ruined the budget, so I might as well enjoy myself.

If you have ever saved carefully for weeks and then spent too much in one weekend, you are not lazy or bad with money. You are reacting to pressure. The goal is not to become perfect. The goal is to understand the pattern, put a pause between emotion and payment, and reset your budget without shame.

This guide explains how revenge spending works, why it happens, and how to stop impulse spending after a budget setback using practical steps you can apply today.

What Revenge Spending Is and Why It Happens

Revenge spending is a form of emotional spending. It usually happens when you spend money to push back against restriction, stress, disappointment, or frustration. The purchase feels like a reward, a protest, or a way to take back control.

For example, you may stick to a tight food budget all month, then order expensive takeaway twice because you feel tired of saying no. Or you may avoid shopping for weeks, then buy clothes online after a bad day because you feel you deserve something nice.

The phrase is important because the spending is not only about the item. It is about the emotion behind the item. You are not just buying trainers, a dinner, a gadget, or a weekend trip. You are buying relief, comfort, freedom, or proof that your life is not only bills and limits.

Revenge spending often becomes stronger when a budget is too strict. If your plan allows no fun money, no flexibility, and no space for real life, your brain may eventually rebel. This is especially common when prices are rising, rent or mortgage payments are high, and normal living costs already feel heavy.

Common Triggers That Lead to Revenge Spending

Revenge spending usually has a trigger. Once you can name your triggers, you can build better barriers around them.

  • A budget setback: You overspend on groceries, miss a savings goal, or forget a bill. The mistake makes you feel like the whole month is ruined.
  • Feeling restricted: You cut everything at once and start to feel deprived. The spending becomes a reaction to too many no answers.
  • Stress or burnout: Work pressure, family responsibilities, or lack of rest can make quick purchases feel like an easy reward.
  • Social pressure: A dinner, trip, gift, or night out can push you to spend more than planned because you do not want to feel left out.
  • Overspending after saving money: After reaching a savings goal, you may spend more than usual because you feel you have earned a break.
  • Online shopping prompts: Sale emails, limited-time discounts, buy now pay later offers, and social media ads reduce the time you have to think.

These triggers are common across Europe, especially where card payments, mobile wallets, instant bank transfers, and delivery apps make spending almost invisible. The easier it is to pay, the more important it is to create a deliberate pause.

How Revenge Spending Damages Your Budget and Financial Confidence

The immediate problem with revenge spending is obvious: money leaves your account. The deeper problem is that it can damage your confidence. You start to think, I cannot stick to a budget, or I always fail. That belief makes it harder to restart.

Revenge spending can also create a cycle:

  1. You build a strict budget.
  2. You feel restricted or stressed.
  3. You overspend to feel better.
  4. You feel guilty or discouraged.
  5. You make the next budget even stricter to compensate.
  6. The pressure builds again.

This cycle is exhausting. It can also lead to late payments, overdraft fees, credit card balances, and buy now pay later instalments that reduce next month’s income before the month even starts.

A healthier approach is to stop treating every budget setback as failure. A budget is a working plan, not a moral test. When something goes wrong, you adjust it. You do not need to start over from zero every time.

Step 1: Identify the Emotion Behind the Purchase

Before you try to stop spending, ask what the purchase is trying to do for you. This step matters because the same item can have different emotional meanings.

A takeaway meal could mean you are tired and need rest. A clothing order could mean you want confidence. A new phone could mean you feel behind compared with friends. A weekend trip could mean you need a break from routine.

Use this simple check before buying:

  • What happened today that made me want this?
  • Am I buying because I need it, or because I want to change how I feel?
  • Will this purchase still feel useful in 24 hours?
  • What problem am I hoping this money will solve?

You do not need to judge the answer. Just name it. Try one of these quick labels: stressed, bored, tired, lonely, embarrassed, deprived, angry, proud, disappointed, or anxious.

Here is a practical example:

You planned to spend €60 on eating out this month. By the 12th, you have already spent €55. After a long workday, you want to order food for €28. The surface reason is hunger. The emotional reason might be exhaustion. If exhaustion is the real issue, a lower-cost option may work: a simple supermarket meal, leftovers, or a planned low-effort dinner from the freezer.

The aim is not to ban comfort. The aim is to choose the kind of comfort that does not create another problem tomorrow.

Step 2: Create a 24-Hour Spending Pause Rule

A spending pause is one of the most effective ways to stop impulse spending. It creates distance between the urge and the payment. You are not saying no forever. You are saying not yet.

Use a 24-hour rule for non-essential purchases above a set amount. The amount should fit your income. For some people, it may be €20. For others, it may be €50 or €100.

During the pause, keep the item in the basket, write it in a note, or save the link. Do not check out immediately. Many urges fade when they are not fed by urgency.

Use these scripts when you feel the urge to buy:

  • I can buy this tomorrow if I still want it and it fits the budget.
  • This is not a no. It is a pause.
  • I am allowed to want this without buying it right now.
  • If it is still a good idea tomorrow, I can plan for it properly.
  • A discount is not a saving if I did not plan to spend the money.

For online shopping, remove stored card details where possible. Turn off one-click payments. Unsubscribe from sale emails that trigger emotional spending. If you use mobile wallets, consider moving shopping apps away from your home screen.

For in-person spending, try leaving the shop and walking for ten minutes before paying. If the purchase is still important after the walk, check your budget category first.

Step 3: Build a Small Guilt-Free Spending Category

Many people overspend because their budget has no pressure valve. If every euro is assigned to bills, debt, groceries, and savings, life can start to feel like a financial lockdown. A small guilt-free spending category helps prevent rebellion.

This category is for low-stakes enjoyment. You can use it for coffee, books, takeaway, hobbies, beauty items, games, or small treats. The rule is simple: once the money is in that category, you can spend it without guilt. When it is gone, you pause until the next budget period.

Here is a simple example:

Monthly income after taxSuggested guilt-free amountExample use
€1,500€30 to €50Coffee, one meal out, small personal item
€2,200€60 to €100Takeaway, hobby costs, social plans
€3,000+€100 to €180Dining, entertainment, flexible treats

These numbers are only examples. If your rent, childcare, transport, or debt payments are high, start smaller. Even €10 or €20 can help because it gives your brain permission to enjoy something without breaking the plan.

The key is to make this category visible. A tool like WhizBudget can help you separate essential bills from flexible spending so you can see what is genuinely available before you buy.

Step 4: Use a Budget Reset Instead of Starting Over

One of the biggest mistakes after a budget setback is declaring the whole month ruined. That thought often leads to more spending. A budget reset is better than starting over because it works with the money you still have.

Use this same-day mini reset plan when you overspend:

  1. Check your current account balance. Do not estimate. Open your banking app and look at the actual number.
  2. List bills still due before payday. Include rent, mortgage, utilities, phone, insurance, subscriptions, loan payments, and direct debits.
  3. Protect essentials first. Set aside money for housing, food, transport, medicine, and minimum debt payments.
  4. Find the shortfall. Compare what you need with what is left.
  5. Adjust flexible categories. Reduce eating out, shopping, entertainment, or non-urgent personal spending.
  6. Choose one action today. Return an item, cancel a subscription, move a social plan to a cheaper option, or cook from what you already have.

Here is a quick example of a reset after overspending:

CategoryOriginal planAfter setbackReset action
Groceries€300€340Use pantry meals for one week
Eating out€100€85 spentLimit remaining spend to €15
Shopping€80€120 spentReturn €40 item if possible
Savings€250At riskSave €200 this month, restore next month

Notice that the reset does not demand perfection. It protects the most important parts of your finances and keeps you moving.

Step 5: Replace Spending Rewards With Non-Spending Rewards

It is normal to want a reward after doing something hard. The problem is when every reward costs money. If you only celebrate progress by spending, saving money becomes a trigger for overspending after saving money.

Create a list of rewards that do not involve shopping. Make the list before you need it, because it is harder to think clearly when you are stressed.

  • Watch a film or series you already have access to.
  • Take a long walk in a nice area or park.
  • Have a home coffee or tea ritual without rushing.
  • Borrow a book from the library.
  • Call a friend instead of meeting somewhere expensive.
  • Use a free museum day or local community event.
  • Take an evening off from chores if possible.
  • Cook a simple comfort meal at home.

If you want a paid reward, plan it into the budget. For example, if you reach a savings milestone, set aside €20 for a treat rather than spending €150 impulsively. Planned enjoyment is not the same as revenge spending. It is part of a sustainable money mindset.

Step 6: Track Patterns Without Shame

Tracking is not about proving you failed. It is about collecting useful information. If you treat every purchase as evidence that you are bad with money, you will avoid looking at your spending. Avoidance makes the pattern worse.

Instead, track three things:

  • What you bought: Keep it simple. Food delivery, clothes, taxi, gifts, apps, or home items.
  • What you felt before buying: Tired, bored, stressed, restricted, lonely, excited, or angry.
  • What happened afterwards: Relief, regret, no change, useful purchase, or more stress.

After two to four weeks, look for patterns. You may notice that you spend most on Fridays after work, after arguments, before payday, or after checking social media. You may discover that certain shops, apps, or friends make spending easier.

Once you know the pattern, choose one barrier. For example:

  • If you order takeaway when tired, keep two easy meals at home.
  • If you shop after scrolling, remove shopping apps from your phone.
  • If you overspend on nights out, take a fixed amount and use a separate card.
  • If you spend after a budget mistake, do a 15-minute reset before making any new purchase.

WhizBudget can make this easier by showing your categories clearly, so you can spot where emotional spending is happening without manually rebuilding your budget every week.

When Revenge Spending Becomes a Bigger Financial Problem

Occasional emotional spending is common. But revenge spending can become a serious problem if it starts to affect your ability to pay bills, save, or sleep well.

Look for these warning signs:

  • You hide purchases from a partner or family member.
  • You regularly use overdrafts, credit cards, or buy now pay later for non-essentials.
  • You feel unable to stop even when you know the purchase will cause problems.
  • You miss rent, mortgage, utility, tax, or debt payments because of discretionary spending.
  • You shop to cope with anxiety, sadness, anger, or low self-worth most weeks.
  • You avoid opening bank statements or budgeting apps because you feel afraid.

If this sounds familiar, the solution may need more support than a simple budget adjustment. Consider speaking with a free debt advice charity, a financial counsellor, or a qualified mental health professional. Many European countries have non-profit debt advice services that can help you deal with arrears, creditor contact, and repayment options.

Getting help is not a sign of failure. It is a practical step to stop the cycle and protect your future income.

A Realistic Mini Reset You Can Use Today

If you have already overspent and feel tempted to keep going, use this 30-minute reset:

  1. Pause all non-essential spending for the next 24 hours. Food, transport, medicine, and bills are allowed. Everything else waits.
  2. Open your bank account and write down your balance. Include cash, current account money, and any pending card payments you can see.
  3. Write the next payday date. Count how many days you need the money to last.
  4. List must-pay expenses before payday. Include direct debits and standing orders.
  5. Set a daily spending limit. After essentials, divide the remaining flexible money by the number of days left.
  6. Choose one repair action. Return something, cancel an unused subscription, reduce a planned expense, or move money from a lower-priority category.
  7. Plan one no-spend reward tonight. Replace the urge to punish yourself with a calm activity that does not cost money.

This reset is not about making the month perfect. It is about stopping the slide. A small correction today can prevent a much larger problem next week.

FAQs

What is revenge spending?

Revenge spending is when you spend money in reaction to feeling restricted, stressed, deprived, or discouraged. It often happens after a budget setback or a long period of saving.

Is revenge spending the same as emotional spending?

Revenge spending is a type of emotional spending. Emotional spending can happen for many reasons, such as sadness, boredom, stress, or excitement. Revenge spending is specifically linked to pushing back against restriction or frustration.

How do I stop impulse spending after a bad budget month?

Start with a 24-hour pause on non-essential purchases. Then check your real account balance, protect essential bills, reduce flexible categories, and choose one repair action such as returning an item or cancelling a planned expense.

Should I cut all fun spending when I overspend?

Usually, no. Cutting all fun spending can make revenge spending worse. Instead, create a small guilt-free category that fits your income and current obligations. This gives you some freedom while keeping limits clear.

Why do I overspend after saving money?

Overspending after saving money often happens because saving feels like restriction. When you reach a goal, your brain wants a reward. Plan a small reward in advance so celebration does not turn into uncontrolled spending.

Can budgeting apps help with revenge spending?

Yes, if they help you see your categories clearly and make decisions before spending. A budgeting tool like WhizBudget can show what is left for flexible spending, which makes it easier to pause and reset after a setback.

Conclusion

Revenge spending is not a character flaw. It is a signal that your budget, stress level, or reward system needs adjustment. The answer is not harsher rules. The answer is a better pause, a more realistic plan, and a reset process that helps you recover quickly after mistakes.

Start small. Identify the emotion behind the purchase, use a 24-hour spending pause, add a guilt-free spending category, and reset your budget instead of abandoning it. These steps help you rebuild financial confidence one decision at a time.

If you want a clearer way to manage categories, track spending, and recover from budget setbacks, try WhizBudget. Build a budget that supports real life, not one that makes you want to rebel against it.

The New Money Mindset: Why Financial Wellness Is the Biggest Trend in 2026

For years, money advice focused on one thing: build wealth as fast as possible. Save aggressively. Invest heavily. Earn more.

But in 2026, a new money mindset is taking over.

Today, people care less about chasing wealth — and more about feeling secure, calm, and in control of their finances. This shift is redefining how we think about money, success, and financial habits.

Welcome to the era of financial wellness.


What Is the New Money Mindset?

The modern money mindset isn’t just about numbers.

It’s about your relationship with money.

Younger generations, especially, are treating finances as part of self-care — similar to mental health, fitness, or productivity habits. Research shows that many now see managing money as something that improves overall quality of life, not just future wealth.

Instead of asking:

“How much money can I make?”

People are asking:

  • Does my money reduce stress?
  • Does it align with my values?
  • Does it give me freedom and stability?

That’s a massive mindset shift.


Why This Trend Is Growing So Fast

Several powerful forces are driving this change.

1. Money Stress Is at an All-Time High

Financial anxiety is now widespread. Many young adults report worrying about rising costs, job uncertainty, and housing affordability.

In fact:

  • People spend nearly 4 hours per day thinking about money.
  • More than half say they’re thinking about it more than ever.

When money takes up that much mental space, mindset becomes critical.


2. Younger Generations Value Stability Over Wealth

Gen Z especially is reshaping financial culture.

Studies show:

  • 82% feel positive about their savings progress
  • Many openly discuss money with friends
  • Emotional satisfaction matters more than net worth

This is a major shift from older generations who often viewed money as a private or purely numerical topic.


3. Financial Success Now Means “Less Stress”

For many people, being financially healthy doesn’t mean being rich.

It means:

  • Not living paycheck-to-paycheck
  • Feeling secure about emergencies
  • Having control over spending decisions

In other words, peace of mind has become the new definition of wealth.


The Biggest Money Mindset Trends Right Now

Here are the most important trends shaping financial thinking today.


1. “Soft Saving” Instead of Strict Budgeting

One of the fastest-growing trends is called soft saving.

This approach focuses on:

  • Small, consistent progress
  • Flexible goals
  • Guilt-free financial habits

Instead of rigid rules, people track small wins - like saving $5 daily or automating tiny deposits.

The idea: saving shouldn’t feel painful.


2. “Loud Budgeting” and Financial Transparency

The opposite trend is loud budgeting.

This mindset encourages openly talking about financial priorities.

Examples include:

  • Saying “I can’t afford that right now”
  • Sharing savings goals publicly
  • Building accountability through community

This breaks old money taboos and helps people stay motivated.


3. Treating Money Like Self-Care

Today, financial habits are part of wellness routines.

Many people now:

  • Track spending mindfully
  • Reflect on emotional spending triggers
  • Align money with life values

Nearly 58% say actively managing money improves their quality of life.

That’s a huge shift from traditional budgeting mindsets.


4. Investing for Control — Not Just Returns

Young adults are also investing differently.

Instead of focusing purely on profit, they see investing as a way to:

  • Gain financial independence
  • Reduce uncertainty
  • Build long-term security

This reflects a psychological shift toward resilience and flexibility.


What This Means for Your Financial Journey

Understanding this new mindset can transform your finances.

Here’s what it suggests:

Focus on consistency, not perfection

Small habits matter more than big financial moves.


Align money with your values

Spend intentionally on what improves your life.


Reduce financial anxiety first

Stability and security should come before aggressive investing.


Build a positive relationship with money

Your mindset directly influences your financial decisions.


How to Start Adopting the New Money Mindset

If you want to apply this trend today, start with these simple steps:

  1. Track spending without judgment
  2. Set small, realistic saving goals
  3. Talk openly about money with trusted people
  4. Focus on financial habits that reduce stress
  5. Celebrate progress, not perfection

Final Thoughts

The biggest shift in personal finance isn’t a new investment strategy.

It’s a new way of thinking.

Money is no longer just about wealth — it’s about well-being, control, and peace of mind.

And as financial stress continues to rise globally, one thing is clear:

The future of money isn’t just financial.

It’s psychological.

Budgeting Around the World: Financial Practices from Different Cultures

Budgeting may be a universal concept, but how people manage money varies dramatically across cultures. From communal saving practices in Africa to cash-only systems in parts of Asia, financial habits are deeply influenced by tradition, values, and even religion. Understanding these global perspectives can inspire new ways to think about your own finances—and might even offer tips you haven’t considered before.


🌍 1. Japan: The Kakeibo Method – Mindful Budgeting

In Japan, budgeting is often centered around the Kakeibo (pronounced kah-keh-bo), a traditional journaling method that encourages people to reflect on their income and expenses weekly. Created in the early 1900s, this method asks four key questions:

  • How much money do you have?
  • How much would you like to save?
  • How much are you spending?
  • How can you improve?

đź’ˇ Whiz Tip: Try using a Kakeibo-style journal to make your budget more intentional and emotionally aware.


🇩🇪 2. Germany: The Value of Frugality and Precision

Germans are known for being disciplined with money. Many follow strict budgets and avoid debt unless absolutely necessary. Even credit card usage is lower compared to the U.S. or the UK.

💡 Whiz Tip: Embrace the "buy it for life" mindset—invest in high-quality, durable items instead of frequent, cheap purchases.


🇮🇳 3. India: Community and Cash-Based Living

In many Indian households, budgets are managed collectively. Elders often guide financial decisions, and cash is still a preferred method of transaction, especially in smaller towns. Savings are often prioritized over spending, and gold is a common form of wealth preservation.

đź’ˇ Whiz Tip: Consider how involving family in money talks might enhance transparency and shared goals in your home.


🇳🇬 4. Nigeria: Rotating Savings and Community Funds (Esusu)

In various African cultures, especially in Nigeria, Esusu or rotating savings and credit associations (ROSCAs) are common. A group of people contribute a fixed amount regularly, and one member takes the whole pot each time. It's a communal way to save and access larger sums.

💡 Whiz Tip: If you’re part of a trusted community, try forming a savings group or accountability circle.


🇸🇪 5. Sweden: Minimalism Meets Financial Health

In Sweden, the lagom philosophy—“not too little, not too much”—translates into financial habits. People budget with balance in mind, avoiding excess while still enjoying life. There’s also a strong social safety net, which influences how Swedes think about risk and savings.

💡 Whiz Tip: Apply the lagom approach by building a budget that’s sustainable and not overly restrictive.


🇧🇷 6. Brazil: Coping with Inflation and Financial Instability

With a history of economic instability and inflation, Brazilians often budget with a sense of urgency. Many people invest in real estate or U.S. dollars to hedge against currency fluctuation, and short-term planning is more common than long-term saving.

đź’ˇ Whiz Tip: If you're in an inflation-prone economy, consider diversifying where and how you save your money.


đź’¬ Final Thoughts: What Can We Learn?

Every culture has developed its own budgeting wisdom based on its unique challenges and values. Whether it’s Japan’s mindfulness, Nigeria’s community approach, or Germany’s structured discipline, there’s a lesson for all of us.

Ask yourself:
âś… What budgeting methods do I connect with most?
âś… Can I blend cultural practices to fit my lifestyle?
âś… How can I make budgeting feel more natural and fulfilling?

Scarcity vs. Abundance Mindset: How Your Beliefs Affect Your Finances

Ever wonder why some people seem to attract wealth like a magnet while others constantly feel like their money is slipping through their fingers? It’s not just about income, it’s about mindset. The way you think about money can significantly impact your financial reality. Enter: the Scarcity vs. Abundance Mindset debate.

What Is a Scarcity Mindset?

A scarcity mindset is like always believing the universe is one grocery store trip away from running out of toilet paper. It’s the belief that resources, like money, opportunities, and success, are limited. This leads to behaviors like hoarding, fear-based financial decisions, and an aversion to taking risks.

Signs of a scarcity mindset:

Constantly worrying about money, even when you have enough

Saying things like "I can’t afford that" (instead of "How can I afford that?")

Avoiding investments because you fear losing money

Feeling envious of others' financial success

Believing money is a zero-sum game (if someone wins, you must lose)

What Is an Abundance Mindset?

An abundance mindset is like believing there’s always another slice of pizza, no matter how many people are at the party. It’s the idea that wealth and success are limitless and that opportunities are always available for those willing to seek them.

Signs of an abundance mindset:

Viewing money as a tool, not a source of stress

Seeing opportunities where others see obstacles

Investing in yourself through education, networking, and skill-building

Celebrating others' financial wins rather than feeling jealous

Taking calculated risks, knowing that failure is just a learning experience

How Your Mindset Affects Your Finances

Your mindset influences your financial decisions, which in turn shape your financial future. Here’s how:

1. Saving & Spending Habits

Scarcity: You hoard money, afraid to spend even on essentials.

Abundance: You budget wisely, knowing money flows in and out.

2. Investing & Growing Wealth

Scarcity: You avoid investing due to fear of loss.

Abundance: You take smart financial risks, knowing growth comes from action.

3. Career & Income

Scarcity: You stay in a job you hate because you’re afraid of instability.

Abundance: You seek better opportunities, knowing your skills are valuable.

Shifting from Scarcity to Abundance

Good news! Your mindset isn’t set in stone. Here’s how you can cultivate an abundance mindset:

Practice Gratitude: Focus on what you have instead of what you lack.

Reframe Negative Thoughts: Instead of “I can’t afford it,” ask, “How can I afford it?”

Surround Yourself with Growth-Oriented People: Your environment shapes your mindset.

Educate Yourself on Finances: Knowledge is power, and power creates confidence.

Take Small Risks: Prove to yourself that smart financial decisions lead to growth.

Final Thoughts

Your beliefs about money shape your financial reality. A scarcity mindset keeps you stuck, while an abundance mindset opens the door to wealth and opportunity. The best part? You get to choose your mindset. So, next time you catch yourself worrying about money, ask yourself: Am I thinking in scarcity or abundance?

And remember, there’s always another slice of pizza.

From Paycheck to Paycheck to Financial Freedom: Changing Your Mindset

I know what it feels like to live paycheck to paycheck. There was a time when I’d get paid, cover my bills, buy a few things I thought I “needed,” and before I knew it, my bank balance was back to zero, waiting for the next payday. It felt like an endless cycle, and no matter how much I earned, I never seemed to get ahead.

The turning point for me? Realizing that financial freedom starts with mindset, not just money.

Step 1: Seeing Money Differently

For the longest time, I saw money as something that came and went. I worked for it, spent it, and waited for more. But once I started looking at money as a tool rather than something to chase, everything changed. Instead of spending first and saving what was left, I flipped the script: I paid myself first.

I started setting aside even a small percentage of my paycheck before touching a dime. At first, it was just $20 a week. But over time, that small habit built up and gave me confidence.

Step 2: Creating a Plan (Not Just a Budget)

I used to think budgeting was restrictive, just a way to remind me of what I couldn’t do. But when I actually took the time to track my expenses and create a budget that worked for me, I realized I was giving myself more control, not less.

Instead of wondering where my money went, I started telling it where to go.

A few key changes that helped me:

  • Cutting back on things I didn’t truly value (goodbye, random impulse buys).
  • Automating my savings so I didn’t have to think about it.
  • Setting mini-goals, like saving for a weekend trip or a new gadget.

Step 3: Shifting to a Growth Mentality

One of the hardest parts of breaking the paycheck-to-paycheck cycle was overcoming the belief that I would always struggle financially. But I had to remind myself: my financial situation wasn’t permanent.

I started focusing on ways to increase my income, whether it was taking on freelance work, learning new skills, or just negotiating a better salary. More importantly, I stopped comparing my progress to others and focused on what I could control.

Step 4: Building Long-Term Freedom

The biggest difference between where I was and where I am now? Consistency.

I didn’t get out of the paycheck-to-paycheck cycle overnight, and neither will you. But the small shifts in mindset and habits compound over time.

  • Track your spending - WhizBudget can help;
  • Save before you spend;
  • Invest in your future;
  • Believe that financial freedom is possible!

I’m not saying it’s always easy, but I can tell you firsthand, it’s absolutely worth it. Start today, even if it’s just a small step. Your future self will thank you.

How to Develop a Wealth Mindset: Shift Your Thinking for Financial Success

Your mindset plays a crucial role in financial success. A wealth mindset helps you spot opportunities, make smart financial choices, and build lasting wealth. By shifting the way you think about money, you can create a path toward financial freedom.

Many people believe wealth is only for a select few. Instead, start seeing it as attainable. Financial success comes from the right mindset and actions. Surround yourself with positive financial influences and learn from those who have built wealth.

A scarcity mindset makes you feel like there’s never enough money, leading to fear-based decisions. An abundance mindset helps you recognize that opportunities for earning and growing wealth are everywhere. Focus on possibilities rather than limitations and take proactive steps toward financial growth.

A wealth mindset thrives on continuous learning. Read books, take courses, and follow financial experts. The more you understand about money, investing, and financial management, the better decisions you’ll make for long-term success.

Define what financial success looks like for you. Whether it’s saving a certain amount, starting a business, or investing for the future, setting clear goals keeps you focused. Break down goals into smaller steps and track your progress.

Building wealth often requires stepping out of your comfort zone. Whether it’s investing, starting a side hustle, or negotiating a higher salary, taking calculated risks can lead to greater rewards. Make informed decisions and take action with confidence.

A wealth mindset isn’t just about earning more—it’s about managing money wisely. Create a budget, track expenses, and prioritize saving and investing. Make intentional spending choices that align with your goals.

The people around you influence your money mindset. Connect with financially responsible individuals who have a positive approach to wealth. Their habits and advice can keep you motivated and help you make smarter financial decisions.

Developing a wealth mindset takes time and effort, but it’s one of the most powerful shifts you can make for your financial future. By believing in financial abundance, continuing to learn, setting clear goals, and managing money wisely, you can create a path to long-term financial success.

How to Get Your Spouse on Board with Budgeting

Talking about money with your spouse can be challenging, especially if you have different financial habits. But getting on the same page about budgeting is essential for a healthy financial future. The good news is, that with the right approach, you can turn budgeting into a team effort instead of a source of conflict.

Start by having an open and judgment-free conversation about your financial goals. Instead of focusing on restrictions, frame the discussion around shared dreams, whether it's buying a house, travelling more, or securing a comfortable retirement. Highlight how a budget is simply a tool to achieve those goals together.

Understanding each other’s money mindset is key. People have different financial upbringings and attitudes toward spending and saving. Take the time to listen to your spouse’s perspective and acknowledge their concerns. A collaborative approach makes it easier to find common ground and compromise.

Make budgeting simple and stress-free. If your spouse is hesitant, ease into it by starting with a basic spending tracker or a shared budgeting tool like WhizBudget.

Avoid assigning blame or micromanaging spending. A successful budget isn’t about control, it’s about teamwork. Set spending limits together and agree on flexible categories so both partners feel heard. A little personal spending money for each of you can prevent feelings of restriction and frustration.

Turn budgeting into a habit with regular check-ins. Treat it like a monthly date where you review progress, celebrate small wins, and make adjustments as needed. Keeping the conversation positive and solution-focused will help both of you stay committed.

If your spouse is still resistant, lead by example. Show the benefits of budgeting through small changes and let them see how it reduces financial stress and builds security over time. Sometimes, actions speak louder than words.

Remember, budgeting is a journey, not a one-time conversation. Be patient, stay supportive, and work together to build a financial plan that fits your lifestyle and strengthens your relationship.

Looking for more financial tips? Check out our blog for practical money management strategies!