Budgeting Basics
Beginner-friendly guides on budgeting
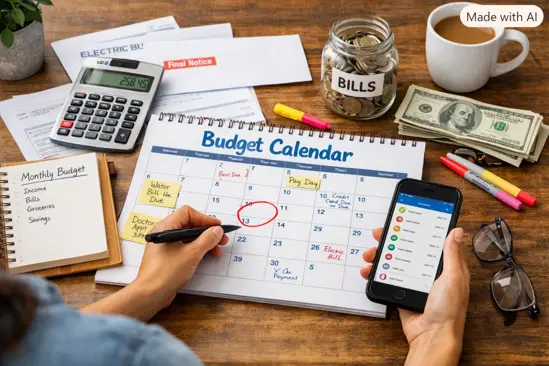
How to Make a Budget Calendar That Prevents Missed Bills
A budget calendar is one of the simplest ways to stop bills from taking you by surprise. It shows when money arrives, when money leaves, and whether your account balance can safely cover each payment. Unlike a full spending plan, it focuses on timing: the practical cash flow decisions that help you avoid late fees, failed direct debits and unnecessary overdraft use.
Whether you are paid weekly, monthly or on irregular dates, a clear bill payment calendar can make the month feel more predictable. Use the steps below to build one around your real paydays, account balances and billing dates.
What a Budget Calendar Is and Why It Matters
A budget calendar is a calendar that records your paydays, bill due dates, planned transfers and expected spending. It can be a paper wall calendar, a spreadsheet, a phone calendar or a free budget app. The key is that it lets you see the order of events, not just a list of monthly totals.
For example, you may have enough income to pay rent, utilities and insurance over a month. But if rent leaves your account on the 1st and you are paid on the 5th, you still have a cash flow problem unless you keep money aside from the previous payday. A monthly budget calendar makes these timing gaps visible before they become a missed payment.
It is important to use a budget calendar alongside your normal budget, not instead of one. Your budget decides how much you can afford to spend on each category. Your calendar helps you make sure the money is in the right account on the right day.
Gather Your Bills, Paydays and Account Balances
Start with accurate information. Open your bank app, check recent statements and review emails from providers. Do not rely only on memory, especially for quarterly, annual or variable payments.
- Every source of income and its expected payday
- Rent or mortgage payment date
- Utilities, broadband, mobile and streaming subscriptions
- Insurance premiums, loan repayments and credit card minimum payments
- Council tax or local property charges where applicable
- Childcare, school costs, transport passes and membership fees
- Direct debits, standing orders and card subscriptions
- Your current balance in each bank account and savings pot
For each bill, write down the amount, due date, payment method and account it is taken from. If the amount changes, note the usual range and the highest recent amount. This is particularly useful for energy bills, mobile usage, credit cards and water charges.
Also record money already committed. A balance of €900 or £900 does not mean all of it is available if a rent payment and several direct debits are due before your next payday.
Choose a Calendar Format That You Will Actually Use
The best format is the one you will check consistently. A paper calendar can work well if everyone in the household needs to see it. A spreadsheet is useful for calculating running balances. A digital calendar can send reminders. A budget app can keep transactions, categories and upcoming bills in one place.
WhizBudget is a free budget app that can help you track planned bills and review your wider spending alongside your calendar. Whatever tool you choose, keep the layout simple enough to update in a few minutes each week.
| Format | Best for | Watch out for |
|---|---|---|
| Paper calendar | Quick visual overview and shared households | Needs manual updates and no automatic reminders |
| Spreadsheet | Running balances and flexible planning | Can become overly complicated |
| Phone calendar | Alerts for due dates and portability | May not show account balances clearly |
| Budget app | Connecting bills with spending records | Still requires regular review |
Add Fixed Bills and Their Due Dates
Enter fixed bills first because they are the least flexible commitments. Use the actual collection date rather than the statement date. Mark direct debits clearly, as a failed direct debit can result in charges from both your bank and provider.
Use a consistent label, such as “Rent – £950 DD” or “Internet – €35 card”. If a bill is taken automatically, add “auto” to the entry. If you need to pay it yourself, create a reminder two or three working days before the deadline.
Remember that weekends and bank holidays can affect timing. Some payments leave on the next working day, while others may be requested earlier by the provider. Check how each biller handles non-working days. For important payments, plan as if the money needs to be available one business day early.
Match Bill Payments to Your Paychecks
This is the step that turns a list of bills into a useful cash flow calendar. Look at each payday and assign the bills it needs to cover until the next payday. Your aim is not necessarily to pay every bill immediately; it is to reserve the money so it cannot be spent accidentally.
Here is a simple example for someone paid on the 25th of each month.
| Date | Calendar entry | Amount | Running balance example |
|---|---|---|---|
| 25 April | Salary received | +€2,100 | €2,250 |
| 28 April | Rent direct debit | -€900 | €1,350 |
| 1 May | Insurance direct debit | -€65 | €1,285 |
| 3 May | Phone and broadband | -€70 | €1,215 |
| 10 May | Transfer to groceries pot | -€320 | €895 |
| 24 May | Hold remaining money for next rent | -€900 reserved | €-5 available without extra income |
The example reveals a problem: even though income may cover monthly costs overall, the next rent is not fully funded before the next payday. The solution might be building a small rent buffer, changing the rent payment date if the landlord allows it, splitting savings across paydays or reducing other planned spending. Seeing this early gives you options.
If you are paid fortnightly or weekly, assign a portion of monthly bills to each payday. For example, set aside half of a €120 monthly energy bill from each fortnightly pay. Keep reserved money in a separate savings pot or a dedicated bills account where possible.
Plan for Variable Bills and Automatic Payments
Variable bills need more care because the exact amount is not known. Add an estimate based on the highest normal bill, rather than the average, until you have built a comfortable buffer. For energy, consider seasonal changes: winter use may be significantly higher than summer use.
For automatic payments, your calendar should show both the expected date and the safe amount to hold. A card subscription may renew after a free trial, and a credit card direct debit can rise when you spend more. Review these entries before they leave your account.
- Use the upper end of a recent bill range for variable direct debits.
- Add renewal dates for annual insurance, software and memberships.
- Put a reminder seven days before any payment that can change.
- Check that the payment account has enough cleared funds, not just pending income.
- Cancel unused subscriptions before their renewal date, not after it.
Leave a Buffer for Timing Gaps and Unexpected Charges
A buffer is money that remains in your account after planned payments. It protects you when a transaction is processed early, a utility bill is higher than expected or a bank transfer takes longer than usual. Even a small buffer can prevent a missed bill.
A practical first target is enough to cover one essential direct debit, such as your phone bill or insurance. Over time, build towards a full month of core bills held separately. This is different from an emergency fund, although both improve financial resilience.
Be especially cautious when moving money between accounts. Transfers may not be instant across all banks or countries, and weekends can delay processing. Schedule transfers early, then confirm they have arrived before a direct debit is due. Avoid planning your balance down to the last euro or pound.
Create a Weekly Budget Calendar Review
Your calendar only works if it stays current. Set a repeating 10-minute appointment once a week, ideally on the same day. Check the next 7 to 14 days, rather than waiting until a bill has already failed.
- Compare your calendar with your actual bank balances.
- Confirm upcoming direct debits, card payments and transfers.
- Mark income that has arrived and bills that have cleared.
- Update any variable bill estimates or changed due dates.
- Move money into your bills account or savings pots if needed.
- Check whether discretionary spending needs to slow down before payday.
A weekly review also helps couples and families coordinate shared costs. If one person pays a household bill, record it clearly so the other person knows when to transfer their contribution.
Common Budget Calendar Mistakes to Avoid
- Listing due dates but not paydays. A calendar without income dates cannot show whether cash will be available.
- Using statement dates instead of collection dates. Always plan for when money actually leaves your account.
- Forgetting annual and quarterly costs. Add insurance renewals, vehicle taxes, school costs and memberships as soon as you know the dates.
- Ignoring pending transactions. Your displayed balance may include money that is already committed.
- Assuming autopay means no work. Automatic payments still need enough funds and periodic checks.
- Creating no buffer. A calendar is more reliable when small timing changes do not cause a crisis.
- Never updating the plan. Pay rises, new subscriptions and changed direct debit dates all need to be reflected.
Frequently Asked Questions
What is the difference between a budget calendar and a regular budget?
A regular budget sets spending limits and savings goals. A budget calendar maps when income and payments happen, helping you manage cash flow and avoid missed bills.
Should I pay bills as soon as I get paid?
Paying early can work if it helps you avoid spending the money elsewhere. However, you can also reserve the money in a separate bills account or savings pot and pay on the due date. Always ensure direct debits are funded before collection.
How do I make a bill payment calendar if I am paid weekly?
Add every weekly payday, then divide monthly and quarterly bills into weekly amounts. Transfer each portion to a bills pot so the full payment is ready by its due date.
How much buffer should I keep in my bills account?
Start with enough to cover one essential bill or your largest likely variation. Build gradually towards a larger buffer, ideally up to one month of essential bills if that is realistic for your circumstances.
What if a bill is due on a weekend or bank holiday?
Check your provider’s rules, but keep the money available at least one working day before the due date. Some payments are collected on the next business day, while others can be processed earlier.
Can I use one calendar for personal and household bills?
Yes. Use labels or colours to show who pays, which account is used and whether another household member needs to contribute. Keep personal spending private where necessary.
Conclusion: Put Your Bill Dates in One Clear View
A budget calendar gives every payday and bill due date a place in your plan. Start with fixed payments, match them to income, allow for variable costs and protect yourself with a buffer. Then review the next two weeks every week. This straightforward habit can reduce financial stress and make missed bills far less likely.
Ready to make your cash flow easier to manage? Use WhizBudget, the free budget app, to organise upcoming bills, track spending and stay ahead of your next payday.
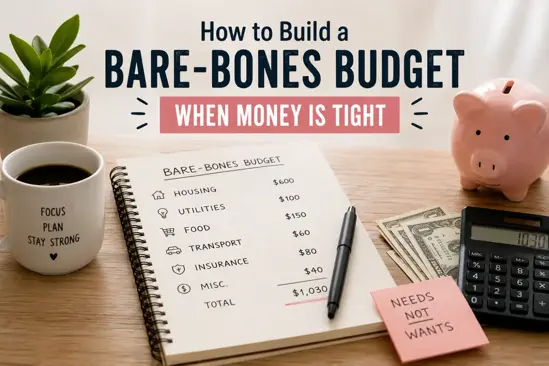
How to Build a Bare-Bones Budget When Money Is Tight
When your income drops, your hours are reduced, you lose a job, or a large bill arrives unexpectedly, your normal budget may stop working overnight. A bare bones budget helps you focus on one goal: keeping your household stable until things improve.
This is not about perfection, guilt, or cutting every small comfort forever. It is a short-term emergency budget plan that protects your essentials first: housing, utilities, food, transport, and minimum debt payments. Once your income stabilises, you can rebuild your usual spending plan.
In this guide, you will learn how to create a practical bare bones budget, what to cut first, which bills to prioritise, and what to do within the next 24 hours if money is tight.
What Is a Bare-Bones Budget?
A bare bones budget is a stripped-down version of your normal monthly budget. It includes only the expenses you genuinely need to keep a roof over your head, maintain basic services, eat, get to work or appointments, and avoid serious financial consequences.
Unlike a normal budget, it does not aim to balance comfort, lifestyle, savings, and long-term goals. Instead, it focuses on short-term survival and stability. It is sometimes called an essential expenses budget because every line should be necessary.
A bare bones budget usually includes:
- Rent or mortgage payments
- Basic utilities such as electricity, gas, water, and heating
- Essential groceries and household items
- Transport needed for work, school, medical appointments, or caring responsibilities
- Minimum debt payments to prevent arrears or penalties
- Insurance that protects your home, car, health, or income where relevant
- Basic phone and internet if needed for work, job searching, banking, or essential communication
It usually excludes non-essential spending such as subscriptions, takeaways, clothing that is not urgent, entertainment, holidays, upgrades, and impulse purchases.
When You Should Use a Bare-Bones Budget
A bare bones budget is most useful when your financial situation changes quickly and you need to make decisions before missed payments pile up. It can help during both short-term and uncertain situations.
You may need a bare bones budget if:
- You have lost your job or expect redundancy
- Your working hours have been reduced
- You are self-employed and income has slowed down
- You are waiting for benefits, unemployment support, or insurance payments
- You have an unexpected medical, dental, car, or home repair bill
- Your rent, mortgage, energy, or food costs have increased sharply
- You are relying on savings and need them to last longer
- You are behind on bills and need a clear recovery plan
This type of budget is not meant to be permanent. Living on the minimum for too long can be stressful and unrealistic. The aim is to buy time, reduce damage, and give you a clear plan while you look for extra income, support, or a more stable routine.
Step 1: Calculate Your Reliable Monthly Income
Start with the money you can realistically count on this month. Do not build your budget around income that might arrive, such as overtime, a possible freelance invoice, or a job offer that is not confirmed.
List only reliable income, such as:
- Net salary or wages after tax and deductions
- Confirmed unemployment benefits or social support
- Child benefit, maintenance, or family support you reliably receive
- Pension payments
- Regular self-employment income from confirmed work
- Any cash savings you have decided to use this month
If your income is irregular, use the lowest realistic amount you expect. For example, if your monthly income is usually between €1,200 and €1,700 but work is uncertain, build your low income budgeting plan around €1,200 or less. If more money arrives, you can use it to catch up on bills, rebuild a small emergency fund, or cover next month.
Write down the date each income payment is expected. Timing matters. A budget may look balanced for the month but still fail if rent is due before wages arrive. If cash flow is tight, you may need to contact a landlord, lender, or provider to request a different due date.
Step 2: Separate Essential Expenses From Non-Essentials
The hardest part of a budget when money is tight is deciding what stays and what goes. Use a simple rule: if not paying for it could threaten your housing, health, ability to earn income, legal obligations, or basic family needs, it is likely essential. If it can be paused without serious consequences, it is non-essential for now.
| Essential expenses | Non-essential expenses to pause or reduce |
|---|---|
| Rent or mortgage | Streaming subscriptions |
| Electricity, gas, water, heating | Takeaways and restaurant meals |
| Basic groceries | Alcohol, tobacco, and convenience snacks |
| Transport to work, school, or medical care | Clothing that is not urgent |
| Minimum debt repayments | Hobbies, events, and paid entertainment |
| Essential insurance | Gym memberships |
| Phone and internet needed for work or essential admin | App subscriptions and premium software |
| Childcare needed to work | Beauty treatments and non-urgent appointments |
Some categories depend on your circumstances. A car may be essential if you live in a rural area or need it for work. It may be less essential if reliable public transport is available. Internet may be essential if you work remotely, search for jobs, manage online banking, or complete benefit applications.
Be honest, but do not be harsh with yourself. The goal is not to judge past spending. The goal is to make the next month safer.
Step 3: Prioritize Housing, Utilities, Food, Transportation, and Minimum Debt Payments
Once you know your income and essential costs, rank bills by consequence. Not all bills have the same urgency. Missing a subscription payment is inconvenient. Missing rent or mortgage payments can put your home at risk.
Use this priority order when building your bare bones budget:
- Housing: rent, mortgage, service charges, and essential home insurance.
- Utilities: electricity, gas, heating, water, and basic waste charges where applicable.
- Food and household basics: simple groceries, hygiene items, baby supplies, and essential medicines.
- Transport: fuel, public transport pass, bike repairs, car insurance, or vehicle costs needed to work and meet essential obligations.
- Minimum debt payments: credit cards, loans, overdrafts, tax debts, or arrears where missed payments could create fees or collection action.
- Essential communication: the cheapest practical phone and internet option.
If your income does not cover all essentials, do not ignore the problem. This is the point where you contact providers before the due date, check eligibility for support, and look for temporary payment arrangements. Many European lenders, utility companies, landlords, and public bodies have hardship teams or repayment options, but it is usually easier to arrange help before you miss payments.
Step 4: Cut or Pause Non-Essential Spending Immediately
When money is tight, speed matters. Waiting until the end of the month can mean the money has already gone through automatic payments, card charges, and small purchases. Within the next 24 hours, cancel, pause, or downgrade anything that is not essential.
Start with quick wins:
- Cancel streaming, music, gaming, magazine, and app subscriptions.
- Pause gym memberships if your contract allows it.
- Stop takeaway food and switch to simple home meals.
- Delay clothing, electronics, homeware, and furniture purchases.
- Remove saved cards from shopping apps to reduce impulse buys.
- Turn off auto-renewals for annual subscriptions.
- Downgrade mobile or broadband packages if you are out of contract.
- Put a temporary spending limit on your debit or credit card if your bank allows it.
Check your bank account for direct debits, standing orders, and recurring card payments. In many European countries, direct debit payments can be easy to forget because they leave automatically. Make a list of every recurring payment and decide whether it is essential, negotiable, or cancellable.
Be careful when cancelling insurance or contracts with penalties. Some policies are essential, and some contracts charge fees for early cancellation. If in doubt, contact the provider and ask about a temporary reduction, payment holiday, or cheaper plan before cancelling.
Step 5: Contact Lenders, Utility Providers, and Service Companies Before You Miss Payments
If your bare bones budget shows you cannot pay everything, communication is urgent. It may feel uncomfortable, but early contact can reduce fees, protect your credit file, and give you more options.
Contact these providers first:
- Your landlord, mortgage lender, or housing office
- Energy, heating, and water providers
- Credit card companies, loan providers, and overdraft providers
- Local tax, council, municipality, or social insurance offices if relevant
- Phone, internet, and insurance companies
When you contact them, keep the message simple and factual. Explain that your income has temporarily dropped, you are reviewing your essential expenses budget, and you want to avoid missed payments. Ask what hardship options are available.
You can say:
I am experiencing a temporary drop in income and I am creating an emergency budget plan. I want to stay on top of my account, but I may not be able to make the full payment this month. Are there any payment plans, reduced payments, due date changes, or hardship options available?
Before agreeing to anything, ask:
- Will this affect my credit record?
- Will interest or late fees be added?
- How long will the arrangement last?
- Can I return to normal payments without a penalty?
- Will I receive the agreement in writing?
Keep records of every call, email, and agreement. Note the date, name of the person you spoke to, and what was agreed. If possible, request confirmation by email or letter.
Step 6: Build a Simple Bare-Bones Budget Example
Here is a realistic example for one person living in Europe after a temporary income drop. The exact numbers will differ depending on your country, city, household size, and housing costs, but the structure is what matters.
| Category | Monthly amount | Notes |
|---|---|---|
| Reliable income | €1,450 | Reduced wages after tax |
| Rent | €650 | Priority housing cost |
| Utilities | €180 | Electricity, gas, water, heating |
| Groceries and household basics | €250 | Simple meal plan and essential items |
| Transport | €95 | Monthly public transport pass |
| Phone and internet | €45 | Basic plan needed for work and admin |
| Insurance | €40 | Essential cover only |
| Minimum debt payments | €120 | Credit card and personal loan minimums |
| Medicines and health costs | €35 | Regular prescriptions and appointments |
| Emergency buffer | €35 | Small cushion for unexpected basics |
| Total essential spending | €1,450 | Every euro assigned |
In this example, there is no room for non-essential spending. That is uncomfortable, but it gives the person a clear plan. If they spent €60 on takeaways or subscriptions, they would likely fall behind on food, transport, or debt payments.
If your total essential spending is higher than your income, you need a shortfall plan. For example:
| Shortfall action | Possible impact |
|---|---|
| Request a utility payment plan | Spreads a large bill over several months |
| Ask lender for temporary reduced payment | May protect cash flow, but check credit impact |
| Use a small amount of emergency savings | Buys time without borrowing |
| Apply for local support or benefits | May help with rent, energy, food, or family costs |
| Sell unused items | Can cover a one-off gap, but is not a long-term income plan |
A budgeting tool such as WhizBudget can help you lay out these categories clearly, adjust numbers quickly, and see which payments are due before your next income arrives.
Step 7: Track Spending Weekly Until Your Income Stabilizes
A bare bones budget needs regular checking because there is very little margin for error. When your budget is tight, one forgotten bill or grocery overspend can cause problems.
Review your spending at least once a week. If your situation is urgent, check it every two or three days. This does not need to be complicated. You can use a notebook, spreadsheet, banking app, or WhizBudget to track what has actually left your account.
During each weekly check-in:
- Compare planned spending with actual spending.
- Check which bills are due before your next income payment.
- Move money for rent, utilities, and food before spending on anything else.
- Update your grocery and transport totals.
- Confirm that cancelled subscriptions have actually stopped.
- Review any payment arrangements you have made.
Use cash envelopes or separate bank spaces if they help you avoid accidental spending. For example, you might keep grocery money separate from bill money. If your bank offers instant notifications, turn them on so you see every transaction.
Weekly tracking also helps you spot progress. Even if the month is difficult, staying current on the most important bills is a win.
Actionable Steps You Can Take Within 24 Hours
If you feel overwhelmed, focus on the next day rather than the whole month. These actions can make your budget safer quickly:
- Check your current bank balance and list all income expected this month.
- Write down the due dates and amounts for rent, utilities, food, transport, and debt payments.
- Cancel or pause at least three non-essential recurring payments.
- Plan the next seven days of meals using food you already have first.
- Contact one provider today if you know a payment will be late or unaffordable.
- Remove shopping apps or saved card details from your phone.
- Set a weekly spending limit for groceries and transport.
- Check whether you qualify for local support, energy help, housing assistance, unemployment benefits, or food aid.
You do not need to solve everything immediately. You need to stop the financial leak, protect essentials, and create breathing space.
Common Mistakes to Avoid With a Bare-Bones Budget
A bare bones budget is simple, but a few common mistakes can make it less effective.
Ignoring payment dates
A monthly total is not enough. If rent is due on the 1st and income arrives on the 15th, you have a cash flow problem even if the budget balances on paper. Track due dates carefully.
Cutting essentials by accident
Do not cancel important insurance, medication, childcare, or transport without understanding the consequences. Some costs are essential because they prevent bigger problems.
Paying loud creditors before priority bills
Some companies chase payments aggressively, but that does not always mean they should be paid first. Housing, energy, food, and essential transport usually come before unsecured debts.
Relying on credit cards to fill the gap
Credit can help in a rare emergency, but using it every month to cover basics can quickly turn a temporary income drop into long-term debt. Contact providers and seek support before borrowing more.
Making the budget too strict to follow
If possible, include a tiny emergency buffer, even €20 or €30. Life rarely follows a perfect plan. A small cushion can prevent one small problem from becoming a missed bill.
Not asking for help early enough
Support may be available through government schemes, municipalities, charities, food banks, energy assistance programmes, or debt advice services. Asking early gives you more options.
How to Move Back to a Normal Budget
A bare bones budget should last only as long as necessary. Once your income improves, your hours increase, you start a new job, or the emergency bill is dealt with, you can gradually move back to a normal budget.
Do not rush straight back to old spending patterns. First, repair the damage and create stability.
Use this order:
- Catch up on priority arrears: rent, mortgage, utilities, and tax or local authority debts.
- Rebuild a small emergency fund: aim first for €250 to €500, then build from there.
- Clear expensive short-term debt: overdrafts, payday-style loans, and high-interest credit cards.
- Restart important sinking funds: annual insurance, car maintenance, school costs, health costs, or home repairs.
- Add back non-essentials slowly: choose the subscriptions, hobbies, or treats that genuinely matter.
- Review your normal budget: update it based on your real cost of living, not your old assumptions.
This is also a good time to ask what the emergency taught you. Did you need a larger emergency fund? Were too many subscriptions running unnoticed? Was your rent or car payment too high for your income? Use that information without blaming yourself.
WhizBudget can be useful here because you can create a bare bones version of your budget first, then gradually add categories back when your finances recover.
FAQs
What is the difference between a bare bones budget and a normal budget?
A normal budget covers essentials, savings, debt repayment, and lifestyle spending. A bare bones budget removes almost everything except essential expenses. It is designed for short-term financial pressure, such as job loss, reduced hours, or emergency bills.
How long should I use a bare bones budget?
Use it for as long as your income is unstable or your essential bills are at risk. For many people, this may be one to three months. If you need it for longer, consider getting debt advice or local financial support because the pressure may not be temporary.
Should I stop saving while using a bare bones budget?
If your income does not cover essentials, it is usually reasonable to pause long-term savings temporarily. However, if you can keep even a small emergency buffer, it may help you avoid borrowing for minor unexpected costs.
Which bills should I pay first when I cannot pay everything?
Prioritise housing, utilities, food, essential transport, and legal or priority debts. Then deal with unsecured debts such as credit cards and personal loans. Always contact lenders and providers before missing payments where possible.
Is a bare bones budget useful for low income budgeting?
Yes, especially during periods when income is very limited. However, if your income is consistently below your essential costs, budgeting alone may not be enough. You may need benefit checks, debt advice, housing support, or help from local services.
Can I still have any personal spending?
If your essentials are covered and you have a small amount left, you can include a modest personal allowance. If there is no money left, pause personal spending temporarily and focus on free options until your income improves.
What should I do if my bare bones budget still does not balance?
Contact providers immediately, ask about hardship options, check eligibility for local or national support, and consider speaking to a free debt advice organisation. Do not wait until several payments have already been missed.
Conclusion
A bare bones budget is not a punishment. It is a practical tool for protecting your home, food, utilities, transport, and financial stability when money is tight. By focusing on reliable income, separating essentials from non-essentials, cutting unnecessary spending quickly, and contacting providers early, you can reduce stress and make better decisions during a difficult period.
Start with the next 24 hours: list your income, protect your priority bills, cancel non-essentials, and make one important phone call if a payment is at risk. Small actions taken early can prevent bigger problems later.
If you want a clearer way to organise your emergency budget plan, use WhizBudget to map your essential expenses, track weekly spending, and move back to a normal budget when your income stabilises.
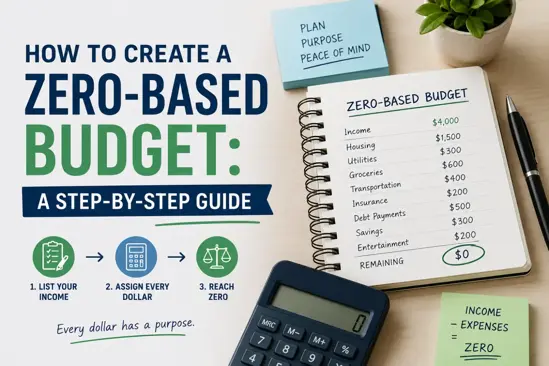
How to Create a Zero-Based Budget: A Step-by-Step Guide
A zero-based budget is a budgeting method where every dollar of your income is allocated to specific expenses, savings, or debt repayment, leaving you with zero unallocated funds. This approach encourages conscious spending and ensures that every dollar you earn is put to work in your personal finance strategy.
Benefits of a Zero-Based Budget
Implementing a zero-based budget offers several advantages:
- Increased Awareness: You gain a clear understanding of your financial situation.
- Improved Control: You control where your money goes, reducing unnecessary expenses.
- Financial Goals: It helps prioritize saving for financial goals and emergencies.
- Adaptability: Your budget can be adjusted to reflect changes in income or expenses.
Step 1: List Your Income
The first step in creating a zero-based budget is to list all your sources of income. This includes your salary, side hustles, and any other earnings. Make sure to calculate your total monthly income.
Step 2: Identify Your Expenses
Next, you need to identify all your monthly expenses. This can be divided into fixed and variable expenses:
- Fixed Expenses: Rent, mortgage, insurance, etc.
- Variable Expenses: Groceries, entertainment, dining out, etc.
Step 3: Allocate Every Dollar
Once you have your income and expenses listed, allocate every dollar from your income to your expenses, savings, or debt repayment. This is the essence of a zero-based budget. Your income minus your expenses should equal zero.
Step 4: Review and Adjust Monthly
Budgeting is not a one-time task. Review your zero-based budget at the end of each month. Adjust your allocations as necessary to reflect changes in income or expenses.
Common Mistakes to Avoid
When creating a zero-based budget, be mindful of common pitfalls:
- Underestimating Expenses: Always overestimate your variable expenses to avoid surprises.
- Not Adjusting Regularly: Make it a habit to adjust your budget every month.
- Ignoring Irregular Expenses: Don’t forget to account for annual or semi-annual expenses.
FAQs
What is a zero-based budget?
A zero-based budget is a method where every dollar of your income is assigned to expenses or savings, leading to a balance of zero.
How do I start a zero-based budget?
Start by listing your income, identifying your expenses, and allocating every dollar until your income minus expenses equals zero.
Can I use budgeting tools?
Yes, tools like WhizBudget can simplify the process and help you track your budget effectively.
How often should I review my budget?
Review your budget monthly to make necessary adjustments based on your financial situation.
What if my expenses exceed my income?
If your expenses exceed your income, consider cutting non-essential expenses or finding ways to increase your income.
Is zero-based budgeting suitable for everyone?
While it can be beneficial, it may not be suitable for everyone. Assess your personal finance strategy and comfort with detailed budgeting.
Conclusion
Creating a zero-based budget can significantly improve your financial management and help you achieve your financial goals. By following these steps, you can take control of your finances and ensure every dollar is working for you. For those looking for a helpful budgeting tool, consider using WhizBudget to make the process easier and more efficient.

Budgeting for Different Life Stages: Tailoring Your Finances Without Losing Your Mind
Budgeting looks very different when you're living on instant noodles in college versus juggling daycare, a mortgage, and a dog that eats $60 worth of chew toys a month. Life changes and your budget should change with it.
Let’s walk through how to tailor your budget for each stage of life, like we’re chatting over coffee (or reheated tea if you’re in full-on parent mode).
🎓 Budgeting in Your College Years: Survive First, Save Later
Ah, college. Where you’re broke, but creatively so. Budgeting here is about avoiding ramen burnout and managing what little you have.
Quick wins:
- Track everything. Every burrito, every beer. Use a budgeting app (like YNAB or Mint) so you know where it all goes.
- Prioritise essentials. Rent, books, and maybe that one streaming service you actually use.
- Start small with savings. Even $10 a week adds up. Think of it as your “Oh crap, I forgot this bill” fund.
- Say yes to student discounts. Your student ID is basically a coupon book.
Budgeting for different life stages starts here, with learning what NOT to do (like putting a pizza on a credit card).
🏃♀️ Budgeting in Your 20s and 30s: The “Am I Doing This Right?” Era
You're adulting now. Ish. These years are full of transitions - first jobs, moving out, possibly moving back in, and figuring out how taxes work.
Your financial strategy now should include:
- Building an emergency fund (3–6 months of expenses is the gold standard, but hey, even one month is a great start).
- Tackling student loans. Don’t ignore them. Check if income-based repayment is a better fit.
- Setting financial goals. Want to travel? Buy a car? Save for a wedding? Budget with those in mind.
- Automate your savings. Out of sight, out of spend-temptation.
Example: My friend Julia set up an auto-transfer of $50/week into a “Future Me” fund. Three years later, she used it as a down payment on a car. Past Julia was a genius.
🍼 Budgeting in Your 30s and 40s: The “Juggling Everything” Phase
This stage is where budgeting gets complicated. You might be raising kids, paying off a mortgage, managing childcare, saving for retirement... and trying to remember what sleep felt like.
Make your budget work harder with:
- Line-iteming your priorities. Childcare, groceries, health insurance—no fluff here.
- Planning for irregular expenses. Think holidays, school supplies, and replacing that dishwasher that’s on its last wheeze.
- Investing regularly. Even if it’s small, compound interest is your friend.
- Reviewing your budget monthly. Kids grow. So do expenses. Adapt accordingly.
Pro tip: Use a “sinking fund” system. Have mini-accounts for future big costs (like Christmas or home repairs) so they don’t wreck your month. WhizBudget can help with getting those sorted.
🧓 Budgeting in Your 50s and Beyond: The “Let’s Future-Proof This” Chapter
Retirement’s no longer a vague concept—it’s a real, looming calendar item. Your budget now should prioritise stability and peace of mind.
Smart moves:
- Max out retirement accounts. If you’re behind, catch-up contributions exist for a reason.
- Pay off remaining debts. Mortgage, car loans, credit cards—clear them if possible.
- Adjust lifestyle spending. Maybe cut back on some wants to stretch those dollars longer.
- Review insurance and health costs. These can spike as you age—plan now to avoid surprises.
Anecdote: My uncle switched from expensive restaurant meals to a home cooking club with friends. Healthier, cheaper, and honestly more fun.
☕ Final Sip: Your Budget Should Age As Gracefully As You Do
Budgeting for different life stages isn’t about following the same rules forever, it’s about staying nimble, intentional, and kind to yourself. You’ll spend differently in your 20s than in your 60s, and that’s exactly how it should be.
The secret? Keep it simple, stay consistent, and check in with your budget regularly, like a good friend who tells you when your spending’s getting a little wild.
👇 TL;DR: Life Stage Budgeting Tips
- College: Track every dollar. Learn the ropes.
- 20s/30s: Build goals, save automatically, slay debt.
- 30s/40s: Prioritise essentials, plan for unpredictability.
- 50s+: Future-proof your finances, review everything.

Track Your Progress and Adjust Your Budget for Success
Creating a budget is just the first step, sticking to it and making adjustments along the way is what really leads to success. Life changes, unexpected expenses come up, and financial goals shift over time. That’s why tracking your progress and tweaking your budget regularly is essential.
Why Tracking Your Finances Matters
When you track your spending and saving, you can see what’s working and what’s not. It helps you:
- Stay accountable and motivated
- Catch bad spending habits before they get out of hand
- Ensure you're making steady progress toward your financial goals
- Adjust quickly when unexpected expenses pop up
Think of your budget like a fitness plan. You wouldn’t work out once and expect to be in great shape, you have to check in, measure progress, and adjust your approach over time.
How to Track Your Financial Progress
There’s no one-size-fits-all method, so choose what works best for you:
- Use a Budgeting App – Apps like WhizBudget make tracking your expenses effortless by automatically categorizing transactions.
- Review Your Bank Statements – A quick monthly review helps spot trends and unnecessary spending.
- Set Monthly Check-Ins – Schedule time to review your finances, just like you would a doctor’s appointment.
- Track Savings Goals – Whether you're building an emergency fund or saving for a vacation, seeing progress can keep you motivated.
Make adjustments without stress! If you notice you're overspending in one category or struggling to save, don’t panic, budgets are meant to be flexible. Here’s how to make smart adjustments:
- Reallocate funds – If you’re overspending on dining out but underspending on entertainment, shift money between categories instead of abandoning your budget.
- Find easy cuts – Small changes, like brewing coffee at home or cancelling unused subscriptions, can free up extra cash.
- Increase savings gradually – If saving 20% of your income feels impossible, start with 5% and increase it over time.
And remember that consistency is the key. The most successful budgets aren’t perfect; they’re adaptable. Checking on your progress regularly and making small tweaks will keep you on track. Over time, these adjustments become habits that strengthen your financial stability.
No matter where you are in your financial journey, tracking your progress ensures you're moving in the right direction. Need help staying on top of your budget? WhizBudget makes tracking and adjusting your finances simple and stress-free

How to Adjust Your Spending Habits and Save More Money
Taking control of your finances isn’t just about earning more—it’s also about managing how you spend. Small changes in your spending habits can lead to big improvements in your financial health, helping you save more and reach your goals faster.
Identify Where Your Money Is Going
Before making changes, it’s important to understand your current spending patterns. Review your bank statements or use a budgeting app to see where your money goes each month. Are there areas where you’re overspending, like dining out, subscriptions, or impulse buys?
Cut Back Without Feeling Deprived
Adjusting your spending doesn’t mean giving up everything you enjoy. Instead, find smarter ways to manage your expenses:
- Cancel unused subscriptions – If you’re not using a service regularly, cut it.
- Limit impulse purchases – Wait 24 hours before buying non-essential items.
- Eat out less – Cooking at home can save you hundreds each month.
- Shop smarter – Use cashback apps, compare prices, and buy in bulk for essentials.
Prioritize What Matters
Not all spending is bas, it's about making intentional choices. Focus on spending in ways that align with your values and goals. If travel or experiences matter more to you than fancy gadgets, redirect your money accordingly.
Make Saving Automatic
One of the easiest ways to adjust spending habits is to automate savings. Set up a direct deposit to move a portion of your income into savings before you even see it. When saving becomes a priority, adjusting your expenses naturally follows.
Stay Accountable
Keeping track of your progress can help you stay motivated. Set small goals, celebrate wins, and regularly review your spending to ensure you’re staying on track. Over time, these new habits will become second nature.
Small changes can lead to big financial improvements. By making mindful adjustments to your spending, you’ll have more control over your money and be in a better position to achieve your financial goals. WhizBudget makes it easy to track your spending and savings in one place, start today!

How to Set Realistic Financial Goals and Actually Achieve Them
Setting financial goals is the first step toward achieving financial stability and success. Whether you want to build an emergency fund, pay off debt, or save for a big purchase, having a clear and realistic plan will keep you motivated and on track.
Why Realistic Goals Matter
It’s easy to dream big, but unrealistic goals can lead to frustration and burnout. Instead of setting vague or overly ambitious targets, focus on goals that are specific, measurable, and achievable within a reasonable timeframe. This makes it easier to track progress and stay committed.
How to Set Financial Goals That Work
Start by identifying what matters most to you. Do you want to get out of debt, save for a home, or build long-term wealth? Once you have a focus, break your goals into short-term, medium-term, and long-term targets.
- Short-term goals (3–12 months): Build an emergency fund, pay off a small debt, or create a monthly budget.
- Medium-term goals (1–5 years): Save for a down payment, pay off student loans, or increase retirement contributions.
- Long-term goals (5+ years): Buy a home, achieve financial independence, or retire comfortably.
Making Your Goals Achievable
Once you've set your goals, create a plan to reach them:
- Be specific – Instead of saying, “I want to save money,” set a goal like, “I will save $5,000 for an emergency fund in 12 months.”
- Break it down – Divide your goal into smaller, manageable steps, such as saving $100 per week.
- Track progress – Use budgeting apps or spreadsheets to monitor how close you are to reaching your goal.
- Stay flexible – Life happens. Adjust your timeline if needed, but don’t lose sight of your goal.
Staying Motivated
Achieving financial goals takes time, so keep yourself motivated with small rewards and regular check-ins. Celebrate progress along the way—every extra dollar saved or debt paid off brings you closer to financial freedom.
Setting realistic financial goals gives you a clear path to success. Start small, stay consistent, and make adjustments as needed. WhizBudget can help you track your goals and stay on top of your finances with ease.

How to Choose a Budgeting Method That Works for You
Finding the right budgeting method is key to managing your finances effectively. The best approach depends on your spending habits, financial goals, and lifestyle. There’s no one-size-fits-all solution, but exploring different budgeting styles can help you determine what works best for you.
One popular method is the 50/30/20 rule, which keeps things simple by dividing your income into three categories: 50% for necessities like rent and bills, 30% for discretionary spending, and 20% for savings or debt repayment. This approach works well for those looking for an easy, balanced way to manage their money.
The envelope system can be a game-changer for those who struggle with overspending. With this method, you allocate cash into separate envelopes for different spending categories, like groceries, dining out, or entertainment, and once an envelope is empty, you stop spending in that category for the month. It’s a great way to control expenses and build discipline.
Some people prefer a more detailed approach, like zero-based budgeting. In this system, every dollar of your income is assigned a job, whether it’s for bills, savings, or personal spending, so that by the end of the month, your budget balances to zero. This method is ideal for those who want to track every expense closely and ensure their money is being used with purpose.
If saving is your top priority, the pay-yourself-first method might be the best fit. Instead of saving whatever is left at the end of the month, you set aside a fixed amount for savings first and then budget the rest for expenses. This approach ensures that building financial security comes before anything else.
Choosing the right budgeting method depends on your financial habits and goals. Some prefer the structure of zero-based budgeting, while others appreciate the flexibility of the 50/30/20 rule. The key is to find a system that feels natural and sustainable so you can stick with it long-term. If one method doesn’t work, don’t be afraid to try another until you find the perfect fit.

Understand Your Income and Expenses
Before creating a budget, it's important to have a clear picture of how much money is coming in and where it's going. Understanding your income and expenses helps you spot areas where you can make adjustments to reach your financial goals.
Start by tracking your income, which includes any money you earn regularly. This could be your salary after taxes, income from freelance work or side gigs, rental earnings, government benefits, or investment returns. Having a complete breakdown of your income sources gives you a better idea of what you're working with each month.
Next, take a close look at your expenses. These generally fall into two categories:
- Fixed expenses, like rent, insurance, and loan payments, which stay the same each month.
- Variable expenses, such as groceries, dining out, entertainment, and shopping, which can fluctuate.
Going through your bank statements or using budgeting apps can help you categorize and track your spending more accurately. Once you have a list, compare your total income to your total expenses. Are you consistently spending more than you earn? If so, it may be time to cut back in certain areas, like subscriptions or impulse purchases.
If you’re looking for an easy way to keep track of everything, there are plenty of tools available. While many paid apps offer useful features, WhizBudget stands out for its free tools and cross-device accessibility. If you prefer a more hands-on approach, spreadsheets like Google Sheets or Excel can work too, though they may not be as tidy or automated as an app.
Once you have a solid understanding of your income and expenses, you can make better financial decisions and create a budget that works for you. The key is consistency, regularly reviewing your finances will help you stay in control and work toward your goals.
Trending Topics


Recent Posts
How to Build a Bare-Bones Budget When Money Is Tight
Jul 24, 2026
How to Choose a Budgeting Method That Works for You
Nov 05, 2024