Saving Strategies
Ways to cut costs and grow savings
How to Cut Your Grocery Bill Without Coupons: A Practical 4-Week Plan
Learning how to save money on groceries does not require spending Sunday clipping coupons, eating the same meal every day or buying only the cheapest food available. The biggest savings usually come from a repeatable system: knowing what you spend, planning around food you own, buying with a clear list and wasting less.
This practical four-week plan focuses on sustainable habits for European households. It separates supermarket spending from restaurant, takeaway and delivery costs, so you can see what is really happening to your food budget. Use it to reduce grocery spending while still buying meals you enjoy.
Find Your Grocery Spending Baseline
Before trying to lower food costs, measure your starting point. Review the last four weeks of bank, card and cash spending. Put purchases into separate categories:
- Groceries: supermarket, market, bakery, butcher and household food shops.
- Eating out: cafés, restaurants, work lunches and takeaways.
- Delivery: meal-delivery apps and restaurant delivery fees.
- Non-food items: toiletries, cleaning products, batteries and other items bought at the supermarket.
This distinction matters. A €75 supermarket receipt is not necessarily €75 of food, and cutting your grocery budget will not solve frequent delivery spending. Add grocery-only transactions, then divide by four to find your average weekly amount.
For example, if you spent €520 on groceries last month, your baseline is €130 per week. Do not aim to halve it immediately. A first target of 10% to 15% is realistic: €117 to €110 per week. Use a free budget app such as WhizBudget to tag transactions and see the pattern without relying on memory.
Set a Realistic Weekly Grocery Budget
A useful grocery budget plan gives you a weekly number rather than one large monthly limit. Weekly limits are easier to manage because food shopping is frequent and prices vary. Keep a small monthly buffer for pantry restocks, school events or guests.
| Current weekly spend | First saving target | New weekly budget | Approximate monthly saving |
|---|---|---|---|
| €80 | 10% | €72 | €32 |
| €120 | 12% | €106 | €56 |
| €160 | 15% | €136 | €96 |
Set the budget according to household size, dietary needs, location and cooking time. A family in a city centre may pay more than a single person near discount supermarkets. The goal is not to compare your trolley with someone else’s; it is to spend less than your own normal level.
Build in one planned convenience item if it helps you avoid a €25 takeaway. A ready-made soup, frozen pizza or bagged salad can be a sensible budget choice when it prevents a more expensive last-minute decision.
Plan Low-Cost Meals Around What You Already Have
Pantry-first planning is one of the fastest ways to stop overspending on groceries. Before opening a shopping app or walking into a shop, check your fridge, freezer and cupboards. Write down food that needs using first, especially vegetables, cooked leftovers, opened dairy products and freezer portions.
Then build five or six evening meals around those ingredients. Leave one night flexible for leftovers, a simple omelette or a freezer meal. You do not need an elaborate meal-prep routine.
- Cooked rice + frozen vegetables + eggs = fried rice.
- Half a bag of lentils + tinned tomatoes + carrots = lentil soup or sauce.
- Roast chicken leftovers + wraps + yoghurt = quick lunch wraps.
- Soft vegetables + stock + beans = soup.
- Pasta + tinned fish + peas + lemon = low-cost cupboard dinner.
Plan meals by ingredient overlap. If you buy spinach for pasta, use the rest in omelettes or curry. If you buy a large tub of yoghurt, use it for breakfasts, sauces and snacks. This reduces grocery spending because every purchase has more than one job.
Use a Flexible Grocery List to Prevent Overspending
A list is not restrictive; it is a spending boundary. Divide it into three columns: essential meals, flexible staples and optional extras. Buy the essential meals first. Choose flexible staples only if they fit the remaining budget, and keep optional extras for the end.
| List type | Examples | Rule |
|---|---|---|
| Essential | Milk, vegetables, protein, lunch ingredients | Buy for planned meals |
| Flexible | Oats, rice, frozen veg, tinned beans | Buy when running low or well priced |
| Optional | Snacks, premium drinks, desserts | Buy only with money left |
Use a note on your phone and add items as they run out. Before checkout, compare the basket total with your weekly limit. If you are over, remove optional items or swap an expensive ingredient rather than abandoning the plan entirely.
Compare Unit Prices and Choose Lower-Cost Alternatives
Headline prices can be misleading. The unit price, usually shown per kilogram, litre or 100 grams, tells you what you actually pay. Comparing unit prices is a core cheap grocery shopping skill because packaging sizes and promotions can distort value.
Suppose a 500g bag of oats costs €1.29 and a 1kg bag costs €2.20. The first costs €2.58 per kg; the larger bag costs €2.20 per kg. The larger bag is better value only if you will use it before it goes stale and can afford the higher upfront cost.
Also compare brands and formats. Store-brand tinned tomatoes, dried pasta, rice, frozen vegetables and basic cleaning products are often comparable in quality to branded versions. Try switching one or two categories at a time rather than changing everything at once.
- Choose frozen berries or vegetables when fresh produce is expensive or likely to spoil.
- Use dried beans and lentils for some meals, while keeping tinned versions for busy days.
- Replace part of a meat-based meal with beans, mushrooms or lentils.
- Buy seasonal produce and substitute freely: cabbage for salad leaves, carrots for imported vegetables, apples for berries.
Be careful with multi-buy offers. “Three for two” saves nothing if you would normally buy one. Only treat an offer as a saving when it is planned, useful and within your budget.
Reduce Food Waste Before Buying More
Food waste is delayed overspending: you paid for food, then paid again to replace it. Create a visible “use first” area in the fridge for items nearing their best-before date. Keep leftovers in clear containers and label them with the date.
Once each week, schedule a use-up meal. Pasta bakes, soups, curries, frittatas and grain bowls are forgiving options. Freeze bread, herbs, grated cheese, cooked beans and individual portions before they become waste. Remember that a best-before date is usually about quality, not automatic safety; use your judgement and follow storage guidance.
Buying smaller packs can be cheaper overall than buying a larger pack that is partly thrown away. Value is what you eat, not merely the lowest unit price.
Shop Strategically Without Relying on Coupons
You can lower food costs without coupons by changing when, where and how you shop. Choose one main weekly shop and one small top-up visit if needed. Multiple browsing trips create more opportunities for impulse purchases.
- Do not shop hungry; eat a snack first.
- Try a discount supermarket or compare two nearby shops for your regular staples.
- Use supermarket own brands for basics and reserve premium brands for products you genuinely prefer.
- Check reduced-to-clear items only when you can cook or freeze them promptly.
- Shop online with a saved list if in-store browsing leads to overspending, but compare delivery and service fees.
- Pay attention at the checkout: a basket total is feedback, not a surprise.
Coupons can be useful, but they are optional. A system based on planned meals and sensible substitutions works even when no promotion is available.
Build a 4-Week Grocery Savings Challenge
Use this month-long challenge to turn individual ideas into a habit. Keep the same food standards; focus on eliminating unplanned spending and waste.
- Week 1: Measure and pause. Record every grocery purchase, set your weekly cap and make a pantry inventory. Do not try to be perfect; simply identify your usual triggers.
- Week 2: Plan and list. Plan five to six dinners from food you own, shop once with a three-part list and include one use-up meal.
- Week 3: Swap and compare. Compare unit prices on five regular products. Test two store-brand swaps and one lower-cost protein meal.
- Week 4: Waste less and review. Freeze leftovers, use up perishables and compare your four-week average with your original baseline. Keep the changes that felt easy.
A simple weekly workflow keeps the process manageable:
- Check cupboards, fridge and freezer for ten minutes.
- Choose meals based on what needs using.
- Make a list by shop section and set a maximum spend.
- Shop once, then store and freeze food properly.
- Review the receipt and note one lesson for next week.
Track Results and Adjust Your Food Budget
Tracking should be short enough to maintain. At the end of each week, complete this worksheet in a notebook, spreadsheet or WhizBudget:
| Week | Budget | Grocery spend | Difference | What worked? |
|---|---|---|---|---|
| 1 | €_____ | €_____ | €_____ | ________________ |
| 2 | €_____ | €_____ | €_____ | ________________ |
| 3 | €_____ | €_____ | €_____ | ________________ |
| 4 | €_____ | €_____ | €_____ | ________________ |
If you exceed the budget, look for the cause rather than blaming yourself. Was it a household restock, a social event, too little meal planning or takeaway spending recorded in the wrong category? Adjust the following week. A good grocery budget plan is flexible enough for real life and clear enough to show progress.
Frequently Asked Questions
How much can I realistically save on groceries each month?
Many households can save 10% to 15% by planning meals, reducing waste and comparing unit prices. Your result depends on your starting point, household size, dietary needs and local prices.
Is it cheaper to buy groceries online or in store?
Online shopping can reduce impulse buys because you see the running total, but delivery fees and substitutions can raise costs. In-store shopping may be cheaper if you stick to a list and compare unit prices. Test both methods for a month.
How do I save money on groceries with a busy schedule?
Use simple repeat meals, frozen vegetables, tinned beans and planned convenience foods. A ten-minute weekly plan and one main shop are more effective than ambitious meal prep you will not maintain.
Should I always buy the cheapest brand?
No. Compare unit prices and choose store brands for products you like, especially staples. It is reasonable to keep a few preferred branded items if they help you stick to your overall budget.
How do I stop overspending on groceries when shopping with children?
Set expectations before entering the shop. Give children a small planned choice, such as one fruit or one snack, and avoid shopping when everyone is hungry or rushed.
Do reduced items really save money?
They do only when you will use or freeze them promptly. A discounted item that spoils is not a saving, so buy reduced food with a specific meal or freezer plan.
Conclusion: Start With One Better Shop
The most reliable way to save money on groceries is not chasing every discount. It is building a routine: check what you have, plan flexible meals, make a list, compare unit prices and use the food you buy. Start this week with your spending baseline and one pantry-first meal plan.
Download WhizBudget, the free budget app, to track grocery spending separately from takeaways and delivery. Small weekly improvements can turn into meaningful monthly savings without making your meals feel restrictive.

How to Save Money on a Variable Income When Your Paychecks Change Every Month
When your income changes from one month to the next, saving can feel impossible. A freelancer may have one excellent client payment followed by a quiet month. Contractors can face gaps between projects, while commission-based and seasonal workers may earn most of their money in only part of the year.
The answer is not to wait for a perfect month or to use the same budget designed for a fixed salary. Learning how to save money on a variable income means building a plan around your lowest realistic earnings, then deciding in advance where extra income goes. This approach gives every payment a job without assuming that next month will look the same.
Why Saving Is Hard When Your Income Changes
With a fixed salary, it is easy to schedule bills and savings around a predictable payday. With irregular earnings, a large payment can create a false sense of security. It is tempting to spend as though that amount will arrive every month, only to feel squeezed when work slows down.
The real challenge is cash-flow timing. You may earn enough across a year but still struggle in individual months because invoices are paid late, commissions vary, or your busy season is short. Saving with irregular income works best when you separate three questions:
- What must I pay each month to keep life running?
- How much of this payment belongs to tax and near-term obligations?
- What percentage can I put toward future goals before increasing discretionary spending?
That structure turns an unpredictable income into a series of manageable decisions.
Calculate Your Minimum Monthly Income and Core Expenses
Start with a conservative income baseline. This is not your average month and not your best month. It is the lowest amount you can reasonably expect to receive in a normal working month, based on the past 12 months if possible. If your work is new, use your lowest recent reliable month and revise it as you collect more data.
Next, list your core monthly expenses: housing, utilities, basic food, transport, insurance, debt minimums, childcare, phone and essential subscriptions. Include annual or quarterly bills by dividing them into monthly amounts. For example, a €360 annual insurance bill equals €30 per month.
| Monthly core expense | Example amount |
|---|---|
| Rent or mortgage | €850 |
| Utilities and phone | €180 |
| Food and household basics | €320 |
| Transport and insurance | €190 |
| Debt minimums and essential subscriptions | €110 |
| Total core expenses | €1,650 |
Compare this total with your conservative income baseline. If your baseline is €2,000 and core costs are €1,650, you have €350 of planned room. If core costs exceed your baseline, reduce flexible costs, review fixed bills, or seek ways to stabilise income before setting ambitious savings goals. A variable-income budget must survive an ordinary slow month.
Create a Variable-Income Spending Baseline
Your spending baseline is the amount you allow yourself to use in a lean month. It includes core expenses plus a realistic, limited amount for flexible spending such as coffee, social plans, clothing and hobbies. Think of it as your “normal month” lifestyle, not a punishment budget.
Set this baseline from your conservative income, rather than from whatever lands in your account. For instance, if your minimum monthly income is €2,000, you might allocate €1,650 to core costs, €150 to flexible spending and €200 to planned saving or future expenses. Any income above €2,000 is then handled by rules, not impulse.
This is the key difference between a standard budget and a variable income budget: expenses are anchored to the floor of your income, while higher earnings are allocated separately. Review your baseline every three to six months, especially after rent changes, a new contract or major lifestyle changes.
Use a Separate Buffer Account for High-Income Months
A cash-flow buffer account holds money that smooths the gap between high-income and low-income months. It is different from money set aside for a specific goal: its purpose is to help you pay yourself your baseline amount when client work is quiet or payments arrive later than expected.
Keep this account separate from your daily spending account so a strong month does not look like spendable cash. After a large payment arrives, move the portion intended to cover future baseline months into the buffer. Then transfer a set amount from the buffer to your current account each month, as if you were paying yourself a salary.
- Choose a target, such as one to three months of your spending baseline.
- In high-income months, direct a fixed share of surplus income to the buffer.
- In low-income months, use the buffer only to bring available cash up to your baseline.
- Refill it after the next strong payment instead of treating it as extra spending money.
This makes cash flow easier to read and reduces the urge to make dramatic spending changes every time a payment is late.
Set a Percentage-Based Savings Rule
Fixed euro amounts can be difficult when income fluctuates. A percentage rule scales with what you earn, so you continue the habit in both modest and strong months. Choose percentages that fit your actual situation and apply them to every payment after reserving tax where required.
A practical starting point might be 10% for short-term goals and 5% for long-term savings or investing. If your margins are tight, begin with 2% to 5%. The percentage matters less than using a rule you can maintain. When income rises, your savings rise automatically without requiring a new decision.
You can use separate percentages for different priorities:
- Cash-flow buffer: 10% to 20% of surplus income until your target is reached.
- Short-term goals: 5% to 15% for planned purchases, travel or annual bills.
- Long-term savings: 5% to 15%, subject to your goals, risk tolerance and local investment options.
Track these allocations in a free budget app such as WhizBudget. Seeing each category separately helps you avoid confusing money for next month’s bills with money available for a goal.
Prioritise Savings When a Large Payment Arrives
Large payments need a clear order of priority. Do not wait until the end of the month to see what remains; by then, the surplus may have disappeared into unplanned spending. Divide the payment as soon as it clears.
Here is a worked example for a freelancer who receives €5,000 in a strong month. Their usual monthly baseline is €2,000, and they need to reserve money for taxes based on their local rules. The example uses a 25% tax allocation for illustration only; your rate may be very different.
| Allocation | Amount | Purpose |
|---|---|---|
| Taxes (25%) | €1,250 | Held separately for tax payments |
| Essential expenses | €1,650 | Core costs for the current month |
| Flexible spending | €150 | Within the monthly baseline |
| Cash-flow buffer | €900 | Supports future low-income months |
| Short-term goal savings | €600 | Annual costs, planned purchase or travel |
| Long-term savings | €450 | Long-range financial goals |
| Total | €5,000 |
The exact split will vary, but the sequence is useful: reserve tax, fund this month’s baseline, strengthen future cash flow, then fund goals. Any remaining amount can be allocated deliberately rather than absorbed by lifestyle inflation.
Plan for Taxes, Slow Seasons and Income Gaps
For self-employed workers, tax money is not available income. Keep it in a separate account from the day you are paid. Tax systems differ across Europe, and VAT, social contributions, income tax instalments and deductible expenses can all affect what you should reserve. Use recent returns, an accountant or your tax authority’s guidance to estimate your percentage.
Also map your seasonal pattern. Review the last year and mark months when work or sales typically slow down. If you earn most of your income from May to September, your cash-flow plan should intentionally fund the autumn and winter months. This is cash flow planning for freelancers and seasonal workers: match money received in busy periods to expenses due throughout the year.
Create a simple calendar for irregular costs too, including professional memberships, software renewals, vehicle costs, holiday travel and tax deadlines. A predictable annual bill should not become a financial surprise simply because it is not monthly.
Adjust Your Savings Target Without Abandoning the Habit
Some months will be genuinely lean. When that happens, reduce your savings percentage if necessary, but avoid stopping the system entirely unless essential costs require it. A small contribution keeps your process active and makes it easier to increase again when work improves.
For example, if your usual long-term savings rate is 10%, you might lower it to 3% during a slow month, then return to 10% or add a little more after the next major invoice. This is how to save when income fluctuates without relying on all-or-nothing thinking.
Use a monthly review to compare income received, baseline spending, tax set-asides and buffer balance. WhizBudget can make this easier by showing whether your spending stayed within the baseline and whether each payment was allocated according to your rule.
Common Mistakes People Make With Irregular Income
- Budgeting from the best month: This leads to commitments that cannot be supported when work is quieter.
- Spending before reserving tax: Tax bills can disrupt otherwise healthy finances.
- Keeping all money in one account: It becomes too easy to spend funds intended for future months or goals.
- Using averages without checking timing: Annual income may look fine while monthly cash flow remains difficult.
- Increasing lifestyle costs after one strong payment: Recurring upgrades can create pressure long after the large payment is gone.
- Giving up after a low-income month: Adjusting the percentage is more effective than abandoning your saving routine.
Frequently Asked Questions
How much should I save with an irregular income?
Start with a percentage you can sustain, such as 5% to 10% of income after tax set-asides. If money is tight, even 2% to 5% builds the habit. Increase the rate in stronger months rather than committing to a fixed amount you cannot meet consistently.
Should I budget using my average income or my lowest income?
Use a conservative, reliable income figure to set your core spending baseline. An average can help with annual planning, but it may hide low months. Build regular spending around a lower figure and allocate income above it using clear rules.
What is a cash-flow buffer account?
It is a separate account used to smooth uneven pay. You add money during high-income months and use it to cover your normal spending baseline during slower months or delayed payment periods.
How do freelancers save for taxes?
Reserve a percentage from every client payment in a separate tax account. The appropriate percentage depends on your country, income, deductible expenses, VAT position and social contributions, so check official guidance or consult a qualified tax professional.
What should I do after receiving a large client payment?
Allocate it immediately: first reserve tax, then cover core expenses, add to your cash-flow buffer, and fund short-term and long-term savings goals. This prevents a one-off payment from turning into unplanned spending.
Can I save money in a low-income month?
Yes, but the amount may be small. Lower your savings percentage temporarily while protecting essential spending. The goal is to maintain a flexible system, not to force an unrealistic contribution.
Build a Saving System That Works in Every Season
Variable earnings do not prevent you from saving; they simply require a different structure. Set spending from a conservative income baseline, separate future-month cash from daily spending, reserve tax early and use percentages to allocate every payment. Over time, strong months will support quiet ones instead of disappearing without a plan.
Ready to see where each payment should go? Use WhizBudget, the free budget app, to track your baseline, savings goals and cash-flow buffer in one clear place. Start with your next payment and give every euro a purpose.
How to Save for a Down Payment on a Low Income: A Realistic Step-by-Step Plan
Buying a home on a limited income can feel out of reach, especially when prices, rents and everyday bills leave little spare cash. But a low income does not automatically rule out homeownership. The key is to build a target that reflects your real costs, create a repeatable monthly system and use every legitimate source of support available.
This guide explains how to save for a down payment on a low income without relying on extreme cutbacks or draining your emergency fund. The goal is steady progress: a practical down payment savings plan that works with your current circumstances and can improve as your income grows.
Set a Realistic Homebuying Savings Target
Before deciding how much to save each month, work out the full amount you will need. Focusing only on the deposit can leave you short when it is time to make an offer, complete the purchase or move in.
Your target should include four parts:
- Down payment or deposit: The amount required by your lender. Requirements vary by country, lender, property type and your credit profile.
- Purchase and closing costs: These can include valuation or survey fees, legal or notary fees, lender fees, taxes, registration charges and insurance.
- Moving and setup costs: Include removals, utility deposits, basic furniture, repairs and appliances.
- Post-purchase cash cushion: Keep money aside for unexpected repairs or a temporary income disruption after you move.
For example, if you hope to buy a €180,000 home and need a 10% deposit, the deposit is €18,000. Add €5,000 for taxes and transaction costs, €2,000 for moving and €3,000 as a cash cushion. Your real savings target is €28,000, not €18,000.
How much to save for a down payment depends on local lending rules. In some markets, buyers may qualify with a smaller deposit, while a larger deposit can reduce monthly repayments and improve lender options. Ask a regulated mortgage adviser or lender for a realistic affordability estimate before setting a fixed property price.
Calculate How Much You Can Save Each Month
A useful first-time homebuyer savings strategy starts with your actual cash flow, not an idealised budget. Review the last two or three months of bank statements and identify your average take-home income and essential spending.
| Sample monthly budget | Amount |
|---|---|
| Take-home pay | €2,000 |
| Rent, utilities and insurance | €900 |
| Food and household essentials | €320 |
| Transport | €180 |
| Minimum debt payments | €120 |
| Phone, healthcare and other essentials | €180 |
| Flexible spending | €160 |
| Available for goals | €140 |
In this example, €140 a month equals €1,680 a year before interest, gifts or extra income. That may not look dramatic, but it creates a foundation. If the saver later adds €60 through lower costs and €100 from occasional extra work, they reach €300 a month, or €3,600 a year.
Start with an amount you can sustain even in an expensive month. Automate it for the day after payday. Saving €75 reliably is better than planning to save €300 and repeatedly transferring it back.
Choose the Right Down Payment Account
Money needed within the next few years should usually be protected from large investment swings. A dedicated savings account keeps your house fund separate from everyday spending and makes progress easier to see.
- Easy-access savings account: Suitable when your buying timeline is uncertain or you need flexibility.
- Notice or fixed-term savings account: May offer a better rate, but check access rules and penalties before locking money away.
- Government-supported homebuyer account: Some European countries offer tax advantages, bonuses or matched savings schemes for qualifying buyers. Check contribution limits, property rules and withdrawal conditions.
- Cash account versus investments: If you expect to buy within roughly five years, cash is often the safer choice. Investments can fall in value just when you need the money.
Keep your emergency fund separate from the down payment account. Name the account clearly, such as “Home Deposit + Costs,” and set up an automatic transfer. WhizBudget, a free budget app, can help you label this goal and see whether your monthly savings are on track.
Find Room in Your Budget Without Cutting Essentials
When you save for a house on a low income, the biggest gains usually come from your largest recurring costs, not from giving up every small pleasure. Never cut food, healthcare, necessary insurance or debt payments simply to make a larger transfer into savings.
Review these areas first:
- Housing: If safe and practical, consider a house share, moving at the end of a lease, taking in a lodger where permitted, or negotiating bills with housemates. Even a temporary reduction in rent can accelerate your target.
- Transport: Compare public transport passes, cycling, car-sharing and insurance quotes. If you own a costly car, calculate its full monthly cost, including fuel, maintenance, parking and depreciation.
- Utilities and subscriptions: Switch tariffs where available, cancel duplicate streaming services and review mobile plans. Direct the exact savings to the house fund.
- Food: Plan a weekly menu, use a shopping list, buy store brands and reduce convenience purchases. Aim for realistic savings, not a restrictive diet.
- Debt: High-interest credit card or consumer debt can make mortgage approval harder. Paying it down may be a better use of extra money than adding every euro to the deposit.
Use a “one change at a time” approach. Choose two expenses to improve this month, then check whether the saving actually appeared in your account. This is more effective than creating a harsh budget you cannot maintain.
Increase Your Savings Rate With Income Boosts
Cost-cutting has a limit, particularly on a low income. Increasing income, even temporarily, can make a major difference to a down payment savings plan.
Consider options that fit your skills, schedule and local rules:
- Ask about overtime, additional shifts or a pay review at your current job.
- Take freelance work in administration, tutoring, translation, design, childcare or pet care.
- Sell unused electronics, clothing, furniture or hobby equipment.
- Offer seasonal services, such as holiday cover, gardening or event work.
- Train for a qualification that improves your pay or job prospects, while checking the cost and likely return.
Assign income boosts before you receive them. A simple rule is to send 50% to 80% of side income to your home fund and use the rest for tax, work expenses or normal life. If freelance income is taxable in your country, keep a separate amount for tax rather than accidentally spending money you will owe later.
Use Windfalls and Tax Refunds Strategically
Windfalls can shorten the timeline without increasing your regular monthly pressure. This includes tax refunds, bonuses, gifts, rebates, back pay and proceeds from selling belongings.
Before transferring a windfall, use this order:
- Catch up on essential bills or overdue payments.
- Build or restore a basic emergency fund.
- Pay down high-interest debt.
- Put the remainder into your deposit fund.
You do not need to send 100% of every windfall to savings. Keeping a small planned portion for enjoyment can make the process sustainable. The important part is deciding in advance, rather than letting the money disappear through unplanned spending.
Research Down Payment Assistance Programs
Down payment assistance programs may make buying possible sooner, but they are not all the same. Depending on where you live, support may come from a national government, local authority, housing association, employer or charity. It can take the form of a grant, shared-equity arrangement, matched savings, low-deposit mortgage guarantee, subsidised loan or tax benefit.
Read the conditions carefully. Assistance may have income limits, first-time buyer requirements, maximum purchase prices, residency rules or restrictions on renting out the property. Some support is a true grant that does not need repayment; others are loans or equity arrangements that are repaid on sale, refinancing or after a set period.
Do not assume an advertised scheme is free money. Confirm the repayment terms, fees, effect on future equity and whether the provider is legitimate. A mortgage adviser, local housing office or official government housing website can help you identify current programmes in your area.
Avoid Common Mistakes That Delay Homebuying
- Emptying your emergency savings: A home purchase without a cash buffer can leave you relying on expensive credit after one repair or missed pay cheque.
- Taking on new high-interest debt: Buy-now-pay-later balances, credit cards and personal loans can affect affordability checks.
- Saving only for the deposit: Budget for transaction costs, moving and immediate repairs.
- Ignoring your credit record: Check your report early, correct errors and pay bills on time. Requirements differ by country, but payment history matters to many lenders.
- Chasing a target that no longer fits: Revisit property prices and lending conditions regularly so your goal remains realistic.
Track Progress With Quarterly Milestones
A long-term target is easier to manage when divided into short checkpoints. If your total goal is €24,000 and you can save €250 a month, your base timeline is eight years. That is useful information, not failure: it tells you that lower housing costs, income growth, a lower-priced area or assistance programmes may need to be part of the plan.
Set quarterly milestones and review three numbers: your total house fund, your average monthly saving and your debt balance. For example:
| Quarter | Monthly saving goal | Target balance added |
|---|---|---|
| Months 1–3 | €150 | €450 |
| Months 4–6 | €200 | €600 |
| Months 7–9 | €250 | €750 |
| Months 10–12 | €250 plus windfalls | €750+ |
Use WhizBudget to compare your plan with what you actually spent, then adjust the next quarter instead of giving up after an imperfect month. A home fund grows through consistency, not perfection.
Frequently Asked Questions
Can I save for a down payment on a low income?
Yes. Start with a sustainable automatic amount, reduce one or two major expenses where possible, seek income increases and investigate local buyer support. The timeline may be longer, but steady savings and improved affordability can move you closer.
How much should I save for a down payment?
Save for the lender’s required deposit plus purchase costs, moving costs and an emergency cushion. Deposit requirements vary widely by location and lender, so get an estimate based on your target area and financial profile.
Should I use my emergency fund for a house deposit?
Usually no. Keep emergency savings separate so an unexpected expense does not force you into high-interest debt or put mortgage payments at risk after you buy.
Are down payment assistance programs grants?
Some are grants, but others are loans, guarantees, shared-equity schemes or tax benefits. Always check eligibility, repayment requirements, fees and restrictions before applying.
Is it better to pay off debt or save for a home first?
High-interest debt usually deserves priority because it is expensive and may reduce your mortgage affordability. You can still keep a small automatic home savings transfer going to maintain the habit while you reduce debt.
Where should I keep my down payment savings?
For a purchase planned within a few years, a separate cash savings account is generally more suitable than volatile investments. Compare interest rates, access terms, deposit protection and any government homebuyer incentives available where you live.
Conclusion: Build Your Home Fund One Month at a Time
Saving for a home on a limited income is not about finding a perfect budget. It is about setting a complete target, protecting your financial safety net and making regular progress with the money you genuinely have available. Start with one automated transfer, review your biggest costs and use extra income and eligible support to accelerate your plan.
Create your down payment savings plan today with WhizBudget, the free budget app that helps you track spending, organise savings goals and stay focused on your next milestone.
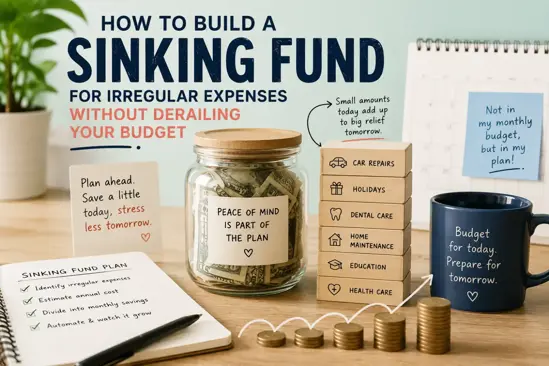
How to Build a Sinking Fund for Irregular Expenses Without Derailing Your Budget
If your monthly budget looks fine on paper but falls apart whenever the car needs repairs, your insurance renewal arrives, or school costs pop up, you are not bad with money. You are probably just budgeting for a normal month and forgetting that real life is not monthly.
Many household costs in Europe are irregular. They may happen once a year, twice a year, seasonally, or without a neat pattern. Car maintenance, annual subscriptions, holidays, property taxes, medical co-payments, Christmas, back-to-school costs, vet bills, and insurance premiums can all disrupt your cash flow if you treat them as surprises.
A sinking fund for irregular expenses solves this problem. Instead of panicking when a large bill arrives, you save a smaller amount every month in advance. This article explains how to save for irregular expenses using simple formulas, realistic examples, and a practical system you can repeat every year.
What Is a Sinking Fund and Why It Matters
A sinking fund is money you set aside regularly for a specific future expense. The expense might be predictable, such as an annual car insurance premium, or semi-predictable, such as car repairs. The point is to spread the cost over time instead of letting it crash into one month.
For example, if your annual home insurance costs €480, you can save €40 per month. When the bill arrives, the money is already waiting. Your monthly budget stays stable, and you do not need to rely on a credit card, overdraft, or last-minute transfer from savings.
Sinking funds matter because they make your budget more honest. A monthly budget that ignores annual expenses is incomplete. You may think you have €300 left over each month, but if you have not accounted for Christmas, car service, insurance renewals, or holiday travel, that money is already partly spoken for.
The goal is not to make your budget more complicated. The goal is to make it more realistic. A good sinking fund system turns large, stressful costs into small, planned monthly savings amounts.
Sinking Fund vs Emergency Fund: Key Differences
A sinking fund and an emergency fund are both savings tools, but they are not the same. Mixing them together often causes problems. If you use your emergency fund for annual bills, it may not be available when a real emergency happens.
| Feature | Sinking Fund | Emergency Fund |
|---|---|---|
| Purpose | Planned or expected irregular expenses | True financial emergencies |
| Examples | Insurance premium, car service, holidays, school costs | Job loss, urgent medical cost, essential home repair |
| Timing | Often predictable or estimated | Unpredictable |
| Amount | Based on known future costs | Usually 3 to 6 months of essential expenses |
| How often used | Regularly throughout the year | Only when necessary |
Think of a sinking fund as your plan for known bumps in the road. Think of an emergency fund as your safety net when the road disappears entirely.
For example, replacing worn tyres is usually not an emergency if you knew they were getting old. It belongs in a car maintenance sinking fund. Losing your job and needing to cover rent or mortgage payments is an emergency fund situation.
Common Irregular Expenses You Should Plan For
The first step in budgeting for non monthly expenses is to identify the costs that do not fit neatly into your regular monthly bills. Start by looking through the past 12 months of bank statements and card transactions. Highlight every expense that was not part of your normal monthly routine.
Common sinking fund categories include:
- Car costs: servicing, repairs, tyres, MOT or roadworthiness tests, toll tags, parking permits, registration fees, and insurance excesses.
- Insurance premiums: car insurance, home insurance, life insurance, health insurance top-ups, travel insurance, and pet insurance if paid annually.
- Home and property: boiler servicing, appliance replacement, property tax, minor repairs, garden maintenance, and furniture replacement.
- Medical and dental: dental check-ups, glasses, prescriptions, physiotherapy, specialist appointments, and co-payments.
- Family and school costs: uniforms, books, school trips, childcare deposits, sports equipment, and exam fees.
- Holidays and travel: flights, accommodation, spending money, passports, luggage, and transport to the airport.
- Seasonal events: Christmas, birthdays, weddings, religious celebrations, and family visits.
- Subscriptions and memberships: annual software, gym membership, professional memberships, streaming renewals, and cloud storage.
- Pets: vaccinations, vet check-ups, grooming, pet boarding, and unexpected but non-emergency care.
You do not need 30 separate funds. Too many categories can become hard to manage. A useful approach is to group similar costs. For example, instead of separate funds for tyres, servicing, and repairs, you could use one car maintenance fund.
How to Calculate Your Monthly Sinking Fund Amount
The basic sinking fund formula is simple:
Total expected cost ÷ number of months until due = monthly sinking fund amount
If your car insurance is €720 and it is due in 12 months, the calculation is:
€720 ÷ 12 = €60 per month
If Christmas usually costs €900 and you have 9 months left to save, the calculation is:
€900 ÷ 9 = €100 per month
For expenses that are not exact, use a realistic estimate based on previous years. If you spent €550 on car repairs last year and €700 the year before, you might set a target of €650 or €700. It is better to slightly overestimate essential categories than to be short when the bill arrives.
For annual expenses budget planning, make a list with four columns:
- Expense category
- Expected annual cost
- Due date or likely timing
- Monthly savings amount
Here is a simple example:
| Expense | Expected Cost | Months to Save | Monthly Amount |
|---|---|---|---|
| Car insurance | €720 | 12 | €60 |
| Car maintenance | €600 | 12 | €50 |
| Christmas | €900 | 9 | €100 |
| School costs | €480 | 6 | €80 |
| Holiday travel | €1,200 | 12 | €100 |
In this example, the household needs to set aside €390 per month. That may feel high, but remember: these costs are happening anyway. The sinking fund simply reveals the true monthly cost of your lifestyle and commitments.
Step-by-Step Method to Set Up Your Sinking Fund
Use this process to build a system that is clear, repeatable, and easy to maintain.
- Review the last 12 months. Go through bank statements, credit card statements, and payment apps. List every irregular expense over €25 or €50, depending on your income level.
- Group expenses into categories. Use practical sinking fund categories such as car, home, insurance, school, holidays, gifts, medical, and pets.
- Estimate annual totals. Use last year as a guide, but adjust for price increases. In many European countries, insurance, travel, utilities, and food-related celebration costs have risen, so avoid using outdated numbers.
- Set target dates. If the cost has a fixed due date, write it down. If not, choose a planning period, such as 12 months.
- Calculate monthly amounts. Divide each target by the number of months available. Round up to the nearest €5 or €10 to create a small buffer.
- Add it to your monthly budget. Treat sinking fund contributions like a bill you pay to yourself. Do not wait to see what is left at the end of the month.
- Automate transfers. Set up a standing order just after payday. Automation removes the need for monthly willpower.
- Track balances. Use a spreadsheet, banking pots, envelopes, or a budgeting tool such as WhizBudget to see how much belongs to each category.
- Review quarterly. Every three months, check whether your estimates are still realistic. Adjust for new bills, price changes, or categories you forgot.
The most important step is automation. If you manually move money only when you remember, the system will be unreliable. A sinking fund works best when it becomes part of your normal payday routine.
Where to Keep Your Sinking Fund Money
Your sinking fund should be safe, easy to access, and separate from everyday spending. You are not investing this money for long-term growth. You are parking it until a known cost arrives.
Good options include:
- Instant-access savings account: Suitable for most sinking funds because you can withdraw when needed.
- Bank sub-accounts or pots: Many European banks and fintech apps allow separate spaces for goals such as car, holidays, and insurance.
- Separate current account: Useful if your bank does not offer pots, but you still want to keep the money away from daily spending.
- Cash envelopes: May work for small categories, but are less secure and less practical for large bills or online payments.
Avoid locking sinking fund money into accounts with withdrawal penalties unless you are certain you will not need it early. Also avoid investing short-term sinking funds in stocks or funds. If markets fall just before your insurance or school payment is due, you could be forced to sell at a loss.
If possible, earn some interest, but do not chase returns at the expense of access. The main job of a sinking fund is stability.
How to Prioritize Sinking Funds When Money Is Tight
If your budget is already stretched, seeing a list of sinking funds can feel overwhelming. Do not give up. You can start with the most urgent and essential categories first.
Use this priority order:
- Legal or compulsory costs: car insurance, property tax, required registration fees, and essential documentation.
- Essential living costs: home repairs, heating system maintenance, medical care, school basics, and transport needed for work.
- High-risk costs: car repairs if you depend on your vehicle, pet care if you have an older pet, or appliance replacement if an item is already failing.
- Quality-of-life costs: holidays, gifts, celebrations, hobbies, and non-essential subscriptions.
When money is tight, do not try to fully fund every category immediately. Instead, choose a starter amount. Even €10 or €20 per month toward a future bill is better than saving nothing.
You can also use the deadline method. Fund the categories with the nearest due dates first. For example, if school costs are due in two months and home insurance is due in ten months, school costs may need attention first.
If the total sinking fund amount is higher than you can afford, your budget is showing you a useful truth: some future costs need to be reduced, delayed, or planned differently. That might mean choosing a shorter holiday, buying second-hand school items, comparing insurance quotes before renewal, or spreading large purchases over a longer saving period. The goal is not vague advice like spend less. The goal is to match your future plans to your actual cash flow.
Example Sinking Fund Budget for a Real Household
Imagine a household in Ireland, Spain, Germany, or France with two adults, one child, one car, and a rented or mortgaged home. Their monthly income after tax is €3,800. Regular monthly bills, groceries, transport, and minimum debt payments total €3,150. That leaves €650 before irregular expenses, extra debt payments, and personal spending.
After reviewing the last year, they identify these irregular costs:
| Category | Annual Estimate | Monthly Sinking Fund | Notes |
|---|---|---|---|
| Car maintenance and tyres | €720 | €60 | Based on service, small repairs, and tyre replacement |
| Car insurance excess and renewal gap | €360 | €30 | Extra buffer for policy changes or excess |
| Home maintenance | €600 | €50 | Small repairs, appliance fund, boiler service |
| School costs | €600 | €50 | Books, trips, uniform, sports items |
| Medical and dental | €480 | €40 | Check-ups, prescriptions, dental cleaning |
| Christmas and gifts | €960 | €80 | Gifts, food, travel, events |
| Holiday | €1,200 | €100 | Accommodation, travel, spending money |
| Annual subscriptions | €240 | €20 | Software, memberships, streaming annual plans |
The total sinking fund contribution is €430 per month. This leaves €220 from the original €650 for extra debt payments, personal spending, or additional savings.
Before using sinking funds, this household may have thought they had €650 spare each month. In reality, €430 of that was needed for predictable future costs. Without a sinking fund, those costs would likely end up on a credit card or come from their emergency fund.
This is the power of an annual expenses budget. It turns an unclear surplus into a realistic plan.
Mistakes to Avoid When Managing Sinking Funds
Sinking funds are simple, but a few common mistakes can weaken the system.
- Using one vague savings account. If all money sits in one pot with no labels, it is easy to spend holiday money on car repairs and then be short later.
- Forgetting inflation and price increases. If last year cost €800, this year may cost €850 or €900. Review your numbers.
- Not saving until the bill is close. The sooner you start, the lower the monthly amount. Waiting until three months before an annual bill makes the contribution much harder.
- Confusing wants with essentials. A holiday fund is useful, but it should not come before legally required insurance or essential medical care.
- Raiding funds for daily spending. If you keep dipping into sinking funds for groceries or nights out, your monthly budget needs adjusting.
- Setting too many categories. Ten clear categories are usually better than forty tiny ones. Keep the system manageable.
- Ignoring one-off upcoming events. Weddings, moving costs, a new baby, or a major birthday may need temporary sinking funds.
Another mistake is expecting your first version to be perfect. It will not be. Your first year of sinking funds is partly a learning year. You will discover categories you missed and estimates that were too low. Adjust and continue.
Tools and Apps That Can Help Track Sinking Funds
You can track sinking funds in several ways. The best tool is the one you will actually use.
- Spreadsheet: Good for people who like control and simple formulas. Create columns for category, target, current balance, monthly contribution, and due date.
- Banking pots or spaces: Useful if your bank allows separate savings goals. You can visually separate money without opening many accounts.
- Budgeting app: Helpful if you want your monthly budget and sinking funds in one place. WhizBudget can help you plan categories, track balances, and see how irregular expenses affect your real monthly cash flow.
- Notebook or paper planner: Works if you prefer a physical system, but you must update it consistently.
Whichever tool you use, make sure it answers three questions quickly:
- How much do I need for this category?
- How much do I have saved right now?
- How much must I add each month to stay on track?
If your system cannot answer those questions, it is too unclear. Keep simplifying until it can.
FAQs
What is a sinking fund for irregular expenses?
A sinking fund for irregular expenses is money saved regularly for costs that do not happen every month. Examples include car repairs, insurance renewals, Christmas, school costs, holidays, and annual subscriptions.
How much should I put in a sinking fund each month?
Use the formula: expected cost divided by the number of months until it is due. If a bill is €600 and due in 12 months, save €50 per month. For uncertain costs, estimate based on previous years and round up slightly.
Should I have separate sinking funds for every expense?
Not necessarily. Separate categories are useful, but too many can become confusing. Group similar expenses, such as car costs, home maintenance, medical, gifts, school, holidays, and insurance.
Is a sinking fund the same as emergency savings?
No. A sinking fund is for expected or planned costs. Emergency savings are for serious unexpected events such as job loss, urgent essential repairs, or sudden income disruption. Both are important.
Where should I keep my sinking fund money?
Keep it in a safe and accessible place, such as an instant-access savings account, bank pots, or a separate current account. Avoid risky investments for money you will need within the next year or two.
What if I cannot afford all my sinking funds right now?
Start with the most essential and urgent categories. Prioritize compulsory bills, transport needed for work, housing, medical care, and school basics. Add smaller amounts to lower-priority funds when your budget allows.
Can sinking funds help with unexpected expenses savings?
Yes, but they do not replace an emergency fund. Sinking funds reduce the number of expenses that feel unexpected because you have planned for them. Your emergency fund can then be reserved for true emergencies.
Conclusion
Irregular expenses are not rare exceptions. They are a normal part of personal finance. If you do not plan for them, they will keep derailing your budget, draining your emergency fund, or pushing you toward debt.
A sinking fund gives every future bill a monthly plan. Start by reviewing your past spending, choose practical categories, calculate monthly amounts, automate transfers, and track your progress. Even if you begin with only a few categories, you will quickly feel more prepared and less reactive.
If you want a clearer way to manage sinking funds alongside your everyday budget, WhizBudget can help you organise categories, plan ahead, and make irregular expenses easier to handle. Build your first sinking fund today, and give your future bills a place in your budget before they arrive.
How to Build an Emergency Fund: Step-by-Step Guide
What is an Emergency Fund?
An emergency fund is a savings account specifically set aside to cover unexpected expenses or financial emergencies. These can include medical bills, car repairs, or sudden job loss. Having an emergency fund provides financial security and peace of mind.
Why You Need an Emergency Fund
Building an emergency fund is crucial for several reasons:
- Financial Security: It acts as a safety net, protecting you from sudden financial shocks.
- Peace of Mind: Knowing you have funds set aside reduces stress during uncertain times.
- Avoiding Debt: An emergency fund helps you avoid relying on credit cards or loans, which can lead to debt accumulation.
Steps to Build Your Emergency Fund
- Set a Savings Goal: Determine how much you need in your fund, typically 3 to 6 months’ worth of expenses.
- Open a Separate Savings Account: Keep your emergency fund separate from your regular accounts to avoid the temptation of spending it.
- Automate Your Savings: Set up automatic transfers to your emergency fund every month.
- Cut Unnecessary Expenses: Review your budget and identify areas where you can cut back to increase your savings.
- Increase Your Income: Consider side jobs or freelance work to boost your savings more quickly.
How Much Should You Save?
Most financial experts recommend saving three to six months’ worth of living expenses. For example, if your monthly expenses are €1,500, aim for an emergency fund of €4,500 to €9,000. Adjust based on your personal circumstances, job stability, and financial obligations.
Where to Keep Your Emergency Fund
Choose a savings account that offers easy access and minimal fees. Online banks often provide higher interest rates than traditional banks. Some good options include:
- High-yield savings accounts
- Money market accounts
- Short-term certificates of deposit (CDs)
Common Mistakes to Avoid
- Not Saving Enough: Underestimating your emergency fund needs can leave you vulnerable.
- Using the Fund for Non-Emergencies: Only use your emergency fund for true emergencies to maintain its purpose.
- Neglecting to Replenish: If you use the fund, make sure to replenish it as soon as possible.
FAQs
1. How quickly should I build my emergency fund?
Start saving as soon as possible. Aim to reach your goal within one to three years, depending on your financial situation.
2. Can my emergency fund earn interest?
Yes, consider placing your emergency fund in a high-yield savings account to earn interest over time.
3. Is it okay to invest my emergency fund?
It's best to keep your emergency fund in a liquid account for quick access, rather than investing it in volatile assets.
4. How do I know when to use my emergency fund?
Use your emergency fund for unexpected expenses that cannot be covered by your regular budget.
5. Can I use my emergency fund for planned expenses?
No, the purpose of an emergency fund is to cover unplanned expenses only.
6. How can WhizBudget help with my emergency fund?
WhizBudget is a helpful budgeting tool that allows you to track your savings goals and manage your finances effectively.
7. What if I exhaust my emergency fund?
If you use your emergency fund, prioritize rebuilding it as soon as possible to maintain financial security.
Conclusion
Building an emergency fund is a vital step in achieving financial stability. By following the steps outlined above and using tools like WhizBudget to track your progress, you can ensure that you are prepared for any unexpected expenses that may come your way. Start today, and take control of your financial future!

Micro-Saving Hacks That Add Up: 15 Tricks That Actually Work
What are the best micro-saving hacks that work?
The most effective micro-saving tricks include rounding up purchases, automating transfers, setting no-spend days, and using cashback apps. Small, consistent actions like these build up your savings over time, without feeling like a sacrifice.
Saving money doesn't always require big changes. Sometimes, it's the tiny tweaks to your everyday habits that make the biggest difference. These micro-saving strategies are easy to implement, stress-free, and proven to help people boost their savings with minimal effort.
Whether you're living paycheck to paycheck or just want to save more without noticing, these 15 micro-saving hacks will help you stay on track.
1. Round Up Your Purchases Automatically
Link your debit card to an app that rounds up your purchases to the nearest dollar and saves the change.
- Spend $3.45 → $0.55 goes to savings
- Works well with budgeting apps like Qapital or banking features that support this
- Set and forget style saving
2. Use the 24-Hour Rule Before Buying Non-Essentials
Impulse buying kills savings. This rule gives you time to reflect:
- Wait 24 hours before purchasing anything non-essential
- Helps eliminate emotional spending
- You’ll often find you don’t actually need it
3. Automate $1–$5 Daily Transfers
Set a small, daily transfer from checking to savings.
- Use your bank or app to automate it
- Feels insignificant day-to-day, but adds up fast
- Great for building your emergency fund
4. Cancel One Subscription Per Month
Chances are you’re overpaying for recurring services.
- Audit your subscriptions (streaming, fitness, apps)
- Cancel at least one unnecessary subscription monthly
- Redirect that money straight into savings
5. Take the No-Spend Day Challenge
Commit to one no-spend day per week:
- No coffee runs, takeout, or Amazon splurges
- Plan ahead with packed meals and offline activities
- Save $10–$30 per week with this one habit
6. Skim Your Account Weekly
Every Sunday, transfer the excess cash from your checking account:
- Anything above your target balance goes into savings
- Builds discipline and clears mental clutter
- Ideal for flexible savers who don’t want strict rules
7. Use Cashback Apps for Everyday Spending
Leverage rewards for things you already buy.
- Try Rakuten, Ibotta, or Honey
- Combine with coupons for double savings
- Transfer cashback directly to savings monthly
8. Set Micro Goals, Not Just Big Ones
Instead of “save $5,000,” break it down:
- Weekly goals like $20 or $30
- Check-in each week to track progress
- Celebrating small wins keeps motivation high
9. Save Windfalls, Not Spend Them
Got a bonus, gift, or tax refund?
- Save at least 50–80%
- Consider opening a high-yield savings account
- Pretend you never had it = easy savings
10. Trigger-Based Saving
Create fun “if this, then save” rules:
- Every time you eat out → save $5
- Every time it rains → save $2
- Use IFTTT or app-based rules to automate it
11. Opt for Generic Brands and Bank the Difference
Next grocery run:
- Choose store brands for basics (cereal, pasta, cleaners)
- Note the difference in price
- Transfer savings manually or via budgeting app like WhizBudget
12. Cash-Only Weekends
Spend only what you withdraw in cash.
- Leaves no room for overdrafting or tapping plastic
- Makes you more mindful of every dollar
- Any unused cash = savings
13. Unsubscribe from Retail Emails
Avoid temptation altogether.
- Clean your inbox of sales triggers
- Install email filters or use unroll.me
- Fewer ads = fewer impulse buys = more savings
14. Split Paychecks into Multiple Accounts
Direct deposit part of your paycheck into savings.
- Out of sight, out of mind
- Start with just 5–10%
- Most employers or banks support split deposits
15. Create a “Treat Fund” in Your Budget
Avoid blowing your entire budget on one bad day:
- Set aside a small “fun money” stash
- Keeps emotional spending in check
- Whatever’s leftover at month-end = move to savings
Conclusion
Micro-saving isn’t about restriction, it’s about working smarter with the money you already have. When you stack these small habits together, they create a solid, low-effort saving system.
Pick 2–3 of these micro-saving hacks today and test them out this week. You’ll be surprised how quickly your savings start to grow.

The 30-Day Money Detox: Save Without Spending
A 30-day money detox is a short, structured break from non-essential spending. It isn't about suffering for a month; it's about interrupting autopilot spending, finding out what you genuinely miss, and freeing up cash for a goal. Done well, it changes your habits long after the 30 days end.
Set the Rules Before You Start
Write down three lists so there are no grey areas mid-month:
- Essentials (allowed): rent, bills, groceries from your list, transport, medicine, debt payments.
- Not allowed: takeaways, eating out, clothes, gadgets, impulse online orders, new subscriptions.
- Exceptions: anything already committed, like a birthday gift or a booked trip, with a fixed amount.
Also decide where the saved money goes: an emergency fund, a debt, or a specific goal. A named destination makes the detox much easier to stick with.
Week 1: Audit and Clear Out
- Review the last 30 days of bank and card statements and note every non-essential purchase.
- Cancel or pause subscriptions you don't use; our subscription audit takes about 30 minutes.
- Delete saved card details from shopping apps and unsubscribe from sale emails.
Week 2: Use What You Have
- Plan meals around what's already in your cupboards and freezer.
- Find free entertainment: library, parks, free events, games nights at home.
- Keep a "want list" instead of buying; review it at the end of the month.
Week 3: Handle the Cravings
Week three is usually the hardest. When you want to buy something, wait 48 hours and write down what triggered it: boredom, stress, an advert, a friend. Patterns show up quickly. If online shopping is your weak spot, our 7-day plan to stop impulse buying has more tactics.
Week 4: Review and Decide What Stays
- Add up what you saved compared with your usual month.
- Go through your want list. Most items will no longer feel necessary.
- Choose two or three habits to keep, such as fewer takeaways or no saved cards.
Make the Savings Last
The biggest risk is a spending rebound in month two. Prevent it by moving the money you saved to its goal on day 30, then setting monthly limits for the categories you cut. Small savings habits like these micro-saving hacks help the change stick.
Track the Detox
Record every purchase during the month, even essentials. Seeing your daily spending flatten is motivating, and the record shows exactly where your money normally goes. A six-month spending review afterwards shows whether the new habits held.
Frequently Asked Questions
How much can I save with a 30-day money detox?
It depends on how much of your usual spending is non-essential. Your Week 1 audit gives you a realistic estimate before you start.
What if I slip up?
Note what happened and carry on. One purchase doesn't end the detox; the goal is awareness, not perfection.

The 50/30/20 Rule: How to Save Money Without Feeling Restricted
The 50/30/20 rule is one of the simplest ways to budget: split your take-home pay into three buckets instead of tracking dozens of categories. It gives you permission to spend on things you enjoy while making sure savings happen. Here's how it works, a worked example, and how to adapt it when the numbers don't fit your life.
How the 50/30/20 Rule Works
- 50% for needs: rent or mortgage, utilities, groceries, insurance, transport to work, minimum debt payments.
- 30% for wants: eating out, hobbies, holidays, subscriptions, shopping beyond the basics.
- 20% for savings and debt payoff: emergency fund, retirement, investing, and any debt payments above the minimum.
Always use your take-home pay (after tax), not your salary.
A Worked Example
With a take-home pay of $4,000 a month:
| Bucket | Share | Monthly amount | Example uses |
|---|---|---|---|
| Needs | 50% | $2,000 | Rent $1,250, groceries $400, utilities $150, transport $120, insurance $80 |
| Wants | 30% | $1,200 | Eating out, hobbies, travel fund, subscriptions |
| Savings and debt | 20% | $800 | Emergency fund $400, retirement $300, extra debt payment $100 |
When the Split Doesn't Fit
In expensive cities or on a lower income, needs can easily take 60–70% of pay. That doesn't mean the method fails; adjust it:
- 60/20/20 if housing costs are high but you still want to protect savings.
- 50/20/30 if you're paying off high-interest debt or building an emergency fund fast.
- When money is very tight, a bare-bones budget is a better first step.
The percentages are a starting point. The real value is deciding the split in advance, so savings aren't just whatever is left over.
How to Set It Up
- Add up your monthly take-home pay.
- Multiply by 0.5, 0.3 and 0.2 to get your three limits.
- Look at last month's spending and sort each item into needs, wants or savings.
- Automate the 20% on payday so it happens first.
- Check the three totals once a week.
In WhizBudget you can create categories for each bucket, set a monthly budget per category and see at a glance how much is left; our getting started guide walks through it.
50/30/20 vs Other Budgeting Methods
If you want more control over every dollar, zero-based budgeting assigns each dollar a job. If irregular bills keep breaking your budget, add sinking funds inside the savings bucket. Many people start with 50/30/20 and add detail later.
Frequently Asked Questions
Do debt payments count as needs or savings?
Minimum payments are needs. Anything you pay above the minimum counts toward the 20%.
Is 20% savings realistic?
Not for everyone at first. Start with what you can, even 5%, and raise it each time your income grows or a debt is paid off.

Automate Your Savings and Build Wealth Effortlessly
Saving money can feel like a challenge, especially when life’s expenses keep piling up. However, by automating your savings, you can make wealth-building an effortless habit rather than a daunting task. In this guide, we’ll walk you through simple yet effective ways to automate your savings and set yourself up for long-term financial success.
Why Automate Your Savings?
Automation takes the guesswork out of saving. Instead of relying on willpower to set money aside, automation ensures you consistently save without having to think about it. This approach provides consistency, helps you avoid temptation, reduces stress, and capitalizes on compound interest. Regular contributions add up over time, making it easier to build wealth effortlessly. Since the money is saved before you have a chance to spend it impulsively, you are more likely to stay on track. Additionally, automating savings eliminates the stress of remembering to set money aside manually, and the earlier you start, the more you benefit from compound growth.
Steps to Automate Your Savings
Setting up direct deposits into a savings account is one of the easiest ways to start automating your savings. Many employers allow you to split your direct deposit between multiple accounts, making it simple to allocate a fixed percentage for savings before you even see the money. If your employer doesn’t offer paycheck splitting, you can set up automatic transfers from your checking account to your savings account. Most banks allow you to schedule recurring transfers weekly, bi-weekly, or monthly, ensuring that saving becomes a regular habit.
Using a high-yield savings account can help maximize your savings since these accounts offer higher interest rates than traditional savings accounts, allowing your money to grow faster over time. Another strategy is automating retirement contributions. If your employer offers a 401(k), setting up automatic deductions from your paycheck can be beneficial, especially if there is a company match. For those without a 401(k), setting up automatic monthly contributions to a Roth or Traditional IRA can help grow retirement savings effortlessly.
Round-up savings apps such as Acorns, Qapital, and Digit are also helpful tools for automating savings. These apps round up your purchases to the nearest dollar and save the spare change for you. Over time, these small savings add up significantly. Additionally, using a robo-advisor or automated investment platform can help grow your wealth. These services automatically invest your money based on your financial goals and risk tolerance, helping you build long-term wealth passively.
While not directly related to saving, automating bill payments can ensure you never miss a due date. This prevents late fees and protects your credit score, which can save you money on interest rates in the future.
Automating your savings is one of the simplest yet most effective ways to build wealth without extra effort. By setting up direct deposits, automatic transfers, and utilizing savings and investment apps, you can ensure consistent financial growth. Start small if needed, but take action today, your future self will thank you!
Trending Topics


Recent Posts
How to Build an Emergency Fund: Step-by-Step Guide
Jul 01, 2026
The 30-Day Money Detox: Save Without Spending
Apr 05, 2025