Investing for Beginners
Simple ways to start investing
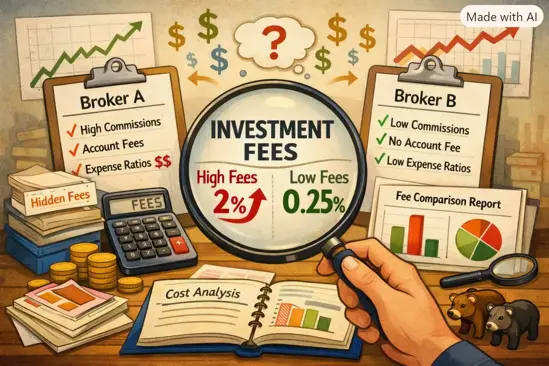
How to Compare Investment Fees Before Opening a Brokerage Account
Investment fees can look small on a price list, but they reduce your returns every year. A €3 trading charge or a 0.70% annual fund fee may not feel urgent when you are starting out. Over a decade or more, however, recurring costs can take a meaningful share of your investment growth.
Learning how to compare investment fees before opening an account helps you choose an arrangement that fits how often you invest, what you want to buy and how much support you need. The goal is not always to find the lowest advertised price. It is to understand the full cost of investing, including charges that may be easy to overlook.
Why Investment Fees Matter More Than Beginners Expect
Fees are paid from money that could otherwise stay invested and potentially grow. This makes them especially important for long-term investors. A one-off charge hurts once; an annual percentage fee can affect every future year because it also reduces the amount available to compound.
For example, assume you invest €10,000 for 20 years and earn 6% a year before fees. With a 0.20% annual cost, the investment could grow to about €30,680. With a 1.20% annual cost, it could grow to about €25,530. The 1% difference in annual fees costs roughly €5,150 in this simplified example.
Actual returns are never guaranteed, and taxes, inflation and market movements also matter. Still, costs are one of the few factors investors can review in advance. Lower beginner investing costs can leave more of your money working toward your goals.
The Main Types of Investing Fees to Check
Brokerage account fees vary by provider, account type, country and investment product. Read the provider’s official fee schedule and, for funds, the prospectus or key information document (KID). Focus on these common charges:
- Account or custody fee: A monthly or annual charge for holding an account or securities. It may be a flat euro amount or a percentage of your portfolio.
- Trading commission: A fee charged when you buy or sell shares, ETFs, bonds or funds. It can be fixed, percentage-based or both.
- Fund transaction fee: A dealing charge for buying certain mutual funds or ETFs, sometimes separate from the fund’s annual costs.
- Expense ratio or ongoing charge: The annual operating cost built into a fund’s performance. This is not normally billed as a separate invoice.
- Advisory or management fee: A percentage paid for a managed portfolio, robo-advice service or financial advice.
- Foreign exchange (FX) fee: A charge for converting euros into another currency to buy assets listed in pounds, dollars or other currencies.
- Transfer-out or account closure fee: A fee to move your holdings or cash to another broker.
- Inactivity, paper statement or corporate action fees: Less common charges that can still affect small accounts.
Also look for bid-ask spreads. The spread is the difference between the current buying and selling price of a security. It is not always listed as a broker fee, but it is a real transaction cost, particularly for less liquid shares and funds.
How to Compare Brokerage Account Fees Side by Side
Do not compare brokers using one headline such as “zero commission.” Instead, compare costs based on your likely behaviour. Someone investing €200 each month into one euro-denominated ETF needs a different price structure than someone making occasional share purchases in US dollars.
- Write down your expected activity. Estimate how much you will invest monthly, how many trades you may place each year, which markets you will use and whether you want a self-directed or managed account.
- Collect the official documents. Download each provider’s pricing page, full fee schedule and terms. Check the date, as prices can change.
- Calculate first-year euro costs. Add expected account fees, trade charges, FX charges and product costs. Include a realistic estimate rather than assuming ideal conditions.
- Check ongoing annual costs. Account maintenance, fund expense ratios and advisory fees can matter more than a one-time opening promotion.
- Review exit costs and service limits. Check transfer fees, minimum balances, fractional-share availability, tax documents, market access and customer support.
| Cost to compare | Question to ask | Where to find it |
|---|---|---|
| Account fee | Is there a monthly, annual or custody charge? | Broker fee schedule |
| Trade commission | What will each purchase and sale cost? | Trading price list |
| FX conversion | Will I pay to buy assets in another currency? | Currency conversion terms |
| Fund expense ratio | What percentage is deducted within the fund each year? | KID, prospectus or fund factsheet |
| Transfer-out fee | What does it cost to leave later? | Transfer and closure fee section |
A simple spreadsheet is enough for this exercise. You can also use a free budget app such as WhizBudget to set aside a regular investing amount and make sure fees fit comfortably within your wider financial plan.
How Expense Ratios Affect Fund Returns
Expense ratios explained simply: they are the annual costs of running an investment fund, expressed as a percentage of the money invested. They can cover administration, management, legal and operating expenses. The fee is generally reflected in the fund’s daily value, so you may not see a separate deduction in your brokerage account.
Suppose you invest €5,000 in two broadly similar funds. Fund A has a 0.15% expense ratio and Fund B has a 0.85% expense ratio. If both earn the same gross return, Fund A leaves more return in your account each year. On €5,000, the difference is €35 in the first year. As the investment and contributions grow, the euro difference can grow too.
Compare funds with similar objectives before focusing on cost alone. A global equity UCITS ETF, an actively managed European equity fund and a short-term bond fund do different jobs. Look at the benchmark, holdings, risk level, distribution policy and tracking approach alongside the ongoing charge.
How to Spot Hidden or Easy-to-Miss Charges
Hidden investing fees are not always deliberately concealed. Often, they are simply placed in detailed documents or only apply in certain situations. These are the charges beginners most often miss:
- Currency conversion mark-ups: A low or zero trade commission may be offset by an FX percentage each time you buy or sell a foreign-currency asset.
- Payment or withdrawal charges: Some platforms charge for card deposits, international bank transfers or particular withdrawal methods.
- ETF and fund spreads: Check whether a fund is thinly traded, as a wider spread raises the effective cost of entering and leaving.
- Securities lending arrangements: Some funds lend holdings to earn income. Review how revenue and risk are handled in the fund documents.
- Managed portfolio layers: A managed service may charge its own fee while the underlying funds also have expense ratios.
- Tax-related service fees: In some European countries, brokers charge for tax reporting, reclaiming withholding tax or issuing special statements.
Commission-free investing means the broker may not charge a stated commission on eligible trades. It does not mean the investment has no cost. Fund charges, spreads, FX fees and account fees can still apply. Always check which products qualify and whether there are minimum order sizes or other conditions.
A Simple Fee Comparison Checklist for New Investors
Use this checklist before submitting an account application:
- Read the complete brokerage account fees schedule, not only the marketing page.
- Estimate the annual cost based on your planned deposits and number of trades.
- Check the fund’s KID or prospectus for its ongoing charge and risks.
- Confirm whether your preferred investments trade in euros or require currency conversion.
- Look for custody, inactivity, withdrawal and transfer-out fees.
- Check whether advisory fees are charged in addition to underlying investment costs.
- Save copies of the fee documents and review them at least once a year.
If the information is unclear, ask the provider for written clarification before funding the account. A transparent provider should make its charges understandable.
Example: Comparing the Long-Term Cost of Two Investment Accounts
Imagine an investor contributes €250 a month for 15 years, or €45,000 in total. For illustration, assume investments return 6% a year before all fees.
| Account A | Account B | |
|---|---|---|
| Annual account fee | €0 | 0.30% of portfolio value |
| Monthly trade cost | €2 | €0 |
| Fund expense ratio | 0.20% | 0.70% |
| Estimated annual total cost | About 0.20% plus €24 trades | About 1.00% |
| Estimated value after 15 years | About €71,000 | About €67,000 |
These figures are rounded illustrations, not projections. Account A has trading costs, while Account B has free trades but higher recurring percentage fees. For a monthly investor, the lower ongoing cost could outweigh the fixed commissions over time. But the result could reverse for a person making many small trades or using different products. This is why a personalised comparison matters.
When a Higher Fee May Be Worth Paying
Cheapest is not automatically best. A higher fee may be reasonable when it provides value you will actually use, such as regulated advice, tax support relevant to your country, access to a needed investment, strong security features or a service that helps you stay disciplined.
For example, paying for advice could be useful if you have a complex cross-border tax position, an inheritance or major decisions around retirement. The key is to identify exactly what you receive, how the fee is calculated and whether less expensive options meet the same need. Avoid paying more simply because a price structure is difficult to understand.
WhizBudget can help you track your monthly cash flow before increasing investment contributions, so you can build a plan that leaves room for an emergency fund and essential expenses.
FAQs About Investment Fees for Beginners
Are commission-free trades really free?
No. Commission-free trades can remove a dealing commission, but you may still pay fund expense ratios, FX fees, spreads, account charges or other costs. Review the full fee schedule.
What is a good expense ratio for a beginner?
There is no single right number. Compare the expense ratio with funds that have the same investment objective, region, risk level and strategy. Broad index funds often have lower costs than specialist or actively managed funds, but suitability matters too.
Do I pay expense ratios separately?
Usually not. A fund’s ongoing charges are generally reflected in its net asset value and returns. You still pay them economically, even though they may not appear as a separate cash transaction.
Should I avoid brokers that charge an account fee?
Not necessarily. A broker with an account fee may still be cheaper overall if it offers low trading, FX or product costs that suit your plan. Calculate your expected total annual cost.
What fees matter most for monthly investors?
For regular investors, recurring fund costs, custody fees and per-trade charges often matter most. A fixed commission can be particularly expensive when each monthly contribution is small.
Can I transfer my investments if fees rise?
Often yes, but transfer rules and costs vary. Check whether in-specie transfers are available, whether cash transfers require selling investments and what transfer-out fees apply before opening the account.
Conclusion: Compare Costs Before You Commit
Before choosing a brokerage, compare the full picture: account charges, trading costs, FX fees, expense ratios, advisory charges, spreads and exit fees. Use realistic assumptions based on how you plan to invest, then revisit the numbers as your portfolio grows. A few minutes spent reviewing official documents can prevent expensive surprises later.
Start by putting your investing amount into a clear monthly plan. Use WhizBudget, the free budget app, to see what you can invest consistently, then use this fee checklist to compare accounts with confidence.
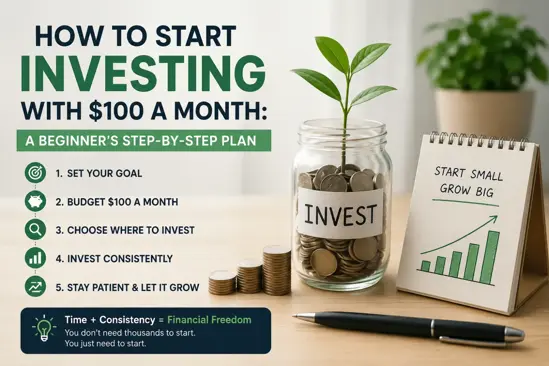
How to Start Investing With $100 a Month: A Beginner’s Step-by-Step Plan
If you have ever thought, I would invest if I had more money, you are not alone. Many beginners across Europe assume investing is only for people with large salaries, property, or thousands of euros sitting in the bank. The good news is that you can start investing with $100 a month, or roughly a similar amount in euros, and build a serious habit over time.
This guide is designed for people who are new to investing, want practical steps, and do not want complicated jargon. You will learn how to check your financial basics, choose an investment account, pick beginner-friendly investments, automate your contributions, and avoid common mistakes. We will also look at what $100 a month could become over the long term, using realistic assumptions rather than guaranteed promises.
Investing with little money is not about getting rich quickly. It is about building consistency, giving your money time to grow, and learning how markets work while the stakes are manageable.
Why $100 a Month Is Enough to Start Investing
$100 a month may not sound like much, especially when housing, energy, food, and transport costs are high. But investing is not only about the amount you start with. It is also about time, consistency, and the power of compounding.
Compounding means your investments can earn returns, and then those returns may earn returns in the future. Over years and decades, this can make small monthly contributions more powerful than they first appear.
Starting with $100 a month can help you:
- Build the habit of paying your future self first.
- Learn how investing works without risking large sums.
- Benefit from long-term market growth.
- Avoid waiting for the perfect moment, which often never comes.
- Create a monthly investing plan that can grow with your income.
For many beginners, the biggest obstacle is not money. It is confidence. Once you understand the basics and start small, investing becomes less intimidating.
Step 1: Make Sure Your Financial Basics Are Covered First
Before you invest, make sure your financial foundation is stable. Investing involves risk, and the value of your investments can go down as well as up. You do not want to sell investments at a bad time because you need cash for rent, an emergency bill, or credit card payments.
Start with these basics:
- Track your income and spending. Know exactly how much comes in and where it goes each month.
- Build a small emergency fund. Aim for at least one month of essential expenses first, then work toward three to six months over time.
- Deal with expensive debt. If you have high-interest credit card debt or payday loans, paying them down should usually come before investing.
- Cover your essentials. Rent or mortgage, bills, food, insurance, transport, and minimum debt payments should be secure before you invest.
A simple budgeting tool can make this step much easier. WhizBudget can help you see whether $100 a month is realistic, where you can reduce spending, and how to create a dedicated investing category in your budget.
If $100 feels too much right now, start with $25 or $50. The habit matters. You can increase later when your finances improve.
Step 2: Choose the Right Investment Account
To start investing for beginners, the first practical step is choosing where your investments will live. The best account depends on your country, tax rules, goals, and time horizon. In Europe, account types vary, but the basic idea is usually similar: you open an account with a bank, investment platform, pension provider, or broker.
Here are common options to consider:
| Account type | Best for | Beginner notes |
|---|---|---|
| General investment account | Flexible investing with no specific tax wrapper | Easy to open, but taxes may apply to dividends, capital gains, or both depending on your country. |
| Tax-efficient investment account | Long-term investing with potential tax benefits | Examples include ISAs in the UK or country-specific investment savings accounts. Rules differ across Europe. |
| Pension account | Retirement investing | May offer tax advantages, but access is usually restricted until later life. |
| Robo-adviser account | Hands-off investing | You answer questions and the platform builds a portfolio for you, usually for an extra fee. |
| Employer pension scheme | Workplace retirement saving | If your employer matches contributions, this can be one of the best investments for beginners. |
When comparing platforms, pay close attention to fees. With a small monthly amount, high fixed fees can eat into your returns. Look for:
- Low or no monthly account fees.
- Low trading fees, especially if you invest monthly.
- Access to low-cost index funds or ETFs.
- Automatic investing options.
- Clear tax documents and local regulatory protection.
Always choose a regulated provider in your country or region. For example, look for oversight by a recognised financial authority, such as the FCA in the UK, BaFin in Germany, AMF in France, or your local regulator.
Step 3: Pick Beginner-Friendly Investments
Once your account is open, you need to decide what to invest in. This is where many beginners get overwhelmed. The financial world is full of individual shares, bonds, funds, crypto assets, commodities, and complex products. You do not need most of them when you are starting out.
For beginners investing with little money, broad, low-cost funds are often a sensible place to begin. Two common choices are index funds and ETFs.
What is an index fund?
An index fund is a fund that tries to track a market index. For example, a global stock market index fund may hold shares in thousands of companies across different countries and sectors. Instead of trying to pick the next winning company, you buy a small piece of the wider market.
What is an ETF?
An ETF, or exchange-traded fund, is similar to a fund but trades on an exchange like a share. Many ETFs track indexes. They are popular because they are widely available, transparent, and often low-cost.
Beginner-friendly investment options may include:
- Global equity index funds or ETFs: diversified exposure to companies around the world.
- Bond funds or ETFs: lower-risk assets that can help reduce portfolio swings, though they still carry risk.
- Multi-asset funds: a ready-made mix of shares and bonds in one fund.
- Target-date or retirement funds: funds that adjust their mix over time as you approach a future date.
A simple beginner portfolio might be one global stock market ETF, or a multi-asset fund with a mix of shares and bonds. You do not need 20 different investments to be diversified. In fact, too many holdings can make your portfolio harder to understand.
Risk matters. Shares can fall sharply in the short term. If you need the money within the next three to five years, investing it in the stock market may not be appropriate. For short-term goals, a savings account or cash deposit may be safer.
Step 4: Set Up Automatic Monthly Contributions
The easiest way to stick with a monthly investing plan is to automate it. Automation removes the need to make a decision every month. You set it up once, and your money is invested according to your chosen schedule.
Here is a simple setup:
- Choose a monthly contribution amount, such as $100 or the euro equivalent.
- Schedule the transfer shortly after payday.
- Set a recurring investment into your chosen fund or ETF if your platform allows it.
- Review your budget monthly, but avoid checking your investments every day.
Payday automation works because it treats investing as a priority, not an afterthought. If you wait until the end of the month, the money often disappears into food delivery, subscriptions, impulse purchases, or general spending.
You can use WhizBudget to create a monthly investing category and track whether your automated contribution fits comfortably with your bills and savings goals.
Step 5: Use Dollar-Cost Averaging to Reduce Timing Risk
Dollar cost averaging for beginners is a simple concept: instead of investing a large lump sum all at once, you invest a fixed amount regularly, such as $100 every month.
When prices are high, your $100 buys fewer fund units. When prices are low, your $100 buys more units. Over time, this can reduce the stress of trying to guess the perfect time to invest.
Dollar-cost averaging does not guarantee profits or protect you from losses. Markets can still fall. But it helps beginners build discipline and avoid emotional decision-making.
For example:
| Month | Investment amount | Fund price | Units bought |
|---|---|---|---|
| January | $100 | $20 | 5.00 |
| February | $100 | $25 | 4.00 |
| March | $100 | $10 | 10.00 |
| April | $100 | $20 | 5.00 |
In this example, you invested the same amount each month, but you bought more units when the price fell. This is one reason monthly investing can be emotionally easier for beginners.
Step 6: Avoid Common Beginner Investing Mistakes
Learning how to start investing with $100 a month also means learning what not to do. Most beginner mistakes come from impatience, overconfidence, or lack of planning.
Avoid these common errors:
- Waiting too long to start. You do not need to know everything before investing a small amount in a diversified fund.
- Investing money you need soon. Short-term money should usually stay in cash or safer savings products.
- Chasing hot tips. Social media trends, meme stocks, and crypto hype can lead to poor decisions.
- Ignoring fees. A fund charging 1.5% per year can cost far more over time than one charging 0.2%.
- Checking your account daily. Market movements are normal. Daily checking can encourage panic selling.
- Selling during every downturn. Losses only become locked in when you sell. Long-term investors need patience.
- Putting everything into one company. Diversification helps reduce the risk of one bad investment damaging your whole portfolio.
The goal is not to make perfect decisions. The goal is to make sensible decisions repeatedly.
Example $100 Monthly Investment Plan
Here is a simple example of how a beginner might structure a $100 monthly investment plan. This is not personal financial advice, but it shows how you can think about your options.
| Investor profile | Possible monthly split | Why it may work |
|---|---|---|
| Young long-term investor | $100 into a global equity index ETF | Higher risk, but suitable for someone with decades before needing the money. |
| Balanced beginner | $80 global equity fund, $20 bond fund | Still growth-focused, but with some stabilising assets. |
| Cautious beginner | $60 multi-asset fund, $40 cash savings | Useful if the person is still building confidence or has a shorter time horizon. |
| Retirement-focused employee | $100 into workplace pension or personal pension | May benefit from employer contributions or tax advantages. |
If you are unsure, a broad multi-asset fund or robo-adviser can be a simple starting point. The key is understanding what you own, how much it costs, and what level of risk you are taking.
You should also keep your investing plan separate from your emergency fund. Your emergency fund is for stability. Your investments are for long-term growth.
How Much $100 a Month Could Grow Over Time
Future returns are never guaranteed. Markets can perform better or worse than expected, and inflation reduces the future buying power of money. Still, examples can help show why consistency matters.
The table below shows how $100 a month might grow over time at different average annual returns, before taxes and fees. These are illustrations only.
| Time invested | Total contributed | At 3% annual return | At 5% annual return | At 7% annual return |
|---|---|---|---|---|
| 5 years | $6,000 | About $6,460 | About $6,800 | About $7,160 |
| 10 years | $12,000 | About $13,970 | About $15,530 | About $17,310 |
| 20 years | $24,000 | About $32,830 | About $41,100 | About $52,400 |
| 30 years | $36,000 | About $58,270 | About $83,570 | About $122,710 |
The lesson is clear: time does much of the heavy lifting. Even if you start small, regular contributions can become meaningful over decades.
Also remember that real returns are affected by platform fees, fund charges, taxes, currency movements, and inflation. This is why low-cost investing and tax-efficient accounts can make a significant difference.
When to Increase Your Monthly Investment Amount
Starting with $100 a month is a strong first step, but it does not have to stay there forever. As your income grows or your expenses fall, you can increase your monthly investing amount gradually.
Good times to increase contributions include:
- After a pay rise.
- When you finish paying off a loan.
- After cancelling unused subscriptions.
- When your emergency fund reaches its target.
- After receiving a bonus, tax refund, or freelance payment.
- When your rent or bills decrease.
A useful approach is to increase your contribution by a small percentage each year. For example, if you invest $100 a month this year, you might raise it to $125 next year and $150 the year after. Small increases are easier to maintain than dramatic changes.
You can also split extra money between different goals. For example, if you free up $200 a month, you might invest $100, add $50 to your emergency fund, and use $50 for travel or personal spending. Sustainable plans are more likely to last.
FAQs
1. Is $100 a month really enough to start investing?
Yes. $100 a month is enough to build the habit, learn the process, and benefit from long-term compounding. It may not make you wealthy overnight, but it can grow meaningfully over time if invested consistently.
2. What are the best investments for beginners with little money?
Many beginners start with low-cost index funds, ETFs, multi-asset funds, or workplace pension funds. These options can provide diversification without requiring you to pick individual stocks.
3. Should I invest if I have debt?
It depends on the debt. High-interest debt, such as credit cards or payday loans, should usually be prioritised before investing. Lower-interest debt, such as some student loans or mortgages, may allow room for investing, depending on your budget and risk tolerance.
4. Can I lose money by investing $100 a month?
Yes. All investing involves risk. Your investments can fall in value, especially in the short term. This is why it is important to invest money you do not need soon and to diversify.
5. How do I choose between an ETF and an index fund?
Both can be good choices. ETFs trade like shares and are widely available on brokerage platforms. Index funds may be easier for automatic monthly investing on some platforms. Compare fees, availability, minimum investment amounts, and how simple each option is to manage.
6. How long should I invest for?
Investing is usually best for medium- to long-term goals. A time horizon of at least five years is commonly suggested for stock market investing, and ten years or more is better for reducing the impact of short-term market swings.
7. Do I need a financial adviser to start investing with $100 a month?
Not always. Many beginners can start with simple, diversified, low-cost funds after learning the basics. However, if you have complex finances, tax questions, inheritance issues, or major retirement decisions, professional advice may be useful.
Conclusion
You do not need to be rich to become an investor. You need a clear plan, a suitable account, beginner-friendly investments, and the discipline to contribute regularly. Starting with $100 a month can help you build confidence, learn good habits, and give your money time to work for your future.
Begin by checking your budget, building a small emergency fund, and choosing a regulated investment platform with low fees. Then select a simple diversified investment, automate your monthly contribution, and avoid reacting emotionally to normal market movements.
If you want help finding room in your budget for your first monthly investment, WhizBudget can help you track spending, plan your savings, and create a realistic investing habit that fits your life. Start small, stay consistent, and let your future self benefit from the decision you make today.
What Should You Invest In? A Simple Beginner Framework (No Overthinking Needed)
Everyone Says “Start Investing”… But In What?
That’s the part nobody explains properly.
You hear:
- “Invest in stocks”
- "Buy ETFs"
- “Think long-term”
Cool. But that doesn’t help when you’re staring at your screen thinking:
“What do I actually put my money into?"
Let’s fix that.
No fluff. No complicated strategies.
Just a simple way to decide.
Step 1: Your Timeline Decides Everything
Before you invest a single dollar, answer this:
When do you need this money?
- 0–3 years → Short-term
- 3–10 years → Medium-term
- 10+ years → Long-term
That’s it. That one answer changes everything.
Because:
- Short-term = don’t risk it. Before investing, make sure you’ve got a basic safety net in place - here’s how much you should actually save.
- Long-term = let it grow
Most beginners mess this up. They invest long-term money like it’s short-term… then panic when it drops. And this is one of the most common investing mistakes beginners make.
Step 2: Match Your Money to the Right Type of Investment
Now let’s keep it simple.
Short-Term (0–3 years)
Goal: Don’t lose money
- Savings accounts
- Money market funds
- Short-term bonds
This is NOT where you chase returns.
This is where you protect your money.
Medium-Term (3–10 years)
Goal: Balance
- Bond ETFs
- Dividend stocks
- Mixed portfolios
Think: house deposit, business idea, life plans.
Long-Term (10+ years)
Goal: Growth
- Index funds
- ETFs
This is where real wealth happens.
Not fast. Not exciting. But effective.
Step 3: Stop Trying to Build the “Perfect Portfolio”
You don’t need:
- 10 ETFs
- 15 stocks
- daily market updates
You need something you can stick to.
A simple setup beats a “perfect” one you abandon.
Example:
- One global ETF
- Maybe one bond fund
Done.
Step 4: The Sleep Test (Most Important Rule)
Ask yourself:
“If this drops 20%, will I panic?”
If yes:
- You’re risking too much
- Or you don’t understand what you bought
Both are problems.
Good investing should feel boring, not stressful.
Step 5: Make It Automatic (Or You Won’t Stick With It)
Here’s the truth:
Investing isn’t about one smart move.
It’s about repeating a simple one.
Set this up:
- Invest monthly
- Automate it
- Don’t touch it
That’s how consistency beats timing.
If you’re thinking, “I don’t have enough to start” you can literally begin small - here’s how to start investing with just $100.
Step 6: If Your Budget Is Messy, Investing Won’t Work
Let’s be real.
You can’t invest consistently if:
- You don’t know where your money goes
- You overspend every month
- You’re constantly “starting over”
Investing only works when your basics are handled.
Budget first. Invest second.
A Simple Beginner Setup (If You’re Overthinking)
If you just want something easy:
- 80% → Global index fund
- 20% → Bonds (optional)
That’s more than enough to get started.
You don’t need anything fancy.
Final Thought: The Real Risk Isn’t Picking Wrong
It’s doing nothing.
Waiting.
Overthinking.
Researching forever.
Meanwhile, time (your biggest advantage) is slipping away.
Start simple.
Adjust later.
But start.

5 Common Investing Mistakes and How to Avoid Them
“Am I too late to start investing?”
“What if I lose all my money?”
“Should I buy crypto, or is that just hype?”
If you've ever asked these, you're not alone.
Investing can feel like walking into a party where everyone knows the rules, except you.
And when money’s on the line, guessing wrong gets expensive real fast.
Let’s fix that.
Here are 5 common investing mistakes that trip people up, and how to dodge them like a pro.
1. Trying to Time the Market (Biggest Trap)
Most folks try to “buy low and sell high.”
Sounds smart, right?
Wrong.
It’s a gamble.
Even pros mess this up.
Nobody, nobody, knows what the market’s doing tomorrow.
Example:
Uncle Joe pulls out of stock when things dip.
Then he buys back in after prices go up.
Now he’s lost twice.
How to avoid it:
- Invest regularly (aka “dollar-cost averaging”).
- Don’t panic when the market drops.
- Think long-term, like years, not days.
2. Going All-In on One Thing
Putting everything into one stock or just crypto?
That’s like betting your house on one horse.
Real Talk:
Even companies that look bulletproof can flop. (Looking at you, Blockbuster.)
How to avoid it:
- Diversify. Spread your money around.
- Mix it up: stocks, index funds, bonds.
- Don’t chase shiny things just because they’re trending.
3. Investing Without a Plan
Randomly throwing money into the market isn’t investing.
It’s guessing.
Story time:
I once met a guy who “invested” by buying whatever his cousin told him was “hot.”
His portfolio? A dumpster fire.
How to avoid it:
- Set goals (retirement, house, freedom from your 9-to-5).
- Pick investments that match those goals.
- Check in every month to tweak things.
4. Ignoring Fees and Taxes
Most people don’t think about the small stuff.
But it’s not small when it’s eating your profits.
Example:
You make $1,000 on an investment.
A 2% fee? That’s $20 gone.
Do that over the years, and it's thousands down the drain.
How to avoid it:
- Watch out for high-fee funds and advisors.
- Use tax-efficient accounts (like Roth IRAs).
- Look at the fine print before clicking “buy.”
5. Letting Emotions Drive the Bus
Fear and greed are terrible investors.
They make you buy high and sell low.
We’ve all been there:
Market drops → “I should pull out.”
Market rises → “I need to buy more!”
That’s emotional investing.
It’s like drunk driving with your money.
How to avoid it:
- Zoom out. What matters is the long game.
- Set rules. Follow them—no matter how you feel.
- Check your money less. Yes, really.

Where to Invest Money to Get Good Returns – A Beginner’s Guide
Disclaimer: This is not financial advice, just my personal opinion and experience. Always do your own research before making any investment decisions.
If you're new to investing, you're probably wondering, Where should I put my money to get good returns? I’ve been there too, and I know how overwhelming it can feel with so many options. The good news is, you don’t need to be a financial guru to start investing wisely. In this post, I'll share my thoughts on some beginner-friendly investment options that can help you grow your wealth over time.
1. High-Interest Savings Accounts & Fixed Deposits (For Safety & Liquidity)
If you’re just getting started, having an emergency fund is crucial. A high-interest savings account or a fixed deposit (FD) is a great place to park some money while you explore other investment opportunities. The returns aren’t sky-high, but they provide safety and liquidity, ensuring you have cash available when needed.
2. Index Funds & ETFs (For Simplicity & Steady Growth)
One of the easiest ways to start investing is through index funds or exchange-traded funds (ETFs). These funds track a market index like the S&P 500 and offer a diversified portfolio with lower risks than individual stocks.
Why I like them: They require minimal effort, have low fees, and historically provide good long-term returns (around 7-10% annually).
Best for: Beginners who want a hands-off approach.
3. Stocks (For Higher Growth Potential)
If you're willing to take on more risk, individual stocks can be a great option. Start with well-established companies (often called "blue-chip stocks") like Apple, Microsoft, or Tesla.
My tip: Invest in companies you understand and believe in. Avoid chasing trends or hype.
Best for: Those willing to do some research and hold for the long term.
4. Real Estate Investment Trusts (REITs) (For Passive Real Estate Income)
Want to invest in real estate without buying property? REITs allow you to do just that. These companies own income-generating real estate, and you can invest in them just like stocks.
Why REITs? They provide regular dividends and have the potential for long-term appreciation.
Best for: Investors looking for passive income with moderate risk.
5. Bonds (For Stability & Fixed Income)
Bonds are essentially loans you give to governments or corporations in exchange for periodic interest payments. They are lower-risk than stocks and can be a great way to balance your portfolio.
Best for: Conservative investors looking for stability and predictable returns.
6. Cryptocurrency (For High Risk, High Reward)
Crypto is one of the most talked-about investments today. While it has the potential for massive returns, it is also highly volatile. Bitcoin and Ethereum are the most established options.
My take: Only invest what you can afford to lose, and don’t put all your eggs in one basket.
Best for: Those who are comfortable with high risk and volatility.
7. Investing in Yourself (The Best Long-Term Investment)
One of the smartest investments you can make is in yourself. Learning new skills, taking online courses, or even starting a side hustle can generate returns that last a lifetime.
Best for: Everyone!
Final Thoughts
As a beginner, the key is to start small, diversify, and stay patient. No investment is risk-free, but with the right strategy and mindset, you can grow your wealth over time.

The Power of Compound Interest: Why Starting Early Matters
Compound interest is one of the most powerful financial tools available, and the sooner you take advantage of it, the more you can benefit. Unlike simple interest, which only earns returns on the original amount, compound interest allows your money to grow exponentially by earning interest on both the principal and the accumulated interest over time.
Starting early is key to maximizing compound interest. Even small, consistent contributions can lead to significant growth over the years. The longer your money stays invested, the more time it has to compound, turning modest savings into substantial wealth.
Consider this example: If you invest $100 per month starting at age 20 with an average annual return of 7%, by age 60, you could have over $240,000. If you start the same investment at age 30, the total drops to about $120,000, half as much, despite investing for only 10 fewer years.
Compound interest works best when paired with smart financial habits. Contribute regularly to savings or investment accounts, reinvest earnings, and avoid unnecessary withdrawals. Even small increases in contributions or returns can make a big difference over time.
The power of compounding is a reminder that time is your greatest asset when it comes to growing wealth. Whether saving for retirement, a home, or financial security, the earlier you start, the better your financial future will be.

Stocks, Bonds, and ETFs: What Every New Investor Should Know
Investing can be overwhelming for beginners, but understanding the basics of stocks, bonds, and ETFs is a great place to start. These three investment types offer different risk levels, returns, and benefits. Let’s break them down.
Stocks: Ownership in a Company
Stocks represent ownership in a company. When you buy a stock, you own a small piece of that company and can benefit if its value grows.
Why Invest in Stocks?
Potential for high returns over time.
Some stocks pay dividends, providing passive income.
You can invest in individual companies or diversify with multiple stocks.
Risks: Stocks can be volatile, meaning prices can fluctuate significantly in the short term. Long-term holding and diversification can help manage risk.
Bonds: A More Stable Option
Bonds are essentially loans you give to companies or governments in exchange for regular interest payments and the return of your principal at maturity.
Why Invest in Bonds?
More stable and predictable than stocks.
Provide regular interest payments.
Lower risk compared to stocks, making them a good option for conservative investors.
Risks: Bonds generally have lower returns than stocks. If interest rates rise, bond prices may fall. Corporate bonds also carry the risk of the issuer defaulting.
ETFs: A Mix of Stocks and Bonds
Exchange-Traded Funds (ETFs) are a basket of investments, such as stocks or bonds, bundled together and traded on an exchange like a stock.
Why Invest in ETFs?
Offer instant diversification with lower costs.
Can track market indexes, industries, or specific investment strategies.
Lower risk compared to buying individual stocks.
Risks: ETF performance depends on the underlying assets. Market fluctuations can still affect returns, but diversification helps reduce risk.
Which One is Right for You?
If you want high growth potential → Consider stocks.
If you prefer stable, predictable income → Bonds might be better.
If you want diversification and balance → ETFs offer a mix of both.
For new investors, a combination of stocks, bonds, and ETFs can help create a balanced portfolio that matches your risk tolerance and financial goals. Start small, stay consistent, and focus on long-term growth!

How to Start Investing with Just $100
Investing often sounds like something only wealthy people do, but the truth is, you don’t need a fortune to get started. Even with just $100, you can take the first step toward building wealth, and the sooner you start, the better. Here’s how to make that small investment work for you.
1. Open a Brokerage Account Many online brokers allow you to open an account with no minimum deposit. Look for a platform with low fees, a simple interface, and fractional shares, this lets you invest in big companies with just a few dollars.
2. Consider Fractional Shares If you’ve got your eye on a company whose stock price is sky-high, fractional shares allow you to buy a piece of that stock instead of waiting until you have enough for a full share. This is a game-changer for small investors.
3. Invest in Index Funds or ETFs A great way to diversify right away is by putting your $100 into an index fund or exchange-traded fund (ETF). These funds spread your money across multiple companies, reducing risk while still offering solid returns over time.
4. Use a Micro-Investing App Apps like Acorns or Stash make investing automatic and effortless. You can start with just a few dollars, and many of these apps offer round-up features that invest your spare change.
5. Focus on Consistency The most important habit in investing isn’t how much you start with, it’s how regularly you contribute. Set up an automatic transfer to add a little to your investments each month, and you’ll be surprised how quickly it grows.
6. Reinvest Your Earnings Whether it’s dividends from stocks or returns from a fund, reinvesting your earnings accelerates growth thanks to the power of compound interest.
7. Keep Learning Investing $100 might feel small now, but it’s the beginning of a journey. As you see your money grow, you’ll build confidence, learn more about the market, and be motivated to invest more.
Starting small is better than not starting at all. That $100 could be the seed that grows into financial freedom, all it takes is a little patience, consistency, and smart choices.

Investing 101: A Beginner’s Guide to Growing Your Wealth
If you’ve ever wondered how to make your money work for you, investing is the answer. It might seem intimidating at first, but with a little knowledge, you can start growing your wealth and securing your financial future. Let’s break down the basics of investing so you can get started with confidence.
Why Invest?
Saving money in a traditional savings account is safe, but it won’t help you build wealth over time. Inflation gradually reduces the value of your money, which means that by not investing, you’re actually losing purchasing power. Investing allows your money to grow faster than inflation, giving you financial security and helping you reach long-term goals like buying a home, funding education, or retiring comfortably.
Types of Investments
There are many ways to invest, but here are a few common options for beginners:
Stocks: When you buy shares of a company, you become a partial owner. Stocks have the potential for high returns but come with higher risk.
Bonds: Essentially loans to companies or governments, bonds are generally lower risk than stocks and provide regular interest payments.
Mutual Funds & ETFs: These investment vehicles pool money from multiple investors to buy a diversified mix of stocks, bonds, or other assets, making them a great choice for beginners looking for diversification.
Real Estate: Investing in property can generate rental income and appreciate over time, though it requires more upfront capital and involvement.
How to Get Started
Set Your Financial Goals: Decide why you want to invest. Are you building wealth for retirement, saving for a major purchase, or creating an emergency fund?
Create a Budget: Before investing, ensure you have a solid budget, an emergency fund, and no high-interest debt. Investing is most effective when it’s done with money you won’t need immediately.
Choose Your Investment Platform: There are many online brokers and investing apps that make it easy to get started. Look for platforms with low fees, educational resources, and user-friendly interfaces.
Start Small: You don’t need thousands of dollars to begin. Many platforms allow you to invest with just a small amount and build from there.
Diversify: Avoid putting all your money into one investment. A mix of stocks, bonds, and other assets helps manage risk.
Long-Term Mindset
Successful investing isn’t about getting rich quick, it’s about consistency and patience. Markets will go up and down, but staying invested and regularly contributing can lead to significant growth over time thanks to compound interest.
Keep Learning
The world of investing is constantly changing, and staying informed is key. Read books, follow financial news, and consider consulting with a financial advisor as your portfolio grows.
Starting your investing journey may feel overwhelming, but taking that first step is the hardest part. Over time, you’ll gain confidence, grow your wealth, and take control of your financial future.
Trending Topics


Recent Posts
5 Common Investing Mistakes and How to Avoid Them
Apr 17, 2025