Debt Management

Paying off loans and credit cards

Loading...

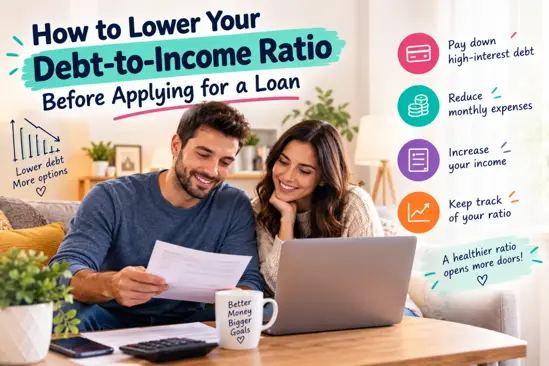
How to Lower Your Debt-to-Income Ratio Before Applying for a Loan

Your debt-to-income ratio (DTI) can affect whether a lender approves your application, how much you can borrow and the interest rate or terms you are offered. If you expect to apply for a mortgage, car finance or personal loan soon, improving your DTI can be one of the most practical steps you take.

The goal is simple: reduce the monthly debt commitments shown on your application, increase stable documented income where possible, and avoid changes that make your finances look riskier. This guide explains how to lower debt-to-income ratio over the next 30 to 90 days without assuming debt consolidation is the answer.

What Debt-to-Income Ratio Means and Why Lenders Care

Debt-to-income ratio compares your regular debt payments with your gross monthly income (income before tax). Lenders use it to judge whether you have enough room in your budget for a new repayment.

A lower ratio generally suggests you can manage another monthly payment more comfortably. A high ratio does not automatically mean rejection: lenders also assess your credit history, savings, deposit, employment, loan term and the affordability rules in your country. However, DTI is a quick and important affordability measure.

An acceptable debt-to-income ratio depends on the lender and loan type. As a broad guide, many lenders prefer lower ratios, while mortgage lenders may apply stricter affordability tests and stress-test your payments against higher interest rates. Do not treat any single percentage as a guaranteed approval threshold. Ask the lender or a regulated broker which affordability criteria apply to your application.

How to Calculate Your Front-End and Back-End DTI Ratios

Knowing how to calculate debt-to-income ratio helps you focus on the payments that matter. Use your gross monthly income and monthly payment obligations, not outstanding balances alone.

  • Front-end DTI measures housing costs as a share of gross monthly income. It may include rent or a proposed mortgage payment, property taxes, buildings insurance and service charges where relevant.
  • Back-end DTI measures housing costs plus other recurring debt payments, such as credit card minimums, car finance, student loan repayments and personal loans.

Use these formulas:

Front-end DTI = monthly housing costs ÷ gross monthly income × 100
Back-end DTI = total monthly debt payments ÷ gross monthly income × 100

For example, suppose your gross monthly income is €4,000. Your monthly rent is €1,100, credit card minimum payment is €120, car finance is €280 and student loan repayment is €100.

CalculationAmountRatio
Front-end: €1,100 ÷ €4,000Housing only27.5%
Back-end: (€1,100 + €120 + €280 + €100) ÷ €4,000€1,600 total monthly debt40%

A debt-to-income ratio calculator can speed up the maths, but check its inputs carefully. Some lenders count commitments differently, especially childcare, maintenance payments, buy-now-pay-later plans or loans ending soon. Your lender's own calculation is the one that matters.

Check Which Debts Count in Your DTI

Start with a complete list of every regular obligation. A common mistake is to focus on what you owe rather than what you must pay each month. A €10,000 loan with a €100 monthly payment may affect DTI less than a €2,000 credit card with a €180 minimum payment.

Items commonly included in back-end DTI or affordability checks include:

  • Mortgage or rent payments and, where applicable, property charges
  • Credit card minimum payments, overdraft commitments and revolving credit
  • Personal loans, car loans, lease payments and hire purchase agreements
  • Student loan repayments
  • Buy-now-pay-later instalments and retailer finance
  • Maintenance or other court-ordered recurring payments

Regular living costs such as food, utilities and transport may not always appear in a basic DTI formula, but lenders often consider them in a wider affordability assessment. Include them in your own budget so you do not borrow more than you can safely repay.

Lower Your Monthly Debt Payments

The fastest way to improve DTI is usually to remove or reduce a monthly payment. This is different from merely reducing a balance. Before moving money around, check whether a change will actually reduce the payment reported to the lender.

  1. Clear a small payment completely. If you can pay off a small credit card, BNPL plan or short-term loan, you may remove its minimum payment from your monthly commitments.
  2. Pay down revolving credit. Credit card minimums often fall as the balance falls. Pay enough before the statement date for the lower balance and payment to appear on your statement.
  3. Request a lower payment only with care. Extending a loan term can reduce monthly debt payments, but it may increase total interest and can be viewed differently by lenders. Read the terms before agreeing.
  4. Use savings selectively. Keeping an emergency buffer is important. Do not empty your cash reserves to clear debt if it leaves you unable to handle a basic surprise expense.

Debt consolidation can lower a monthly payment, but it is not automatically a win. A new consolidation loan adds a credit application and may extend repayment for years. Consider it only when the rate, fees, total cost and repayment plan are clearly better, and avoid applying for several products shortly before your main loan application.

Pay Down the Balance That Improves Your DTI Fastest

When cash is limited, rank debts by their monthly-payment impact. First, identify balances you can clear in full to eliminate a payment. Next, target cards or revolving credit where an additional payment is likely to reduce the required minimum quickly.

For example, paying €500 towards a large instalment loan may not change its fixed monthly payment at all. The same €500 could potentially clear a small retail-finance balance and remove a €45 monthly obligation. For DTI purposes, the second option may have a faster visible effect.

That does not replace the usual interest-rate strategy for long-term debt repayment. High-interest debt still deserves urgent attention. The best 30- to 90-day plan balances total borrowing cost with the need to improve debt-to-income ratio for mortgage or loan affordability.

Increase Reliable Income Lenders May Consider

More gross income can lower your ratio, but lenders generally want income that is stable, provable and likely to continue. Employment income supported by payslips, tax records and bank statements is normally more useful than a one-off payment or informal work.

Possible qualifying income can include a permanent pay rise, regular contracted hours, established self-employment income or documented rental income, depending on the lender and local rules. Do not include future bonuses, cash work, a hoped-for promotion or income that you cannot verify. Using unverified income on an application can lead to delays, rejection or more serious problems.

If your income has recently changed, ask what evidence is required and whether you need a longer track record. For a joint application, adding another borrower can improve the combined income calculation, but both applicants' debts and credit profiles will be assessed too.

Avoid New Credit and Loans Before Applying

In the run-up to a loan application, keep your financial profile steady. Opening a new credit card, financing a purchase, taking a car lease or using a new BNPL account can raise your monthly obligations and trigger credit checks.

  • Do not apply for credit simply to improve your available credit limit.
  • Delay non-essential financed purchases until after the lending decision.
  • Keep making every existing payment on time.
  • Avoid large unexplained transfers, cash deposits or frequent overdraft use where possible.
  • Do not close an old account without checking how it affects your overall financial position.

Consistency matters. Lenders typically review recent statements, so a calm 60 to 90 days is often more persuasive than a last-minute scramble.

Correct Errors on Your Credit Reports and Loan Statements

Check your credit report and each loan statement early. Incorrect balances, duplicate accounts, an account that should show as settled, or a wrongly reported missed payment can distort the picture a lender sees.

Dispute errors directly with the lender or credit reporting agency and keep copies of your evidence. Corrections can take time, so start well before you apply. Also confirm that payments you have made are reflected in the current balance and minimum payment. If you have just cleared a debt, obtain a settlement letter if available.

Set a Target DTI and Track Your Progress

Turn the ratio into a short action plan. Use the lender's stated limit if one is available; otherwise, aim to create a meaningful buffer below the level you believe is causing concern. Track your monthly debt payments, not just balances.

TimeframePriority actions
Days 1–30List all debts, check reports, stop new borrowing and clear one small payment if possible.
Days 31–60Direct extra cash to revolving balances, confirm updated minimum payments and collect income documents.
Days 61–90Review statements, confirm settled accounts are updated and compare your new DTI with your target.

A free budget app such as WhizBudget can help you see recurring debt payments alongside income and essential spending. Update it after each statement cycle so your plan reflects the payment a lender is likely to see.

When a High DTI Requires a Different Borrowing Plan

If your DTI remains high after realistic changes, do not force the application. A better plan may be to borrow less, save a larger deposit, choose a lower-priced property or vehicle, repay debt for longer, or wait until a fixed loan ends.

For a mortgage, speak with a regulated mortgage adviser who understands local lending rules. They can explain whether a different term, product or timing is realistic without encouraging unaffordable borrowing. Never manipulate documents or omit debts to qualify; affordability problems become much more expensive after approval.

Frequently Asked Questions

What is a good debt-to-income ratio?

There is no universal figure because lenders and countries use different affordability rules. Lower is generally better. Ask your chosen lender what it considers acceptable for your loan type, and leave room in your budget for rate rises and essential costs.

Does paying off a credit card improve debt-to-income ratio?

Yes, especially if paying it off removes the monthly minimum payment. The improvement is based on the payment that disappears or falls, rather than the card balance alone.

How quickly can I lower my DTI before applying for a loan?

You may see a change after your next statement cycle if you clear a debt or reduce a card balance enough to lower its minimum payment. Allow 30 to 90 days for statements and credit records to update, and keep proof of settlement.

Does rent count in debt-to-income ratio?

Rent is commonly included as a housing cost in affordability calculations, although methods vary. If you are applying for a mortgage, the lender will assess the proposed mortgage payment and other housing-related costs.

Can I use overtime or freelance income to improve my DTI?

Only if the lender accepts it and you can document a stable history. Regular payslips, contracts, tax returns and bank statements are more persuasive than irregular or newly started income.

Should I consolidate debt before a mortgage application?

Not by default. Consolidation may reduce a monthly payment but can increase total interest, create a new credit inquiry and extend the debt. Compare the full cost and speak to a regulated adviser if you are unsure.

Conclusion: Improve Your DTI Before You Apply

To lower your debt-to-income ratio, focus on the monthly commitments a lender will see: eliminate small payments, reduce revolving credit, verify your records, document reliable income and avoid taking on new debt. A focused 30- to 90-day plan can make your application stronger without taking unnecessary financial risks.

Use WhizBudget, the free budget app, to track every repayment, test your target ratio and stay in control of your loan preparation. Start with your current monthly payments today, then make the next payment decision count.

How to Handle Medical Debt: Check Your Bill, Lower the Balance, and Set Up Payments

A medical bill can arrive when you are already dealing with illness, recovery, or a sudden change in income. The most important rule is simple: do not assume the first amount you see is final or correct. Before paying, take time to check the charges, compare them with your insurer’s statement, ask about discounts, and agree on payments you can realistically afford.

This guide explains how to handle medical debt step by step, with practical actions you can take whether the bill comes from a hospital, clinic, dentist, specialist, or private healthcare provider. Keep notes, ask for written confirmation, and avoid promising more than your monthly budget allows.

Why Medical Bills Are Often Higher Than Expected

Medical costs can be confusing because one episode of care may create several bills. You may receive separate invoices for the hospital, consultant, diagnostic tests, anaesthesia, ambulance transport, laboratory work, or medicines. If you have private health insurance, the provider’s initial charge may also be higher than the amount you ultimately owe.

Common reasons for an unexpectedly high bill include:

  • Charges were submitted before insurance or public-health reimbursement was processed.
  • Your policy has an excess, co-payment, annual limit, waiting period, or excluded treatment.
  • A service was coded incorrectly or charged twice.
  • You received care outside your insurer’s approved network, where relevant.
  • The invoice includes an administrative error, an unrecognised service, or a charge for a cancelled appointment.

Do not ignore the invoice, but do not rush to pay it in full either. Contact the billing office promptly to say you are reviewing it. This can help prevent the account from moving through the provider’s internal collections process while you investigate.

Gather These Documents Before You Call

Having the right paperwork in one place makes it easier to spot mistakes and explain your case. Create a folder, either paper or digital, for every letter, invoice, email, and note.

  • The original bill and any follow-up statements.
  • An itemised bill showing each treatment, test, medicine, and fee.
  • Your insurance explanation of benefits (EOB), claims statement, or reimbursement decision.
  • Your insurance policy details, including excess and coverage limits.
  • Appointment confirmations, referral letters, and discharge paperwork.
  • Proof of income if you may apply for medical bill financial assistance.
  • A call log with dates, names, departments, and a short summary of each conversation.

WhizBudget, a free budget app, can also help you see what room you have for a future payment arrangement without guessing. List essential household spending first, then calculate what remains after regular commitments.

How to Review a Medical Bill for Errors

Ask the provider for an itemised bill if you have only received a summary. This is one of the best first steps in how to handle medical debt because vague statements make it hard to verify what you are being charged for.

  1. Check your name, date of birth, patient number, and dates of treatment.
  2. Compare each item with the care you actually received.
  3. Look for duplicate charges, incorrect quantities, and services that were cancelled or never provided.
  4. Check whether a payment, deposit, referral credit, or insurance adjustment is missing.
  5. Ask for plain-language descriptions or billing codes you do not understand.

Small errors can add up. For example, an invoice might include two imaging charges for one scan, an overnight stay when you went home the same day, or a private-room fee you did not request. Raise questions calmly and specifically; you are asking the provider to verify its records, not making an accusation.

How to Compare the Bill With Your Insurance Explanation of Benefits

An EOB is not usually a bill. It is your insurer’s explanation of how a claim was assessed: the amount submitted, the amount covered, any adjustment, and the amount you may owe. In some European systems, the equivalent may be a reimbursement statement from your insurer, mutual fund, or public health authority.

Match the provider’s invoice against the EOB line by line. Confirm that the provider billed the insurer, the insurer used the correct policy details, and any insurer payment or adjustment appears on your bill. Pay particular attention to:

  • Whether the service date and provider match.
  • The portion marked as covered versus excluded.
  • Your excess, co-payment, or percentage contribution.
  • Whether the claim was declined because a referral or pre-authorisation was missing.

If the insurer denied a claim, call the insurer before paying the provider. Ask for the precise reason and whether you can appeal, submit additional documents, or request a coding review. Deadlines for appeals can be short, so act quickly.

Steps to Dispute Incorrect Medical Charges

If you find an error, learn how to dispute a medical bill in writing as well as by phone. A written record reduces misunderstandings and gives you evidence if the matter takes time to resolve.

  1. Call the provider’s billing department and identify the exact charge you are disputing.
  2. Ask that the disputed amount be placed on hold while the account is reviewed.
  3. Send a dated email or letter with your account number, disputed line items, reason for the dispute, and copies of supporting documents.
  4. Request a corrected itemised bill and a written response.
  5. Follow up by the date the provider gives you, and keep copies of everything.

You can say: “I am reviewing invoice number [number]. I believe the charge for [service] on [date] is incorrect because [reason]. Please place this amount on hold, investigate it, and send me a written explanation and revised itemised bill.”

If the issue is linked to insurance, ask the provider and insurer to confirm any corrected claim submission in writing. Continue paying any undisputed portion only if you can do so without undermining your essential expenses.

How to Ask a Hospital or Provider for Financial Assistance

Many hospitals, clinics, and charitable providers have hardship policies, charity care, income-based discounts, or patient support funds. These programmes may be available before a bill is overdue, so ask early. Eligibility rules vary by country and provider, and some schemes can reduce the balance substantially.

Ask the billing office for its financial assistance policy and application form. You may need to provide payslips, benefit statements, bank statements, tax documents, or evidence of recent hardship such as unemployment or reduced working hours. Do not assume you earn too much to qualify; some providers offer partial reductions on a sliding scale.

Use this sample script:

“I want to resolve this bill, but I cannot pay the current balance without falling behind on essential living costs. Could you tell me whether you offer charity care, income-based discounts, hardship support, or a self-pay reduction? Please send me the application and explain which documents you need. I would also like any decision and revised balance in writing.”

How to Negotiate a Lower Medical Bill

When assistance is unavailable or only partly reduces the bill, you can still ask how to negotiate medical bills. Request a review of the balance and ask whether the provider can apply an uninsured, prompt-payment, hardship, or administrative discount. A provider may have flexibility, particularly when you contact them before the account becomes seriously overdue.

Be truthful about what you can pay. You might offer a realistic lump sum if you have savings set aside after protecting emergency needs, or request a reduced balance paired with affordable instalments. Never drain money needed for rent, food, utilities, transport, or necessary insurance simply to make a larger offer.

Before sending money, get a written agreement stating the reduced total, payment deadline, and that the payment settles the agreed balance. If a discount is declined, ask whether a supervisor or patient financial services team can review the request.

How to Set Up an Affordable Medical Debt Payment Plan

A medical debt payment plan should fit your budget, not the provider’s preferred timetable. Add up your monthly take-home income and subtract essential costs, minimum commitments, and a modest buffer for irregular expenses. The amount left is the maximum you should offer—not an aspirational number.

Monthly budget itemExample amount
Net household income€2,600
Essential living costs and existing commitments€2,350
Buffer for variable costs€100
Affordable medical payment€150

Ask whether the plan is interest-free, whether there are set-up fees, and what happens if you need to change a due date. Confirm the number of payments, payment amount, and remaining balance in writing. Track the arrangement in WhizBudget so the payment is included alongside your regular bills each month.

What to Know Before Using a Medical Credit Card or Personal Loan

Medical finance products and personal loans can make an urgent bill feel easier to manage, but they may add interest, fees, and stricter repayment terms. Promotional financing can be especially risky if interest is charged retroactively when the balance is not cleared by the end of the promotional period.

Before borrowing, compare the total cost with an interest-free payment plan directly from the provider. Read the annual percentage rate, fees, promotional conditions, and missed-payment consequences. In many cases, financial assistance, a negotiated reduction, or a direct instalment plan is safer than converting a medical bill into expensive consumer credit.

How Medical Debt Can Affect Your Credit

The credit impact of medical debt depends heavily on where you live, the reporting rules in your country, and whether the debt has been passed to a third party. In some European countries, medical providers do not routinely report unpaid healthcare bills to consumer credit files in the same way lenders report loans. However, a court judgment, formal default process, or unpaid credit agreement used to finance care may affect your record.

Ask the provider what happens if payments are missed and whether an account will be transferred. Check your local credit report rules and act early if you are struggling. Resolving billing errors and arranging an affordable plan before a debt escalates is generally the best protection.

When to Seek Help From a Nonprofit Credit Counselor or Patient Advocate

Seek independent support if the bill is large, the insurance decision is difficult to understand, you have several providers billing you, or your health makes it hard to manage calls and paperwork. A patient advocate may help review charges, navigate insurer appeals, and locate assistance programmes. A reputable nonprofit debt or credit counselling service can help you build a sustainable household budget and assess your options.

Choose organisations that explain fees clearly and do not pressure you into borrowing. Bring your itemised bills, EOBs, correspondence, household income details, and notes from conversations.

FAQs About Handling Medical Debt

Should I pay a medical bill before checking it?

Usually, no. Review the invoice, request an itemised bill, and compare it with your insurer’s statement first. Contact the provider promptly if you need time or find an error.

Can I ask for a discount on a medical bill?

Yes. Ask about hardship support, charity care, income-based reductions, self-pay discounts, or prompt-payment discounts. Request the final agreed balance in writing.

What is the best way to dispute a medical bill?

Identify the specific charge, ask the billing office to place it on hold, and send a written dispute with supporting documents. Keep a copy and request a written outcome.

What if I cannot afford the provider’s proposed monthly payment?

Offer an amount based on your real budget and ask for a longer, interest-free arrangement. Do not agree to payments that would force you to miss essential household costs.

Will unpaid medical debt damage my credit?

It depends on local law, reporting practices, and whether the debt becomes a formal default or is financed through credit. Ask about the provider’s process and check the rules where you live.

Can I apply for financial assistance after treatment?

Often, yes. Many providers accept applications after care has been delivered, although deadlines may apply. Contact the billing or patient financial services department as soon as possible.

Take Control Before You Pay

Handling a medical bill starts with slowing down: get an itemised invoice, check insurance adjustments, challenge mistakes, and ask for support before agreeing to a payment amount. Medical debt relief options can include corrected charges, financial assistance, a negotiated balance, and an affordable direct payment plan.

Use WhizBudget for free to map your essential spending and choose a monthly payment you can maintain. A clear budget, good records, and written agreements can turn an overwhelming bill into a manageable next step.
How to Pay Off Buy Now, Pay Later Debt Before It Spirals

Buy now, pay later (BNPL) can make a purchase feel manageable because each instalment is small. The problem starts when several plans overlap: a pair of shoes, a phone, household items and travel costs can each have different payment dates. What looked affordable at checkout can become a difficult monthly cash-flow problem.

If you are juggling multiple plans, do not panic or blame yourself. The fastest route out is to make every payment visible, stop creating new obligations and use a clear BNPL debt repayment strategy. This guide focuses on practical steps for managing active plans, avoiding missed payments and rebuilding a spending plan that works.

How Buy Now, Pay Later Debt Can Become Difficult to Manage

A buy now pay later payment plan is not always presented like traditional borrowing, but it still creates a contractual payment obligation. Many short-term plans charge no interest when paid on time. That does not mean they are risk-free. Late fees, collection activity, account restrictions and possible credit-reporting consequences can make a missed payment more expensive than expected.

BNPL debt often becomes hard to manage for three reasons:

  • Payments are fragmented: several small instalments are easy to overlook.
  • Due dates do not match income: a payment may leave your account just before payday.
  • New purchases hide the total: each checkout shows only one instalment, not all existing commitments.

Your aim is to turn a collection of separate plans into one simple monthly picture. Once you know what is due and when, you can make decisions before your bank balance is under pressure.

List Every BNPL Balance, Due Date, and Remaining Payment

Start with an inventory. Check each provider app, email confirmation, bank statement and retailer account. Include plans that have only one payment left; those are still claims on your next pay packet.

Use a notebook, spreadsheet or a free budget app such as WhizBudget to create a list. Record the original purchase only if it helps you identify the plan; the important figures are what remains and when it is due.

Provider / itemPayment dueAmount duePayments leftBalance remaining
Provider A / trainers8th€222€44
Provider B / phone16th€455€225
Provider A / home goods27th€181€18
Total€85 this month€287

Also note whether the provider collects automatically from a debit card or bank account. An automatic collection can fail if there is not enough money available, so it needs just as much planning as a manual payment.

Calculate the True Monthly Cost of Your BNPL Plans

Add every instalment due between your next payday and the following payday. This is your real BNPL monthly cost, not the amount shown for any single order. Then compare it with your available income after essential costs such as rent, utilities, food, transport, insurance and minimum payments on other debts.

A simple calculation is:

Take-home pay − essential living costs − all BNPL payments due = amount left for savings, flexible spending and extra repayments.

If the result is negative, you have identified the problem early. Do not try to solve it by opening another pay-later plan. Instead, reduce flexible spending immediately and contact any provider whose payment you may not be able to make.

Stop Adding New Buy Now, Pay Later Purchases

Pause new BNPL purchases while you pay down existing plans. This is not a permanent ban on spending; it is a short-term rule that stops the balance from moving further away. Delete saved payment methods from shopping sites, remove provider apps from your home screen and unsubscribe from retail marketing emails if they trigger impulse purchases.

For necessary purchases, use money already allocated in your budget. If you cannot pay cash or debit today, consider whether the item can wait. A short pause gives your existing repayment plan room to work.

Choose a Repayment Order for Multiple BNPL Balances

Continue making every scheduled payment first. If you have money left after essentials and all required instalments, direct it to one plan at a time. Check your agreement before making an early repayment: many providers allow it, but the process and any effect on future scheduled collections can vary.

Choose one of these straightforward approaches:

  • Smallest balance first: clear the lowest remaining balance to reduce the number of due dates quickly. This can build momentum.
  • Highest-cost balance first: prioritise a plan with interest, fees or a more urgent collection risk. This can reduce total cost.
  • Cash-flow first: clear a plan with a large upcoming instalment if removing it will make your next month easier to manage.

For most short, interest-free plans, the smallest-balance or cash-flow approach is practical. The best method is the one you can follow consistently. After one plan is cleared, roll its former payment amount into the next target rather than treating it as extra spending money.

Build a Payment Calendar That Prevents Missed Due Dates

Put every due date into one calendar, alongside your paydays and essential direct debits. Set two reminders: one three to five days before the due date and another on the day before. If a provider takes payment automatically, aim to have the money in the relevant account at least one working day early, especially around weekends and bank holidays.

Match payments to paycheques. For example, if you are paid on the 25th and payments are due on the 2nd, 6th and 12th, move that money into a separate bills pot on payday. Treat it as already spent.

  1. List all payments due before your next payday.
  2. Set aside that total as soon as you are paid.
  3. Check the calendar once a week for new dates, refunds or completed plans.
  4. Keep a small buffer if possible for timing differences or failed collections.

WhizBudget can help you view upcoming bills and planned spending in one place, making it easier to see whether a due date will strain your account before it happens.

What to Do If You Cannot Afford an Upcoming BNPL Payment

Act before the due date. Contact the provider through its official app, website or customer support channel and explain that you are experiencing a temporary payment difficulty. Ask what options are available, such as changing a payment date, a short extension or a payment arrangement. Do not assume an option exists, and get any agreed change confirmed in writing.

Review the terms of your specific agreement before taking action. Provider policies, late charges and hardship support vary by country and product. If the payment is set to collect automatically, do not simply ignore it; understand whether changing the payment method or cancelling a mandate is permitted and what consequences may follow.

At the same time, protect essentials. Prioritise housing, food, energy, transport to work and necessary insurance. If several debts are unmanageable, contact a free, reputable debt-advice service in your country. In the UK, organisations such as StepChange and National Debtline offer free support; elsewhere in Europe, consumer advice bodies and national debt-counselling services may be available.

How Missed BNPL Payments Can Affect Your Credit

What happens if you miss a BNPL payment depends on the provider, product and country. A provider may charge a late fee, retry the payment, freeze your account, refer the balance to collections or report payment information to one or more credit reference agencies. Some products may not currently be reported in the same way as others, but practices can change.

Do not rely on general claims that BNPL never affects credit. Read your current agreement and the provider's credit-reporting policy, then check your credit report with the relevant agencies in your country if you are concerned. A missed payment can also affect your finances even if it is not immediately visible on a credit file, because fees and collection contact can add pressure.

When to Consider Returning an Item or Requesting a Refund

If a recent purchase is unused, unwanted or unsuitable, check the retailer's return policy promptly. A successful return may reduce or cancel the related BNPL balance, but do not assume this happens instantly. Keep proof of the return, monitor both the retailer and provider accounts, and continue making due payments unless the provider confirms that the plan has been adjusted or closed.

For faulty goods or services not delivered, contact the retailer first and raise a dispute through the BNPL provider if its process allows. Follow the stated deadlines and save screenshots, emails and delivery evidence. A refund can be useful, but it should not be your only repayment plan because processing times vary.

How to Rebuild Your Spending Plan After Paying Off BNPL Debt

Once the final balance is cleared, keep the old payment amount in your monthly plan for a while. Redirect it first to a small emergency fund. Even a modest buffer can prevent the next unexpected expense from becoming another instalment plan.

Then create a realistic sinking fund for predictable costs such as annual insurance, gifts, repairs and holidays. Divide an expected annual cost by the number of months until it is needed and save that amount each month. This turns future purchases into planned spending rather than debt.

Use a weekly check-in to compare planned and actual spending. WhizBudget is a free budget app that can help you track categories and give each euro a purpose before you spend it. The goal is not perfection; it is knowing that your available cash covers the commitments you make.

FAQs About Buy Now, Pay Later Debt

Can I pay off BNPL debt early?

Often, yes. Check the provider's app or agreement for an early-settlement option and confirm that future automatic payments will be updated. Rules vary, so verify the current terms before paying extra.

Should I use a credit card or loan to pay off BNPL debt?

Not automatically. Moving several short-term plans to a new credit product may simplify dates, but it can also add interest, fees or a longer repayment period. Compare the total cost and only consider it if you can afford the new payment and will stop adding BNPL purchases.

What happens if I miss a BNPL payment?

You may face a late fee, a retried collection, account restrictions, collections activity or potential credit reporting. The exact outcome depends on the provider, product and local rules. Contact the provider before the due date where possible.

Can a retailer refund a purchase after I have started paying with BNPL?

Usually, a valid refund should be applied to the related plan, but timing and process vary. Return the item under the retailer's policy, retain evidence and keep checking your BNPL account until the adjustment is confirmed.

Does BNPL debt affect my credit score?

It can, depending on the provider and country. Some providers may perform credit checks or report payment performance, while others may not report every product. Review the agreement and current reporting policy rather than making assumptions.

How much should I budget for BNPL each month?

Budget the full amount due across all plans before your next payday, not just one instalment. If that total does not fit after essential costs, pause new purchases and contact providers about any payment difficulty.

Conclusion: Take Control One Payment at a Time

Buy now pay later debt is manageable when you make the full picture visible. List every plan, reserve money around paydays, stop adding new instalments and ask for help before a payment is missed. Small actions taken today can prevent fees, stress and a larger debt problem tomorrow.

Start your inventory now, choose your first repayment target and use WhizBudget to build a clear, free spending plan around your real due dates. A budget that reflects every commitment is the foundation for getting back in control.

What to Do When a Debt Collector Contacts You

Getting a call, email, letter, or text from a debt collector can feel intimidating, especially if the debt is old, unexpected, or linked to a difficult period in your life. The most important thing to remember is simple: you do not have to react immediately. A calm, organised response can help you avoid scams, protect your consumer rights, and decide whether the debt is accurate and affordable.

This guide explains what to do when a debt collector contacts you, step by step. It covers how to verify the collector, request proof, check your credit reports, communicate safely, document everything, and seek help if you need it. Debt collection rules, limitation periods, reporting rules, and dispute deadlines vary across Europe, so treat this as general guidance rather than legal advice.

What to Do Before Responding to a Debt Collector

Before you answer questions, pay money, or agree to a plan, slow the process down. Debt collectors may be legitimate, but mistakes happen. Debts can be sold between companies, balances can be wrong, and sometimes scammers pretend to collect debts that do not exist.

Your first goal is not to argue. It is to gather information and avoid giving away details that could be misused. If you receive a phone call, you can say that you do not discuss financial matters by phone and ask for written information. If you receive a letter or email, do not click links or call numbers until you independently verify the company.

Take these first steps:

  • Write down the date, time, phone number, email address, or postal address used.
  • Ask for the collector's company name, registration details, and contact address.
  • Ask who the original creditor was, the amount claimed, and the account reference.
  • Do not confirm your full date of birth, banking details, card number, or online banking access.
  • Do not make a payment just to make the call stop.
  • Do not admit liability until you have reviewed the evidence and your local rules.

If the collector becomes aggressive, end the conversation politely. A legitimate collector should be able to provide information in writing and allow you time to review it.

How to Verify Whether the Debt Is Legitimate

Verification has two parts: checking the company and checking the debt. A real collection agency should be traceable through official business registers, financial conduct registers where relevant, professional memberships, or the website of the original creditor. Do not rely only on the phone number provided by the caller.

To check the collector, search for the company independently. Look for a registered office, official website, regulator entry, consumer complaints, and contact details that match the letter you received. Then contact the original creditor using details from an old statement, the creditor's official website, or your banking records. Ask whether they still own the debt or have assigned it to a collection agency.

To check the debt itself, compare the collector's claim with your own records. Look for old loan agreements, credit card statements, utility bills, bank transactions, emails, payment confirmations, or account closure letters. Pay attention to the dates. In many European countries, there are limitation periods after which a creditor may be restricted from taking court action, but these rules vary significantly and can be affected by payments, written acknowledgements, or court judgments.

Question to checkWhy it matters
Do I recognise the original creditor?Collections are often sold, so the collector's name may be unfamiliar even when the original account is real.
Is the balance correct?Fees, interest, payments, or duplicate accounts can make the amount inaccurate.
Is the debt too old?Time limits vary by country and debt type. Get advice before paying or acknowledging an old debt.
Has there already been a court judgment?Court-ordered debts may have different enforcement rules and deadlines.
Does it appear on my credit report?Credit reporting can reveal errors, duplicate collections, or identity theft.

How to Request Debt Validation in Writing

A debt validation letter is a written request asking the collector to prove what they are trying to collect. The exact legal term and deadline may differ depending on your country, but the principle is the same: ask for clear evidence before you pay or agree to anything.

Your request should be short, factual, and sent in a way you can prove. Use registered post, tracked delivery, secure email, or the collector's official dispute portal if available. Keep a copy of everything you send.

Ask the collector to provide:

  • The name and address of the original creditor.
  • The current creditor if the debt was sold or assigned.
  • The original account number or reference.
  • A breakdown of the balance, including interest, fees, and payments.
  • Copies of agreements, statements, invoices, or notices supporting the claim.
  • Proof that the collector has authority to collect.
  • The date of the last payment or account activity, if relevant.

You do not need to write a long legal argument. A simple letter works well: identify yourself, state that you do not admit liability, request validation of the debt, and ask the collector to pause collection activity until they respond where your local law requires or allows it. If you are unsure about limitation rules, avoid saying anything that could be treated as acknowledging the debt.

When the response arrives, compare it with your records. If the collector cannot provide meaningful proof, you may have grounds to dispute the debt. If they provide evidence and the balance appears correct, you can move on to deciding how to handle payment or negotiation.

How to Review Your Credit Reports for Collection Accounts

Debt collectors may report collection accounts to credit reference agencies, but reporting systems differ across Europe. In some countries, negative credit data is heavily regulated and time-limited. In others, private credit bureaus maintain broader records. Either way, checking your credit reports helps you spot errors and understand how the debt may affect borrowing, renting, insurance, or mobile contracts.

Request your credit data from the main credit reference agencies in your country. Under data protection laws such as the GDPR, you generally have rights to access personal data held about you. Review each report carefully because one agency may show information that another does not.

Look for these problems:

  • A collection account you do not recognise.
  • A debt listed more than once by different collectors.
  • An incorrect balance or payment status.
  • A paid debt still showing as unpaid.
  • An account belonging to someone with a similar name.
  • Old information that should no longer be reported under local rules.
  • Signs of identity theft, such as accounts you never opened.

If you need to know how to remove inaccurate collections from credit report files, start by disputing the specific error with the credit reference agency and the company reporting it. Include evidence such as payment receipts, settlement letters, identity theft reports, account closure confirmation, or correspondence from the creditor. Do not expect a dispute to erase a valid debt automatically. The goal is to correct inaccurate, incomplete, duplicated, outdated, or unverifiable information.

What to Say and Not Say When a Collector Calls

Phone calls can pressure you into decisions you would not make after reading the facts. You are allowed to set boundaries. In many places, collectors must follow rules about fair treatment, harassment, misleading statements, and contact times. Your debt collector rights may include the right to receive information, the right to challenge inaccurate claims, and the right not to be harassed, but the details depend on your location.

Use calm, limited language. For example:

  • I do not discuss debts by phone. Please send details in writing.
  • I do not admit liability. I am requesting proof of the debt.
  • Please provide the name of the original creditor and your authority to collect.
  • I will review the documents and respond in writing.
  • Do not contact me at work. Please use my postal address or email.

Avoid statements that could create problems later, especially for old debts. Do not say that you definitely owe it, promise to pay by a certain date, provide card details, or agree to a direct debit before you understand the debt and your budget. If you decide to pay, get the agreement in writing first.

If the collector threatens arrest, immigration consequences, public embarrassment, or immediate seizure of goods without proper legal process, treat that as a serious warning sign. Debt collection can be stressful, but legitimate civil debt collection should follow formal procedures.

How to Document Calls, Letters, Payments, and Disputes

Good records protect you. If a dispute escalates, you may need to prove what was said, what was sent, when a payment was made, or what the collector promised. Create a simple folder on your computer or in cloud storage, plus a paper folder for postal letters.

Track the following:

  • Dates and times of calls.
  • Names of people you spoke with.
  • Phone numbers, email addresses, and postal addresses used.
  • Summaries of conversations.
  • Copies of letters and emails sent or received.
  • Proof of delivery for important letters.
  • Debt validation responses and supporting documents.
  • Payment receipts, settlement agreements, and final balance confirmations.
  • Credit report disputes and investigation results.

If recording calls is legal in your country, check the rules before doing so. In some places, you must notify the other person or get consent. If you cannot record, write a note immediately after the call while the details are fresh.

WhizBudget, a free budget app, can help you track your income, essential bills, and available cash before you agree to a repayment plan. Keeping your debt file separate from your monthly budget can also make the process less overwhelming.

How to Spot Debt Collection Scams

Scammers use fear and urgency. They may pretend to be a solicitor, bailiff, court officer, tax agency, bank, or well-known collection company. They often know some personal information already, which can make the contact seem real.

Common debt collection scam warning signs include:

  • Refusing to provide written proof of the debt.
  • Demanding immediate payment to avoid arrest or prosecution.
  • Asking for payment by gift card, cryptocurrency, money transfer, or other unusual methods.
  • Using threats, insults, or excessive pressure.
  • Contacting you from a personal email address or untraceable number.
  • Asking for online banking passwords, one-time codes, or full card details.
  • Claiming you cannot speak to anyone else about the debt.
  • Providing company details that do not match official registers.

If you suspect a scam, do not engage. Hang up, do not click links, and do not download attachments. Contact the original creditor directly using official details. You can also report suspected fraud to your national consumer protection authority, police cybercrime unit, financial regulator, or data protection authority, depending on the situation.

What to Do If the Debt Is Accurate but You Cannot Pay

If the debt is valid but unaffordable, you still have options. Do not ignore it, but do not agree to payments that put rent, food, utilities, medicines, transport, or child support at risk. Priority expenses come first.

Start with a realistic budget. List your monthly net income, essential expenses, minimum debt payments, irregular annual costs, and emergency savings needs. Then calculate what you can safely offer. If the amount is very small, it is still better to be honest than to promise a payment that will fail.

OptionBest forWatch out for
Affordable payment planPeople with steady income who can pay over timeGet interest, fees, and review dates in writing.
Temporary hardship arrangementShort-term income loss, illness, or emergencyAsk how it affects credit reporting and future payments.
Full and final settlementPeople with a lump sum availableGet written confirmation that the remaining balance will not be pursued.
Formal debt solutionSerious debt problems involving multiple creditorsRules, costs, and credit impact vary by country.
Nonprofit credit counsellingAnyone unsure what to offer or prioritiseUse reputable free or low-cost services, not high-pressure firms.

When negotiating, keep everything in writing. A collector may accept a lower settlement or reduced payments, especially if you show a clear income and expense summary. Ask whether interest and charges will stop, how payments will be applied, and what will be reported to credit reference agencies.

Use WhizBudget to build a monthly spending plan before making an offer. A repayment plan should fit your real life, not just sound good during a stressful phone call.

When to Contact a Nonprofit Credit Counselor or Attorney

Some debt collection problems are straightforward. Others need expert help. A nonprofit credit counsellor can review your budget, explain repayment options, and help you prioritise debts. This is especially useful if you have several creditors, missed priority bills, or no clear idea of what you can afford.

Consider speaking with a qualified debt adviser, consumer organisation, or attorney if:

  • You receive court papers, enforcement notices, or bailiff communications.
  • The debt may be time-barred or close to a limitation deadline.
  • You believe the collector is harassing you or breaking local rules.
  • You are dealing with identity theft or fraud.
  • Your wages, bank account, or property may be at risk through legal enforcement.
  • You are considering insolvency, bankruptcy, or another formal debt solution.
  • The debt involves tax, child maintenance, rent arrears, or secured lending.

Free help may be available through municipal debt advice services, consumer protection agencies, charities, ombudsman schemes, legal aid clinics, or nonprofit credit counselling organisations. Avoid companies that demand large upfront fees, promise to wipe out debts with no consequences, or pressure you to sign quickly.

FAQs About Debt Collectors and Debt Validation

What is the first thing I should do when a debt collector contacts me?

Stay calm, avoid confirming personal or financial details, and ask for the collector's name, company, contact details, original creditor, amount claimed, and written information about the debt. Do not make a payment or promise until you have checked that the debt is legitimate.

What is a debt validation letter?

A debt validation letter is a written request asking the collector to prove the debt, including who the original creditor is, how much is owed, and why they have the right to collect. Send it in writing and keep a copy with proof of delivery where possible.

How do I dispute a collection account?

If you are wondering how to dispute a collection account, start with a written dispute to the collector. If the account appears on your credit report, also dispute it with the credit reference agency. Explain what is wrong and include copies of evidence. Valid debts are not automatically removed simply because you dispute them.

How can I remove inaccurate collections from my credit report?

You can request corrections if a collection is inaccurate, duplicated, too old to be reported, already paid, or belongs to someone else. Contact the credit reference agency and the data provider with evidence. The process and deadlines vary by country.

What are common debt collection scam warning signs?

Warning signs include pressure to pay immediately by unusual methods, refusal to provide written proof, threats of arrest, requests for sensitive details, and contact from a company you cannot verify. Hang up and independently check the creditor or agency before taking action.

What if I owe the debt but cannot afford to pay?

If the debt is accurate but unaffordable, review your budget, prioritise essential bills, and consider offering an affordable payment plan or settlement in writing. A nonprofit credit counsellor can help you compare options before you agree to anything.

Conclusion: Slow Down, Verify, Then Decide

A debt collector contact is not something to ignore, but it is also not something that should push you into a rushed decision. Verify the collector, request written validation, check your credit reports, keep detailed records, and watch for scams. If the debt is wrong, dispute it with evidence. If it is accurate, choose a repayment or advice route that protects your essential living costs.

The strongest response is organised, calm, and documented. If you need help understanding what you can afford, use WhizBudget as a free budget app to map your income, bills, and realistic repayment capacity before you speak with a collector again.

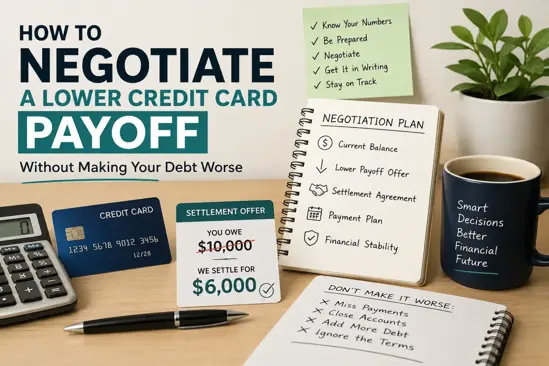
How to Negotiate a Lower Credit Card Payoff Without Making Your Debt Worse

If you are behind on credit card payments, or close to default, you may be wondering whether you can negotiate credit card payoff for less than the full balance. In some cases, a card issuer or debt collector may accept a reduced lump sum or structured settlement. But the process is risky if you rush, miss important details, or pay a company that promises results it cannot guarantee.

Credit card debt settlement can reduce what you owe, but it can also damage your credit file, trigger collection activity, and create a possible tax bill on forgiven debt. The goal is not simply to get a lower number. The goal is to settle credit card debt in a way that is clear, affordable, documented, and less harmful than doing nothing.

This guide explains when payoff negotiation makes sense, how to prepare, what to say, what to get in writing, and which warning signs to avoid. It is written for European readers dealing with credit card lenders, collection agencies, or debt purchasers, although exact rules vary by country. If you are unsure, consider speaking to a free debt advice charity, a regulated financial adviser, or a qualified tax professional.

When Negotiating a Credit Card Payoff Makes Sense

Negotiating a lower payoff usually makes sense only when the lender believes it may not recover the full balance. If your account is fully up to date and you have stable income, the issuer has little reason to accept less. If you are already behind, in serious financial hardship, or the account has been charged off or sold to a debt buyer, the lender may be more open to settlement.

You might consider trying to negotiate credit card debt if:

  • You are 60 to 180 days behind on payments and cannot realistically catch up.
  • You have received letters from a collections department or debt purchaser.
  • You can raise a lump sum from savings, family help, sale of an asset, or a temporary income boost.
  • Your budget shows that minimum payments are no longer sustainable.
  • You want to avoid a court claim, enforcement action, or years of unaffordable payments.

Settlement is not ideal if you can still afford contractual payments or if a short-term credit card hardship program would solve the problem. It is also not a good strategy if you would need to borrow from another high-interest lender to fund the settlement. Replacing one unaffordable debt with another can make your situation worse.

Payoff Negotiation vs. Hardship Program vs. Debt Management Plan

Before you settle credit card debt, understand the main options. A lower payoff is only one route. Depending on your income, credit file, and local consumer debt rules, another option may be safer.

OptionHow it worksBest forMain risk
Payoff negotiationYou ask the issuer or collector to accept less than the full balance, usually as a lump sum or short instalment plan.People already behind who can access a settlement amount.Credit damage, tax issues, and risk of paying without proper written agreement.
Credit card hardship programThe lender may reduce interest, pause fees, or lower payments for a limited period.People with temporary hardship who may recover soon.The account may be restricted or closed, and arrears may still affect your credit file.
Debt management planYou make one affordable monthly payment, often through a nonprofit or regulated provider, which is distributed to creditors.People with multiple unsecured debts and limited spare income.Creditors may not freeze interest, and repayment can take several years.

A hardship plan is often worth asking about before settlement if your income drop is temporary. A debt management plan can help if you owe several lenders and cannot negotiate each one alone. A settlement may be better if the account is already seriously delinquent and you have a realistic one-off amount to offer.

What to Do Before Contacting Your Credit Card Issuer

Preparation is the difference between a controlled negotiation and a stressful phone call that leads to a bad deal. Do these steps before you contact the issuer, collector, or debt buyer.

  1. List all debts. Include balances, account numbers, current status, interest rates, arrears, and who owns or collects each debt.
  2. Build a survival budget. Prioritise rent or mortgage, utilities, food, transport, insurance, child costs, and taxes before unsecured debt.
  3. Check what you can genuinely afford. Do not offer money needed for essentials. A settlement you cannot pay is not a settlement.
  4. Review your credit file. Check whether the account is marked as late, defaulted, charged off, or sold. This helps you understand who has authority to settle.
  5. Confirm the debt owner. If a collection agency contacts you, ask whether it owns the debt or collects on behalf of the issuer.
  6. Save a settlement fund separately. Keep it away from your daily spending account so you know exactly what you can offer.
  7. Decide your opening offer and maximum offer. Never negotiate without a ceiling.

A budgeting tool such as WhizBudget can help you separate essential spending from debt payments, estimate a realistic offer, and avoid agreeing to a settlement that leaves you short on rent or bills.

How Much Credit Card Companies May Agree to Settle For

There is no guaranteed settlement percentage. Be cautious of anyone who promises that all credit card companies will accept a specific amount. Outcomes depend on the lender, country, age of the debt, your hardship, whether the debt has been sold, and how much the collector believes it can recover through normal collection.

In general, creditors are more likely to consider a lower payoff when the account is seriously overdue, when the borrower can show real hardship, and when the offer is paid quickly. Debt purchasers that bought old accounts for less than face value may sometimes be more flexible, but they may also pursue collection aggressively.

Factors that can affect your settlement offer include:

  • How many months you are behind.
  • Whether interest and fees are still being added.
  • Whether the account has been defaulted or sold.
  • Your income, assets, and hardship evidence.
  • Whether you offer a lump sum or instalments.
  • Local rules on limitation periods, court claims, and debt enforcement.

As a practical approach, start lower than your maximum but not so low that the creditor refuses to engage. If you can pay €2,000 on a €6,000 balance, you might open below that and leave room to move. But do not invent numbers or pretend to have no income if that is not true. Creditor notes, call recordings, and affordability checks may be used later.

Step-by-Step: How to Negotiate a Lower Payoff

Use a calm, organised process. The goal is to reduce confusion and protect yourself before any money leaves your account.

  1. Call the correct department. Ask for the hardship, recoveries, settlements, or collections team. Front-line customer service may not have authority.
  2. Explain the hardship briefly. Mention job loss, illness, reduced hours, relationship breakdown, cost-of-living pressure, or other genuine cause. Keep it factual.
  3. State that you cannot afford the full balance. Avoid long emotional arguments. The key is affordability.
  4. Ask whether settlement is available. Do not begin by offering your maximum amount.
  5. Make a controlled opening offer. If you have a lump sum, say it is available only if the agreement is confirmed in writing.
  6. Ask about account reporting. Clarify whether it will be marked as partially settled, settled, satisfied, or similar wording used in your country.
  7. Request a written agreement before paying. This is non-negotiable. Never rely on a phone promise.
  8. Pay only through a traceable method. Use bank transfer, card payment, or another method that creates a record. Avoid cash or informal transfers.
  9. Keep every document. Save letters, emails, payment confirmations, account statements, and call notes.
  10. Check final reporting. After payment, verify that the balance is updated to zero or the agreed status on your statement and credit file.

If you speak by phone, write down the date, time, name of the representative, department, phone number, and summary of what was said. After the call, send a short follow-up email or letter confirming your understanding.

What to Say on the Phone or in Writing

You do not need to sound like a lawyer. You need to be clear, honest, and firm. Below is sample phone language you can adapt.

Sample phone script:

"I am calling about my credit card account. My financial situation has changed and I cannot afford the full balance or the normal monthly payments. I have reviewed my budget and can offer a one-off payment of [amount] as full and final settlement, if you confirm in writing that this will resolve the account and that no further balance will be pursued. Is this something your settlements team can consider?"

If the representative refuses, ask:

"Can you tell me what options are available for someone in financial hardship? Is there a credit card hardship program, interest freeze, payment plan, or settlement review process?"

If the creditor makes a counteroffer that is too high, respond with:

"I understand. Unfortunately, that amount is not affordable based on my current income and essential costs. My maximum available amount is [amount]. I do not want to agree to a payment I cannot make. Can this be reviewed again?"

You can also send a debt settlement letter. Keep it concise and include the account number, your hardship, the proposed amount, payment deadline, and request for written confirmation.

Sample debt settlement letter:

Dear [Creditor/Collector],

I am writing about account number [number]. Due to [brief reason], I am unable to pay the full outstanding balance. After reviewing my income and essential expenses, I can offer [amount] as a full and final settlement of this account.

This offer is made on the condition that, if accepted and paid by [date], the payment will satisfy the account, the remaining balance will not be sold or pursued, and the credit file will be updated to show the agreed settlement status. Please confirm the agreement in writing before I make payment.

Yours faithfully,

[Name]

Do not include unnecessary personal details. Do not send bank statements or medical documents unless you are comfortable and they are genuinely needed. Redact sensitive information where appropriate.

Documents and Terms You Must Get in Writing

Never pay a settlement based only on a phone conversation. A proper written agreement protects you if the account is later passed to another collector or the remaining balance is mistakenly pursued.

Before paying, confirm these terms in writing:

  • Your full name and account number.
  • Name of the creditor, collection agency, or debt owner.
  • The current outstanding balance.
  • The exact settlement amount.
  • Whether the payment is a full and final settlement or partial settlement.
  • The deadline for payment.
  • Where and how to pay.
  • Confirmation that no further amount will be collected after the agreed payment.
  • Confirmation that the remaining balance will not be sold to another collector.
  • How the account will be reported to credit reference agencies.
  • Whether interest, fees, and collection activity will stop after payment.
  • The name, job title, and contact details of the person or department issuing the agreement.

If the letter says only that your payment will be credited to the account, that is not enough. It must clearly say what happens to the unpaid balance. If the wording is unclear, ask for it to be amended before you pay.

Risks to Understand Before Settling Credit Card Debt

Settlement can be useful, but it is not painless. Understand these risks before you negotiate credit card payoff.

  • Credit score damage: Missed payments, defaults, and partial settlements can remain on your credit file for years, depending on local reporting rules.
  • Collection pressure: If negotiations fail, the creditor may continue calls, letters, or legal action.
  • No guaranteed approval: The issuer can refuse your offer or ask for more than you can afford.
  • Tax consequences: In some countries, forgiven debt may be treated as taxable income or have reporting consequences.
  • Scam risk: Some debt settlement companies charge high fees and tell consumers to stop paying without explaining the damage.
  • Account closure: Settled accounts are usually closed and cannot be used again.

The biggest mistake is stopping payments deliberately just to force a settlement when you could afford them. That can create avoidable late fees, default markers, stress, and legal risk.

Tax, Credit Score, and Collection Account Considerations

Tax treatment varies across Europe. In some places, cancelled or forgiven consumer debt may create taxable income. In others, personal insolvency or formal debt solutions may have different rules. Before accepting a large write-off, check local tax guidance or speak to a qualified adviser.

Credit file wording also matters. A settlement may be reported as settled, partially settled, satisfied, default satisfied, or a similar status. A partial settlement tells future lenders that you did not repay the full amount. That may affect mortgage applications, car finance, rental checks, or future credit card approval.

If a debt is already with a collection agency, identify whether the agency owns the account. If it only collects on behalf of the original issuer, the agreement should clearly show that the creditor authorised the settlement. If the debt has been sold, ask for evidence that the buyer has the right to collect and settle the account.

Also be aware of limitation periods. In many European jurisdictions, old debts may become legally unenforceable after a certain period if no payment or written acknowledgement has been made. The rules are specific and can be complex. Making a small payment or admitting liability may restart the clock in some places. Get advice before negotiating very old debts.

Red Flags: When Not to Use a Debt Settlement Company

Some people prefer professional help, especially if they have several creditors. But debt settlement companies can be expensive, and some operate in ways that harm consumers. Be very careful before paying anyone to negotiate credit card debt for you.

Red flags include:

  • They guarantee a specific settlement percentage.
  • They tell you to stop paying creditors without explaining consequences.
  • They charge large upfront fees before any debt is settled.
  • They refuse to explain their regulatory status or complaints process.
  • They tell you not to speak to your creditors.
  • They promise to remove accurate negative information from your credit file.
  • They pressure you to sign immediately.
  • They do not provide a clear written fee schedule.

Free or low-cost debt advice charities, consumer organisations, and regulated nonprofit agencies may be safer starting points. If you choose a paid company, check whether it is authorised in your country and whether its fees are reasonable compared with the possible savings.

Alternatives If the Issuer Refuses to Settle

If the card issuer refuses your settlement offer, do not panic. You may still have options.

  • Ask for a credit card hardship program: Request reduced interest, fee waivers, a payment holiday, or lower monthly payments.
  • Offer a short repayment plan: If you cannot pay a lump sum, ask whether they will accept instalments over three to twelve months.
  • Use a debt management plan: A structured plan can help with multiple unsecured debts.
  • Prioritise essential bills: Do not pay credit cards before housing, food, utilities, taxes, or child maintenance.
  • Sell non-essential assets: Only if it does not harm your ability to work or live safely.
  • Seek formal debt advice: Depending on your country, insolvency, debt relief, or court-approved repayment options may be available.
  • Improve cash flow: Cut unused subscriptions, negotiate bills, switch providers, or add temporary income.

Use WhizBudget to test different repayment scenarios before accepting any plan. If a proposed payment leaves your monthly budget negative, it is not sustainable, even if the creditor agrees to it.

FAQs

Can I negotiate credit card payoff myself?

Yes. Many people negotiate directly with their card issuer, collector, or debt buyer. The key is to prepare a budget, know your maximum offer, speak to the right department, and get the agreement in writing before paying.

Will credit card debt settlement ruin my credit score?

It can seriously damage your credit file, especially if the account already has missed payments or a default. A partial settlement may stay visible for years, depending on your country. However, if you are already in default, settling may help stop the balance from growing and close the account.

Is a credit card hardship program better than settlement?

It may be better if your hardship is temporary and you can afford reduced payments. A hardship program may lower interest or pause fees without requiring a lump sum. Settlement is usually more suitable when you cannot repay the full balance and the account is already seriously overdue.

Should I send a debt settlement letter or call first?

You can do either. A call may help you find the correct department and learn what options exist. A debt settlement letter creates a written record. Even if you negotiate by phone, insist on written confirmation before making any payment.

Can a creditor chase me after I pay a settlement?

If the agreement was poorly written, errors can happen. That is why your settlement letter must state that the agreed payment resolves the account and that the remaining balance will not be pursued or sold. Keep proof of payment forever.

Do I pay tax on forgiven credit card debt?

Possibly. Tax rules differ by country and by the type of debt solution used. A large forgiven balance may have tax consequences. Check local tax guidance or speak to a qualified tax adviser before agreeing to a major write-off.

Conclusion

Negotiating a lower credit card payoff can be a practical way to deal with unaffordable debt, but only if you protect yourself. Do not rely on verbal promises, do not offer money you need for essentials, and do not trust companies that guarantee results. Prepare your budget, confirm who owns the debt, make a realistic offer, and get every important term in writing.

If settlement is not suitable, ask about a credit card hardship program, debt management plan, or free debt advice. The best option is the one you can actually afford without falling behind on rent, food, utilities, or taxes.

WhizBudget can help you see your real monthly numbers, plan a safe settlement fund, and compare repayment options before you contact creditors. Start by building a clear budget today, then negotiate from a position of control rather than panic.

How We Consolidated Two Loans, Bought a Garage, and Saved Over $2,000

This is a real story that happened to my family less than a month ago. With some careful calculations, we managed to refinance one of our loans, purchase an interconnected parking space in the underground garage of our apartment building (along with a small cellar), and set ourselves up to save more than $2,000 in interest.

That’s the short version—now let’s get into the details.

We had three loans: one mortgage and two personal loans. One of the personal loans carried a pretty high interest rate. Our plan was to wait until we finished the refurbishment of our apartment, then refinance that loan to get a better deal. Initially, the idea was to close both personal loans and take out another mortgage.

But then an opportunity came up that we couldn’t pass on. We found out that we could buy an interconnected parking space in the underground garage of our building. To make the deal even sweeter, the purchase also included a small cellar—a nice bonus.

Here’s how it unfolded: we calculated the cost of the parking space plus cellar, added the balances of our two personal loans, and asked the bank for a new loan covering the total. They needed to evaluate our apartment and review our income to decide if we qualified. At first glance, everything looked fine.

Unfortunately, after many discussions, the bank approved a bit less than we had requested. Still, it was enough to buy the parking space and cellar, repay the personal loan with the highest interest rate, and partially pay down the other loan with the lower rate. That change alone reduced its term from 9 years to just 3.

In the end, we secured a larger loan at a lower interest rate, with a repayment period of 13 years instead of 9. According to the new repayment plan, we’ll save over $2,000 in interest over time if we keep paying as scheduled. Pretty great, right?

Our plan going forward is to use the debt snowball method: first tackling the smallest loan with the highest interest rate, then the smaller mortgage with the medium interest rate, and finally focusing on the main mortgage with the best interest rate.

Feel free to use the Debt consolidation calculator and see if you can save yourself some money.

Debt Consolidation: Is It the Right Move for You?

Do you ever feel like you’re juggling bills and hoping nothing hits the ground?

Your credit card payment is due on the 10th. The car loan? That’s the 15th. Student loans? Who knows anymore? It’s like every day is a new financial surprise.

So you Google "how to get my life together financially," and bam: debt consolidation pops up.

But is it actually a good idea? Let’s talk about it.


What's Debt Consolidation?

In plain English, debt consolidation means rolling multiple debts into one payment.

That’s it. Instead of five bills, you pay one. Hopefully, at a lower interest rate.

This could be a:

  • Personal loan you use to pay off high-interest credit cards
  • Balance transfer credit card (with 0% APR for a while)
  • Debt management plan through a non-profit
  • Home equity loan (for the bold and the brave)

Goal: Make it easier to manage, and ideally, cheaper over time.


When Debt Consolidation Might Make Sense?

  1. You’re drowning in interest.
  2. You’re making payments, but the balance isn’t budging. 
  3. You can qualify for a lower interest loan. 
  4. You just want one due date (your brain needs a break)

If this sounds like your life, debt consolidation could be worth a look.


But Hold Up—It’s Not a Magic Wand

Debt consolidation won’t fix bad spending habits. It doesn’t make debt disappear (sorry). It can even cost more if the repayment term is longer.

Your monthly payment is smaller, but if you're paying it for 7 years instead of 3... You get the idea.

Also:

  • Some loans have fees
  • You could lose 0% interest perks if you miss a payment
  • It might ding your credit score (short term)

This is why it pays to read the fine print like it's a gossip column.


Quick Tip List: Is It the Right Move for You?

Ask yourself:

  • Do I know how much total debt I have?
  • What's my average interest rate right now?
  • Can I realistically pay this off in 3-5 years with one loan?
  • Will I actually stop using my credit cards after?
  • Am I trying to avoid bankruptcy or just looking for simplicity?

Pro tip: If you have mostly credit card debt and your credit score is decent, a balance transfer card might save you the most.

But if your score's taken a hit or you're overwhelmed, a debt management plan through a non-profit might be a safer bet.


Story Time: A Tale of Two Friends

Alex had five credit cards. Interest was through the roof. He got a personal loan with a fixed rate, paid off the cards, and made one payment a month. He even set it to autopay. Done.

Taylor tried the same thing but kept using her credit cards. A year later, she had the loan and new credit card debt.

Same tool, different results.

The difference? Discipline.

Debt consolidation works best when it comes with a game plan.


Final Word: Take It or Leave It

Debt consolidation isn’t a scam, but it’s not a cure-all either.

It works for folks who:

  • Want fewer bills
  • Can get a better interest rate
  • Are ready to make a change

It’s not so hot for folks who:

  • Keep racking up debt
  • Don’t read the loan terms
  • Just want a quick fix

No shame either way. Just make sure whatever you choose helps you sleep better at night.

That’s the real goal.


P.S. If you're thinking about consolidating debt, check your credit score first. That tiny number packs a punch when it comes to your options.

And hey, don’t go it alone if you don’t have to. A chat with a non-profit credit counsellor is free, and sometimes, just talking to someone helps untangle the chaos.

Debt's a beast. But you? You’ve got this.

The Hidden Costs of Minimum Payments and How to Escape Them

Paying the minimum on a credit card feels responsible: the account stays in good standing and the bill is small. But the minimum payment is designed to keep you in debt for as long as possible. On a typical card it covers little more than the interest, so the balance barely moves.

This guide shows what minimum payments really cost, with real numbers, and a simple plan to get out faster without needing extra income.

How Minimum Payments Are Calculated

Card issuers use different formulas, but a common one is 1% of the balance plus that month's interest, with a floor of around $25. Some issuers use a flat 2–3% of the balance instead. Either way, the minimum shrinks as your balance shrinks, which is exactly why repayment drags on for years.

The Real Cost: A Worked Example

Take a $5,000 balance at 22% APR and the common formula above. The first minimum payment is $141.67. Here is what happens depending on how you pay:

Payment strategyTime to pay offTotal interest
Only the minimum (it falls as the balance falls)About 19 years (230 months)About $8,100
Keep paying the first minimum: $141.67 every month58 monthsAbout $3,120
Fixed $200 a month34 monthsAbout $1,750
Fixed $300 a month21 monthsAbout $1,020

Paying only the minimum costs more in interest than the original $5,000 you borrowed. Simply freezing your payment at the first month's minimum, with no extra money at all, cuts the payoff time from 19 years to under 5 and saves about $5,000.

The Other Hidden Costs

  • Less room in your budget for years. Money that goes to interest can't go to savings, investing or an emergency fund.
  • Higher credit utilisation. A balance that barely falls keeps your utilisation high, which can weigh on your credit score.
  • Penalty rates. One late payment can trigger a higher penalty APR on some cards, making the slow payoff even slower.
  • Lost opportunity. Every year spent paying 22% interest is a year your money isn't earning anything for you.

How to Escape the Minimum Payment Trap

1. Freeze your payment amount

Look at this month's minimum and commit to paying at least that amount every month from now on, even as the required minimum drops. Set it up as a fixed automatic payment so you don't have to think about it.

2. Add whatever extra you can

Even $25–$50 more each month makes a big difference because all of it reduces the principal. Look for the money in subscriptions you don't use (our 30-minute subscription audit helps) or in your grocery bill.

3. Pick a payoff order if you have several cards

Pay the minimum on everything, then put every spare dollar on one card. The avalanche method targets the highest interest rate first and saves the most money; the snowball method targets the smallest balance first for quicker wins. Compare both with your own numbers in our debt snowball vs avalanche calculator.

4. Consider a lower rate

A balance transfer card or a consolidation loan can cut the interest rate, but only helps if you stop adding new charges. Use the debt consolidation calculator to check whether it actually saves money, and read whether debt consolidation is right for you.

5. Stop the balance from growing

Track every purchase for a month and move the card to the back of your wallet. If the balance keeps rising while you repay it, no strategy will work.

Frequently Asked Questions

Is paying the minimum bad for my credit score?

Paying on time protects your payment history, which is good. The problem is that the balance stays high for longer, so your credit utilisation stays high too.

How much more than the minimum should I pay?

As much as your budget comfortably allows, but even keeping the payment fixed at today's minimum makes a dramatic difference, as the example above shows.

Should I save or pay off card debt first?

Keep a small emergency buffer first so a surprise bill doesn't go back on the card, then focus on the debt. Our emergency fund guide explains how to size that buffer.

How to Stay Motivated While Paying Off Debt

Most people don't fail at paying off debt because they choose the wrong method. They fail because month eight feels exactly like month one: the same payments, the same sacrifices, and a balance that seems to shrink far too slowly. Motivation fades long before the debt does.

The good news is that motivation can be designed. These tactics make progress visible, make sacrifices feel worth it, and help you keep going after a bad month.

1. Write Down Your "Why"

"Be debt-free" is too abstract to fight a craving. Make it concrete: "Stop sending $430 a month to the bank", "Take a holiday without a credit card", or "Never panic about rent again". Keep it somewhere you'll see it when you're about to spend.

2. Know Your Exact Debt-Free Date

A date turns a vague goal into a countdown. List each debt with its balance, rate and payment, and enter them in our debt payoff calculator to see your payoff month and how much faster extra payments get you there.

3. Choose a Method That Fits Your Personality

If you need quick wins, the snowball method (smallest balance first) gives you a closed account sooner. If saving money motivates you, the avalanche method (highest interest first) costs less overall. Our snowball vs avalanche guide explains the trade-off.

4. Make Progress Visible

Progress you can't see doesn't feel real. Update your balances every month and watch the total fall. In WhizBudget you can add debts as accounts and see them shrink alongside your savings, or use a simple chart on the fridge that you colour in for every $100 repaid.

5. Break the Goal Into Milestones

Paying off $15,000 is daunting; paying off the first $1,000 is achievable. Set milestones at every 10% or every closed account, and mark each one.

6. Celebrate Cheaply

Rewards keep you going, as long as they don't undo the work. A favourite meal at home, a day trip, or a small budgeted treat for each milestone keeps the effort feeling worthwhile.

7. Automate the Minimums

Set every minimum payment to go out automatically so a busy month never turns into a late fee. Then make your extra payment by hand: the act of sending it is a small win in itself.

8. Find Money That Doesn't Hurt

Cutting things you value is hard to sustain. Start with things you won't miss: unused subscriptions (try a subscription audit), bank fees, and impulse purchases. Every dollar found this way goes straight to the debt.

9. Plan for Setbacks

An unexpected bill or a weekend of overspending will happen. Treat it as a bad month, not a failed plan. Keep a small emergency buffer so surprises don't go back on a card, and read our guide on bouncing back after a budget setback.

10. Don't Do It Alone

Tell a partner or friend about your goal and your debt-free date. If you share finances, agree on the plan together; budgeting works far better when both people are on board.

What to Do When Motivation Runs Out

  • Look back, not forward: compare today's balance with where you started.
  • Recalculate your debt-free date; it's usually closer than it feels.
  • Lower the bar for one month: keep the minimums and a small extra payment, then build back up.
  • Remember the interest you're no longer paying on the debts you've already cleared.

Frequently Asked Questions

How long does it take to pay off debt?

It depends on your balances, rates and how much you pay each month. A payoff calculator gives you an exact date, and even small extra payments can shorten it by months.

Snowball or avalanche: which keeps you more motivated?

For most people the snowball method feels more motivating because accounts close sooner. The avalanche method saves more money. Either works if you stick with it.

Snowball vs. Avalanche: Which Debt Payoff Method is Best?

The Debt Avalanche and Debt Snowball methods are two popular strategies for paying off debt efficiently. The Debt Avalanche method prioritizes paying off high-interest debt first, reducing total interest costs. The Debt Snowball method focuses on paying off the smallest debt first, building motivation through quick wins.

Each method requires listing all your debts and making minimum payments on all but one, directing extra funds to either the highest-interest debt (Avalanche) or the smallest debt (Snowball). 

Not sure which one comes out ahead for your specific debts? Try our free debt payoff calculator to compare both side by side with your real numbers.


Quick Comparison: Snowball vs. Avalanche

FeatureDebt SnowballDebt Avalanche
Order of PaymentSmallest balance firstHighest interest rate first
FocusQuick wins & motivationCost efficiency & long-term savings
Best ForThose who need psychological boostsThose who want to minimize interest
Main DownsideMay pay more in interestProgress may feel slow initially

What is the Debt Snowball Method?

The Debt Snowball Method focuses on paying off debts from the smallest balance to the largest, regardless of interest rate.

How It Works:

List all your debts from smallest to largest balance.

Make minimum payments on all debts except the smallest one.

Allocate extra funds to pay off the smallest debt first.

Once it’s paid off, roll over the amount to the next smallest debt.

Repeat the process until all debts are cleared.

Pros of the Snowball Method:

✅ Provides quick wins, keeping you motivated.

✅ Simplifies the process, making debt repayment feel achievable.

✅ Works well for those who need psychological momentum.

Cons of the Snowball Method:

❌ Can result in higher overall interest costs.

❌ Not the most mathematically efficient method.


What is the Debt Avalanche Method?

The Debt Avalanche Method focuses on paying off debts by interest rate, starting with the highest.

How It Works:

List all your debts from highest to lowest interest rate.

Make minimum payments on all debts except the highest interest one.

Apply all extra funds toward paying off the highest interest debt first.

Once paid off, move to the next highest interest debt.

Repeat until you’re debt-free.

Pros of the Avalanche Method:

✅ Saves more money on interest over time.

✅ Eliminates high-interest debt faster.

✅ Best for those comfortable with long-term strategies.

Cons of the Avalanche Method:

❌ Can feel slow, leading to loss of motivation.

❌ Doesn’t provide quick wins, making it harder to stay committed.


Which Method is Right for You?

Choose Debt Snowball if you need quick motivation and enjoy crossing debts off your list faster.

Choose Debt Avalanche if you want to save the most money on interest and don’t mind playing the long game.

Hybrid Approach: Some people combine both—starting with Snowball for momentum, then switching to Avalanche to save on interest.


Final Thoughts

Both methods work if you stick to them. The best approach depends on your financial mindset—are you driven by quick wins or long-term savings?

No matter which method you choose, the key is to stay consistent, make extra payments whenever possible, and avoid accumulating new debt. Ready to take control of your finances? Use our free debt payoff calculator to see your exact payoff date and how much interest you could save with each method.

How to Take Control of Your Debt and Achieve Financial Freedom

Debt can feel overwhelming, but you can take control and work toward a debt-free future with the right approach. Managing debt effectively is about making smart financial choices, staying organized, and being proactive in paying off what you owe.

Understanding your debt is the first step. Make a list of all your debts, including balances, interest rates, and minimum payments. This helps you see the full picture and prioritize which debts to tackle first. High-interest debt, like credit cards, should typically be paid off first to minimize the amount you pay in interest over time.

Creating a budget that accounts for debt repayment is key. Track your income and expenses to find areas where you can cut back and allocate more toward paying off debt. Even small adjustments, like reducing dining out or subscription services, can free up extra cash for your payments.

Choosing a repayment strategy can help you stay on track. The debt snowball method focuses on paying off smaller debts first to build momentum, while the debt avalanche method prioritizes debts with the highest interest rates to save money in the long run. Pick the approach that keeps you motivated and aligns with your financial goals.

Negotiating with creditors is an option many people overlook. Some lenders may offer lower interest rates, reduced settlement amounts, or extended payment terms if you communicate with them. It never hurts to ask, and the savings can be significant.

Consolidating debt can make repayment easier by combining multiple balances into one loan with a lower interest rate. This simplifies payments and can reduce the total amount you owe over time. However, it’s important to research your options and ensure that debt consolidation is the right move for your situation.

Building an emergency fund while paying off debt might seem counterintuitive, but it can prevent you from relying on credit for unexpected expenses. Even setting aside a small amount each month can provide a safety net and keep you from accumulating more debt.

Staying disciplined and avoiding new debt is just as important as paying off existing balances. Try using cash or debit instead of credit, and only take on new debt when absolutely necessary. Responsible financial habits will help you maintain stability even after becoming debt-free.

Debt management isn’t about quick fixes, it’s about developing long-term financial habits that set you up for success. With a clear plan, dedication, and smart strategies, you can regain control of your finances and work toward a debt-free future.

Looking for more financial guidance? Explore our blog for practical debt management tips and money-saving strategies!